1 hr ago
UPI MDR Keeps Payments Cheap, While Cards Reward Big Purchases
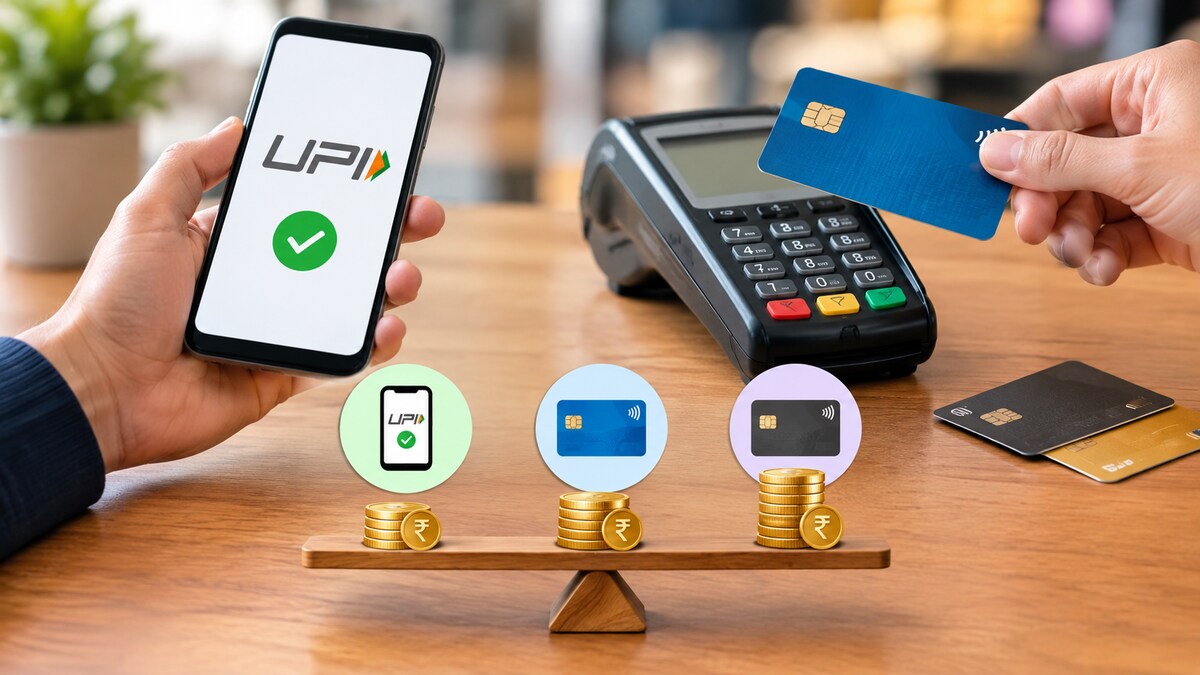
UPI is still free for people sending money to each other.
Many small purchases made at shops will also remain free for merchants.
For some larger shop payments, the shop will pay a small UPI processing fee.
Customers should not be charged that fee separately for using UPI.
UPI is generally cheaper for shops than accepting debit or credit cards.
Credit cards may still be useful because they can provide rewards, cashback or time to pay.
Debit cards take money directly from a bank account.
For expensive purchases, people should compare the final bill and all benefits before deciding.
The best payment method depends on the specific purchase, not just the payment technology.

Eligible UPI person-to-merchant payments above Rs 2,000 will carry a 0.4% merchant fee from October 15, capped at Rs 300.
UPI payments up to Rs 2,000, qualifying small-merchant transactions and all person-to-person transfers remain free under the stated framework.
The MDR is charged to merchants, not consumers, and should not appear as a separate UPI payment charge.
UPI remains cheaper than typical card acceptance costs, with debit-card MDR capped at 0.90% and credit-card MDR generally ranging from 1.5% to 2.5%.
For large purchases, consumers should compare final prices, discounts, fees, rewards, credit terms, limits and protections before choosing a payment method.
- Who
- The National Payments Corporation of India, merchants and consumers are affected; Adhil Shetty of BankBazaar and Prabhat Ranjan of Nexdigm provided comments.
- What
- A 0.4% MDR is being applied to eligible UPI person-to-merchant transactions above Rs 2,000, with a Rs 300 cap, while consumers remain free from a direct UPI charge.
- Where
- The framework applies to eligible UPI merchant payments in India.
- When
- The stated MDR framework applies from October 15; NPCI released its related FAQ on September 15.
- Why
- The policy sets a merchant-side processing charge while keeping UPI’s costs lower than those commonly associated with debit and credit cards.
UPI Cost and Convenience
Card Rewards and Credit Benefits
Everyday payments
UPI Cost and Convenience
UPI is likely to remain the natural choice for routine purchases because it is convenient, settles instantly and carries no consumer transaction charge.
Card Rewards and Credit Benefits
Debit or credit cards may be preferred where they are more widely accepted or provide useful offers and rewards.
Large purchases
UPI Cost and Convenience
UPI remains relatively inexpensive for merchants, and consumers avoid a direct MDR charge.
Card Rewards and Credit Benefits
Credit cards may be more attractive for high-value purchases when cashback, rewards, purchase protection or an interest-free credit period outweighs the benefits of UPI.
Pricing and fees
UPI Cost and Convenience
The MDR should be absorbed by merchants, and merchants may use genuine discounts to encourage lower-cost payment methods.
Card Rewards and Credit Benefits
Consumers should check for convenience fees, platform fees or surcharges because these can reduce or eliminate the value of card rewards or discounts.
Key facts
- UPI MDR
- 0.4% for eligible person-to-merchant payments above Rs 2,000.
- MDR cap
- Rs 300 per transaction for eligible payments above Rs 75,000.
- Consumer charge
- The MDR is a merchant cost and should not be recovered from consumers as a separate UPI fee.
- Exempt transactions
- Person-to-person UPI payments remain free; UPI payments up to Rs 2,000 and qualifying small-merchant transactions remain under the zero-MDR framework.
- Card comparison
- Debit-card MDRs are limited to 0.90%, while standard credit-card MDRs generally range from 1.5% to 2.5%.
- Example
- A Rs 10,000 eligible UPI payment would generate Rs 40 in MDR for the merchant.
- Transaction limit
- Standard UPI transactions are generally subject to a Rs 1 lakh per-transaction limit, although exceptions and lower bank limits may apply.
- Estimated impact
- The Government estimates that about 96% of UPI merchant transactions by volume will remain unaffected.
Quotes
National Payments Corporation of India (NPCI)
The organization operating and regulating India’s UPI infrastructure.
“For example, a Rs 10,000 eligible UPI payment would attract Rs 40 in MDR. Debit and credit card costs can vary based on the card, merchant and payment arrangement. When deciding between payment methods, look at the transaction value, applicable charges, available offers and rewards, and the payment terms attached to each option.”
 financialexpress.com
“Because the proposed UPI MDR is significantly lower than credit card fees and applies only above specific transaction thresholds, shopkeepers have no economic incentive to inflate retail shelf prices. Consumers will continue paying the exact listed price for goods and services.”
financialexpress.com
Prabhat Ranjan
Senior Director at Nexdigm.
“Transaction limits also matter. Standard UPI transactions are generally subject to a Rs 1 lakh per-transaction limit, although higher limits apply to specified categories and individual banks may prescribe lower limits. Consumers should therefore consider the final payable amount, rewards, payment limits, dispute protections and security, rather than choosing solely on the basis of the payment mode.”
financialexpress.com
Sources
Related news

NPCI Sets UPI MDR Below Traditional Card Charges

New UPI MDR Rules Keep Consumers Free, Charge Eligible Merchants
UPI, Debit and Credit Card MDR Costs Compared

UPI MDR Begins October 15, Merchants Face Charges, Customers Don’t
UPI Sets 0.4% MDR on High-Value Merchant Payments
Proposed UPI Fees Above Rs 2,000 Versus Credit Cards

EPFO Details to Check Before Filing a PF Withdrawal Claim

PIB Debunks Fake Free Laptop Scheme Applications Claim
Uttarakhand Media Delegation Studies Ecology and Urban Development
Government Denies Fake Viral Notification Claiming Public Sector Bank Mergers