

1 day ago
How to Correct a Closed Card Still Active on CIBIL
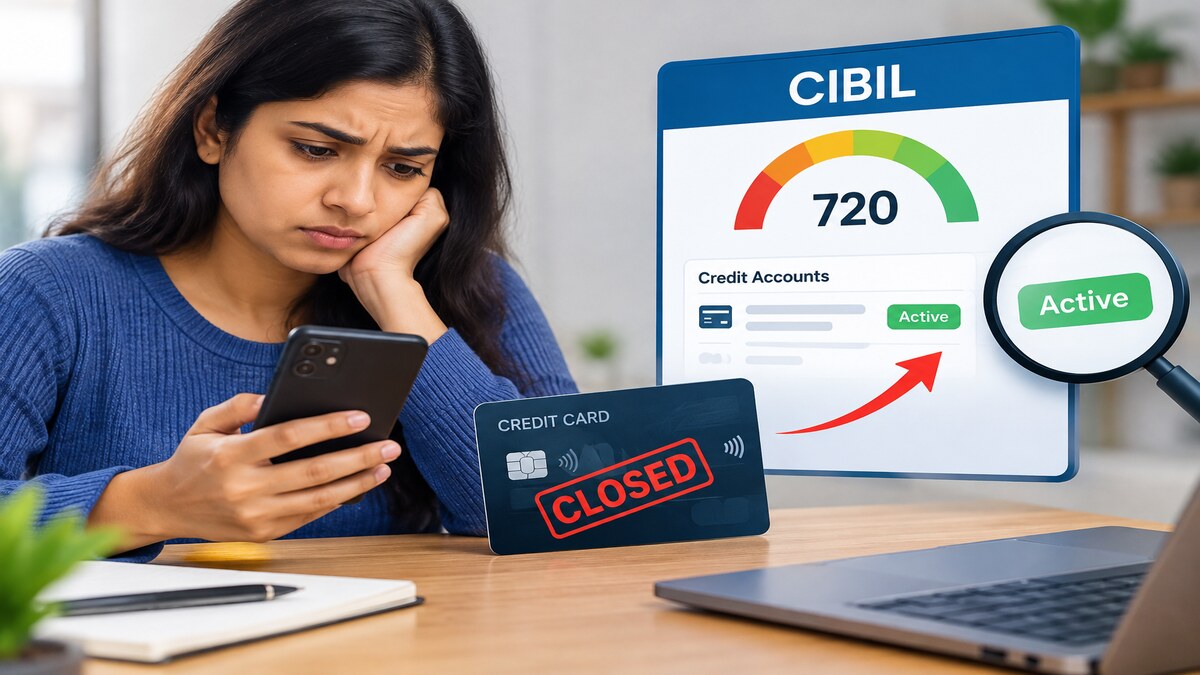
Sometimes a credit card is closed, but a credit report still says it is open.
This can happen when the card company has not sent the updated information to the credit bureau.
That mistake may confuse lenders when they review an application for a loan or another card.
It can also cause problems if the report shows money owed or activity the customer did not make.
Keep papers that prove the card was closed and paid off.
Contact the card company and file a dispute with the credit bureau, sharing those papers.
The article says the lender has 21 days to send corrected information, and the bureau has 30 days to resolve the dispute.
Check a new credit report afterward to make sure the correction appears.

Credit bureaus rely on lenders to report account closures, so a closed card may continue to appear active if the issuer has not updated its records.
An incorrectly active account may affect credit profiles or lender decisions, especially if it shows dues, missed payments, or activity the cardholder does not recognize.
Keep the closure confirmation, final zero-balance statement, proof of last payment, bank acknowledgment, and any No-Dues certificate.
Raise the issue with the lender and use the credit bureau’s dispute process, providing supporting documents; check a fresh credit report after the correction.
The article says lenders have 21 calendar days to submit revised information and the bureau has 30 days to resolve a dispute; eligible customers receive Rs 100 per day for delays beyond 30 days.
- Who
- Credit cardholders whose closed cards are still shown as active, along with their card issuers and credit bureaus.
- What
- How to dispute and correct an inaccurately active credit card entry on a credit report.
- Where
- On a CIBIL or other credit information report in India.
- When
- After a card has been closed and the report still shows it as active.
- Why
- Incorrect account status may affect a consumer’s credit profile and how lenders assess applications.
Key facts
- Lender response period
- 21 calendar days to submit revised credit information after a dispute is filed, according to the article.
- Bureau resolution period
- 30 days to settle the dispute, according to the article.
- Delay compensation
- Rs 100 for each calendar day of delay beyond 30 days, as stated in the article.
- Documents to retain
- Closure confirmation, final zero-balance statement, proof of last payment, and bank acknowledgment.
- Additional proof
- A No-Dues certificate, if available, can document that the card was closed without pending liabilities.
- Suggested escalation
- Raise the issue with the lender and credit bureau; the article also identifies the RBI Ombudsman mechanism for repeated failures after formal complaints.
Quotes
Ramkumar Subramanian
Partner at Grant Thornton Bharat.
“Once flagged, both the lender and the bureau must work to correct the record quickly, as credit-report accuracy is critical for consumers. A closed loan or credit card account should generally be reflected by credit bureaus within 30 days, and certainly within the next one or two reporting cycles.”
 financialexpress.com
“When a closed card is mistakenly shown as open, its credit limit remains part of your total available credit. Since you are not using this card, its outstanding balance is zero, which artificially lowers your overall credit utilization ratio.”
financialexpress.com
Sources
Related news

Repaid Loan Still Active? Steps to Correct Credit Reports

Why Credit Scores Drop Despite On-Time EMI Payments
How Indian Credit Bureaus Build And Update Your Profile
Closing a Credit Card May Leave EMIs and Other Obligations

Why an 800+ CIBIL Score Still May Not Secure Loans

EMI Bounces May Trigger Penalties and Credit Score Damage

Why Equal Credit Card Spending Can Affect Scores Differently
NBFCs Account for 47% of India's New Consumer Borrowers
Festive Two-Wheeler Loan Demand Rose Sharply in 2025
Getting a Personal Loan Without a Salary Slip in India
