

2 days ago
Repaid Loan Still Active? Steps to Correct Credit Reports

Paying your last loan installment does not always make the loan disappear from your credit report immediately.
Banks and other lenders send updated information to credit bureaus from time to time.
First, ask your lender whether it has officially closed the loan account.
Keep your closure letter, no-dues certificate and final payment receipt safe.
Then check whether the report says the account is closed.
Make sure the balance is zero and the closure date is correct.
Also look for wrong overdue amounts or loans that do not belong to you.
If the lender does not fix a mistake, you can file a dispute with the credit bureau.
Under applicable RBI rules, compensation may be available when an eligible complaint is not resolved within 30 days.

A repaid loan may remain marked as active temporarily because lenders update credit bureaus periodically.
Borrowers should first confirm with the lender that the account is officially closed.
Key documents include the closure letter, no-dues certificate, final payment receipt and account records.
Credit reports should be checked for account status, zero outstanding balance, closure date and payment-history errors.
If the lender does not correct the information, borrowers can dispute it with the relevant credit bureau; RBI rules may allow ₹100 per day in compensation for unresolved complaints after 30 days.
- Who
- Borrowers, lending institutions, credit bureaus and officials responsible for correcting credit information.
- What
- Guidance on correcting a credit report when a fully repaid loan still appears as active.
- Where
- On the borrower’s credit report and through the relevant lender or credit bureau’s dispute process.
- When
- After the borrower makes the final loan payment; updates may take time because lenders report information periodically.
- Why
- To ensure the loan is correctly shown as closed, with a zero balance and accurate closure date, and to prevent reporting errors from affecting the borrower’s credit profile.
Key facts
- First step
- Confirm with the lender that the loan account has actually been marked closed.
- Documents to retain
- Loan closure letter, no-dues certificate with acknowledgement details, final payment receipt and related account records.
- Status check
- The credit report should show the account as closed.
- Balance check
- The outstanding balance should be zero and match the final payment records.
- Date check
- The closure date should match the lender’s records.
- Dispute process
- If the lender does not correct the information, the borrower can dispute it with the credit bureau that issued the report.
- Possible compensation
- Under the applicable RBI framework, eligible complaints unresolved within 30 calendar days may attract compensation of ₹100 per calendar day.
Quotes
Kaushik Chatterjee
Founder and CEO of lendingplate
“Borrowers should not assume that repayment automatically means their credit report will be updated immediately. Once a loan is closed, they should review the account status, outstanding balance and closure date on their report. In case of a mismatch, approaching the lender with the closure records should be the first step, followed by a formal dispute if the issue persists.”
 livemint.com
“After a loan is fully repaid, there can sometimes be a gap before the closure status is reflected on the borrower’s credit report. Borrowers should first confirm the closure with the lender and retain the relevant documentation. If the account continues to show as active, they can raise a dispute with the credit bureau and submit supporting documents for correction.”
livemint.com
Sources
Related news

After Final Home Loan EMI, Collect These Essential Documents

RBI Sets ₹5,000 Daily Compensation for Delayed Property Papers

Credit Report Mistakes Can Increase Loan Costs, Expert Explains

Why Credit Scores Drop Despite On-Time EMI Payments
How Indian Credit Bureaus Build And Update Your Profile
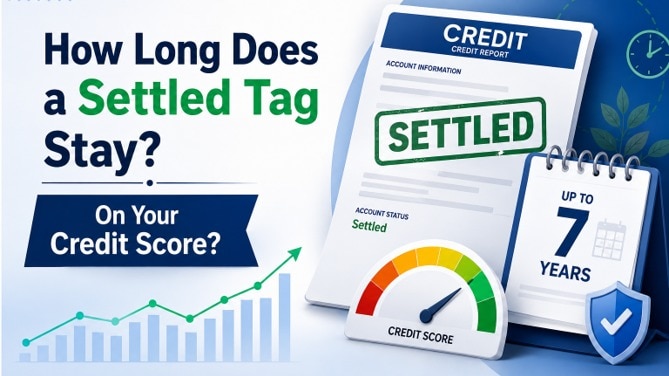
How Long Does a Settled Loan Tag Affect Credit?

India’s 7% Growth Faces Capital, Investment and Judicial Hurdles

NPCI Says UPI Charges May Affect Limited Transaction Value

Bajaj Finance Details Personal Loan Amounts, Rates And Tenures
Bank Strike From September 28 to 30 Prompts Customer Advisory
Indian Markets Tumble as Oil, Yields and War Intensify
