7 hrs ago
Why a Large Retirement Corpus May Still Fall Short
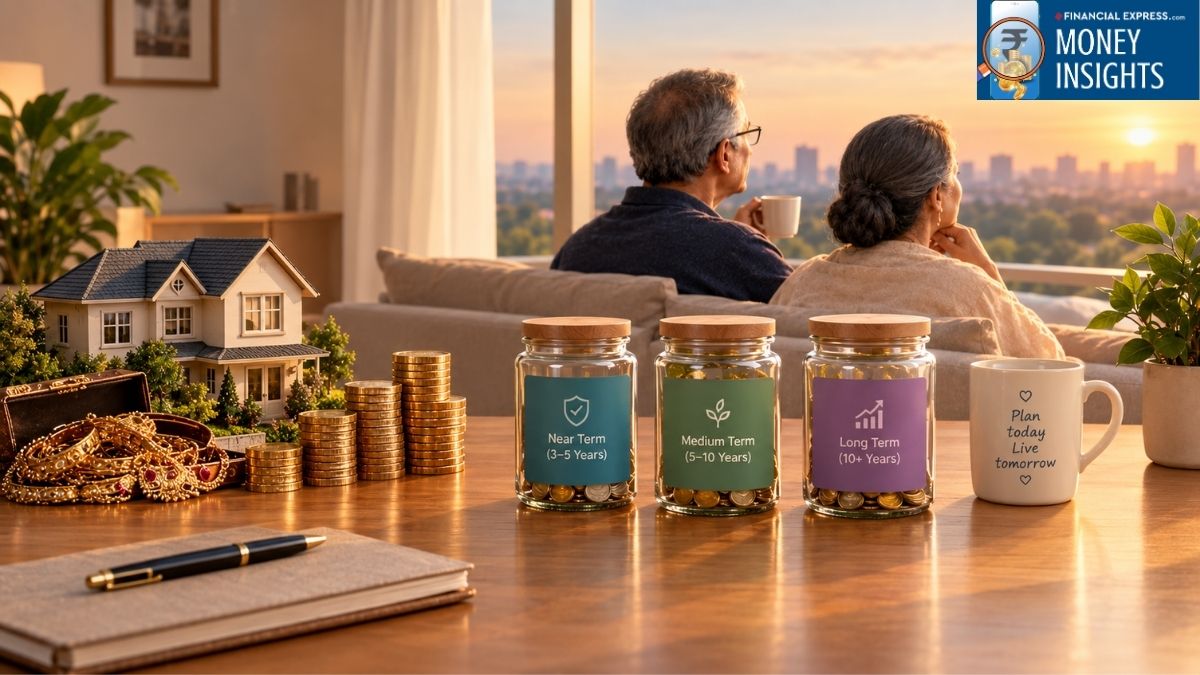
Owning a valuable house or gold does not always give you money to spend each month.
Retirement plans need to turn some savings into regular income.
The article shows an example of ₹2 crore in savings and monthly costs of ₹1 lakh.
If prices rise by 5% each year, those costs grow over time.
Even if the savings earn 6% a year, rising withdrawals can gradually use up the money.
Medical bills can also be large and hard to predict.
One idea is to keep money for the next few years somewhere safe and easy to access.
Money not needed for a long time may still be invested for growth.
The plan should be checked and adjusted as needs change.

A valuable home and gold can raise net worth without generating regular retirement income.
The article says retirees should balance liquid, lower-risk assets for near-term needs with growth investments for later years.
In an illustration, a ₹2-crore corpus earning 6% annually may be largely exhausted around 20 years if initial monthly expenses are ₹1 lakh and inflation is 5%.
Healthcare and emergency costs can be unpredictable, so the article recommends planning for them separately.
A bucket strategy can match investments to when funds are needed, with regular reviews as expenses and risk tolerance change.
- Who
- People planning for or living in retirement, including retirees with substantial assets.
- What
- An explanation of how to structure retirement savings so they can support spending over time.
- Where
- India.
- When
- As people approach retirement and throughout retirement.
- Why
- To show why net worth alone may not provide enough retirement income as expenses, inflation and healthcare needs change.
Key facts
- India's population aged 60+
- Nearly 138 million in 2021, projected to reach around 194 million by 2031, according to the Ministry of Statistics and Programme Implementation's Elderly in India 2021 report.
- Illustrative retirement corpus
- ₹2 crore.
- Illustrative starting expenses
- ₹1 lakh per month, or ₹12 lakh annually.
- Illustrative assumptions
- 5% annual inflation and 6% annual corpus returns.
- Projected monthly expenses
- About ₹1.63 lakh after 10 years and ₹2.65 lakh after 20 years.
- Illustrative corpus balance
- About ₹1.64 crore after 10 years and ₹98 lakh after 15 years; it may be largely exhausted around year 20, before taxes, major medical costs or weaker returns.
- Near-term liquid reserve example
- Three years of current expenses would amount to about ₹36 lakh for annual expenses of ₹12 lakh.
- Healthcare expenditure figure
- LASI reported mean out-of-pocket expenditure of around ₹31,933 for the last inpatient visit at a private health facility among people aged 60 and above.
Quotes
Rahul Bhagat
CEO of DSP Pension Fund
“Net worth measures what you own; retirement is lived on what those assets pay you.”
 financialexpress.com
Sources
Related news

Longer Lives, Rising Healthcare Costs Reshape Retirement Planning in India

How Much Can a ₹2 Crore Retirement Fund Provide?

Three-Bucket Retirement Strategy Targets Income, Goals and Growth

India’s ₹1 Crore Retirement Benchmark Faces Growing Doubts
Parents' FDs, pensions versus today's SIPs: Which retirement is safer?

FIRE Aspirations Grow as Indians Rethink Retirement Security
Survey Finds Few Indians Use Public Transport to Work
Faith Drives Nearly Half of India’s Overnight Trips
India Growth Boosts Confidence as Indonesia Seeks Stronger Economic Ties
Factory wages rose 5% as Jharkhand recorded only decline