

6 hrs ago
Parents' FDs, pensions versus today's SIPs: Which retirement is safer?
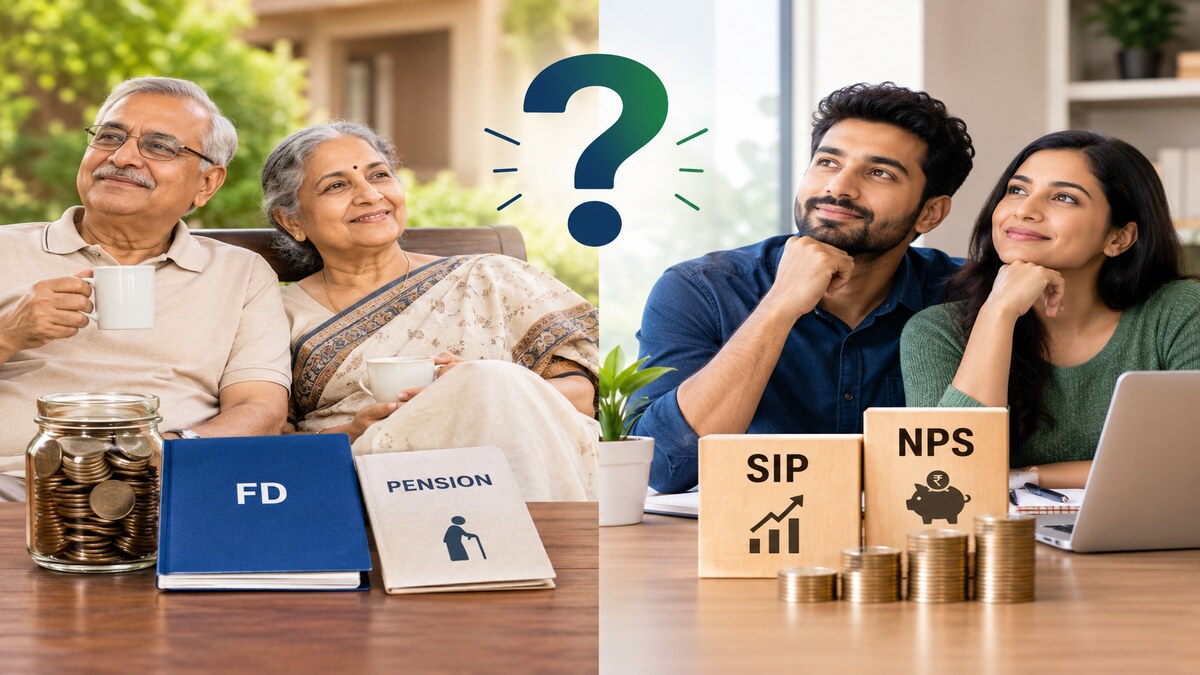
Many parents received pensions that paid them regularly after they stopped working.
Some also used fixed deposits and provident funds to save money.
These investments felt safe, but high inflation reduced the value of their returns.
Today, many people use SIPs and the National Pension System to build a retirement fund.
These investments can grow more over time, but their values can rise and fall.
The newer system does not automatically promise a monthly income for life.
Retirees must decide how much money to keep safe, how much to invest for growth and how much to convert into an annuity.
Keeping one or two years of expenses in safer investments can help during market downturns.
Therefore, neither generation is always safer: older workers had more income certainty, while younger investors have more growth opportunities but greater responsibility.

Older retirees often benefited from defined-benefit pensions, provident funds and relatively predictable fixed-income returns.
High 1990s interest rates were partly offset by inflation, so their real returns were much lower than the headline rates.
Today's NPS and SIP investors have greater growth potential but must manage market, inflation, longevity and withdrawal risks.
Annuities can provide certainty, while equity exposure can help protect purchasing power over a long retirement.
Retirement security now depends on combining income planning, diversified investments, liquidity reserves and disciplined withdrawals.
- Who
- Retirees and workers planning retirement, including government employees under the old pension framework and investors using SIPs and NPS.
- What
- A comparison of retirement security under traditional pensions, FDs and provident funds versus SIPs and NPS.
- Where
- India.
- When
- The comparison covers the 1990s generation, current investors and retirement periods that may last 25–30 years.
- Why
- Modern investors must create their own retirement income while managing inflation, market volatility, longevity, healthcare and withdrawal risks.
Traditional pension-and-FD model
SIP-and-NPS model
Income certainty
Traditional pension-and-FD model
Defined-benefit pensions provided formula-based income and, for eligible employees, inflation-linked Dearness Relief, reducing the need to build a retirement corpus independently.
SIP-and-NPS model
NPS creates a corpus rather than guaranteeing a pension, so investors must plan withdrawals, annuities and income sustainability.
Growth and inflation protection
Traditional pension-and-FD model
FDs and other fixed-income products offered predictable returns but could lose purchasing power when inflation exceeded or nearly matched the interest rate.
SIP-and-NPS model
SIPs and NPS provide access to equity and other market assets, offering greater long-term growth potential but without guaranteed returns.
Main retirement risks
Traditional pension-and-FD model
The main concerns are inflation, reinvestment risk and whether fixed-income returns remain adequate over a long retirement.
SIP-and-NPS model
The main concerns include market volatility, sequence-of-returns risk, longevity, withdrawal discipline, behavioural mistakes and converting the corpus into regular income.
Key facts
- 1990s FD rates
- State Bank of India FD rates peaked at about 13% in 1995–96.
- 1990s inflation
- Consumer price inflation averaged roughly 9–10% in the mid-1990s, including 10.22% in 1995 and 8.98% in 1996.
- Old Pension Scheme
- Eligible government employees generally received a formula-based pension broadly linked to 50% of emoluments or average emoluments, subject to applicable rules.
- NPS contributions
- For covered Central Government employees, the employee contributes 10% of Basic plus Dearness Allowance, while the Government contributes 14%.
- NPS introduction
- NPS began for new Central Government employees on January 1, 2004, and opened to all citizens from May 1, 2009.
- Normal NPS exit
- Under the All Citizen Model, normal exit can permit up to 80% as a lump sum and requires at least 20% as an annuity, subject to applicable rules and thresholds.
- Inflation illustration
- At 6% annual inflation, monthly expenses of Rs 1 lakh today could rise to about Rs 5.74 lakh in 30 years.
Quotes
Vishwajeet Goel
Head of Pensionbazaar
“Retirement planning comes down to having a strong enough corpus to last for 25-30 years and which keeps up with inflation. Guaranteed income will come with staying invested for the long term. Equity will allow the investor to build a large corpus size, which will provide both inflation and longevity protection.”
 financialexpress.com
“Due to this concept, many investors avoid equity altogether. However, the simple solution to this is to separate your short-term income needs from your long-term growth corpus. Keeping 1-2 years of expenses in a liquid or short-duration debt fund means you never have to sell equity during a downturn.”
financialexpress.com
Sources
Related news
IIM Indore Study Finds NPS Gaps, UPS Shifts Pension Costs
Why Indians Need Regular Retirement Income Beyond Their Corpus

How to Keep Retirement Income Steady While Investing

Why Young Workers May Add NPS Alongside EPF

Longer Lives, Rising Healthcare Costs Reshape Retirement Planning in India
India’s 2026 Pension Plans: Expert Picks and Annuity Options

NPS Swasthya to Combine Pension Savings With Health Cover
UPS Railway Pension Estimates After 10, 20 and 25 Years

NPS Vatsalya: How Parents Can File Online Grievances
NPS Swasthya Sets Health Cover, Withdrawal and Insurance Rules
