

Business · Markets · 3 hrs ago
Analysts split on Mesoblast, Transurban and NextDC shares
Three analysts have given different ratings to shares in Mesoblast, Transurban and NextDC, companies listed on Australia's S&P/ASX 200 index.
Bell Potter rates biotech company Mesoblast a buy, pointing to upcoming results from trials for adult graft-versus-host disease and chronic lower back pain.
Those results are expected in the first half of 2027, and clinical trials carry risks.
Gray Perry Wealth Advisers rates toll-road operator Transurban a hold after its agreement to buy more interests in Sydney toll roads.
The deal may support future earnings, but funding needs, debt and interest rates could limit near-term benefits.
Lazarus Capital Partners rates data-centre company NextDC a sell, saying debt and other funding costs may weigh on returns before new capacity begins generating income.
The ratings reflect differing analyst views, and the trial results and ability of new data-centre capacity to earn returns remain ahead.

Analysts have issued differing recommendations on shares in Mesoblast, Transurban and NextDC.
Bell Potter rates Mesoblast a buy, citing expected revenue growth and upcoming clinical trial results.
Gray Perry Wealth Advisers rates Transurban a hold, pointing to its toll-road interests but also higher funding needs and leverage.
Lazarus Capital Partners rates NextDC a sell, citing debt-funded spending and the risk that interest costs will weaken returns.
The article reports that all three shares were down over the past 12 months.
- Who
- Analysts from Bell Potter, Gray Perry Wealth Advisers and Lazarus Capital Partners assessed shares in Mesoblast, Transurban and NextDC.
- What
- Their recommendations were buy for Mesoblast, hold for Transurban and sell for NextDC.
- When
- The article was published on October 11, 2026.
- Where
- The companies are listed on the Australian Securities Exchange; Transurban operates toll roads in Australia and North America.
- Why
- Analysts weighed Mesoblast's growth prospects and upcoming trial results, Transurban's acquisition and funding needs, and NextDC's spending, debt and interest costs.
This story does not have two clearly opposing sides.
The short term outlook for Mesoblast's revenue growth remains highly attractive.
Dependable earnings is challenged by limited immediate upside.
In our view, rising interest costs could squeeze returns before new capacity starts paying its way.
An interim readout on Mesoblast's adult GvHD study is expected.
Headline data from Mesoblast's chronic lower back pain trial is due.
- Mesoblast rating
- Buy; Bell Potter's 12-month price target is $4.45
- Transurban rating
- Hold; its share price was reported at $13.15
- Transurban deal
- $4.5 billion acquisition of additional interests in Sydney toll roads
- NextDC FY2026 revenue
- $496.5 million, up 16 per cent on the prior corresponding period
- NextDC FY2026 capital expenditure
- $3.397 billion
- NextDC share price
- Fell from $16.37 on June 4 to $10.23 on October 8
Sources
Related news
King River starts 11,000-metre gold drilling program in Western Australia
Adidas sues White Fox over four-stripe clothing designs

ASX rises as MAAS shares fall after Firmus cancels planned IPO

Taruga Minerals prepares 1,000-metre drilling campaign in Papua New Guinea
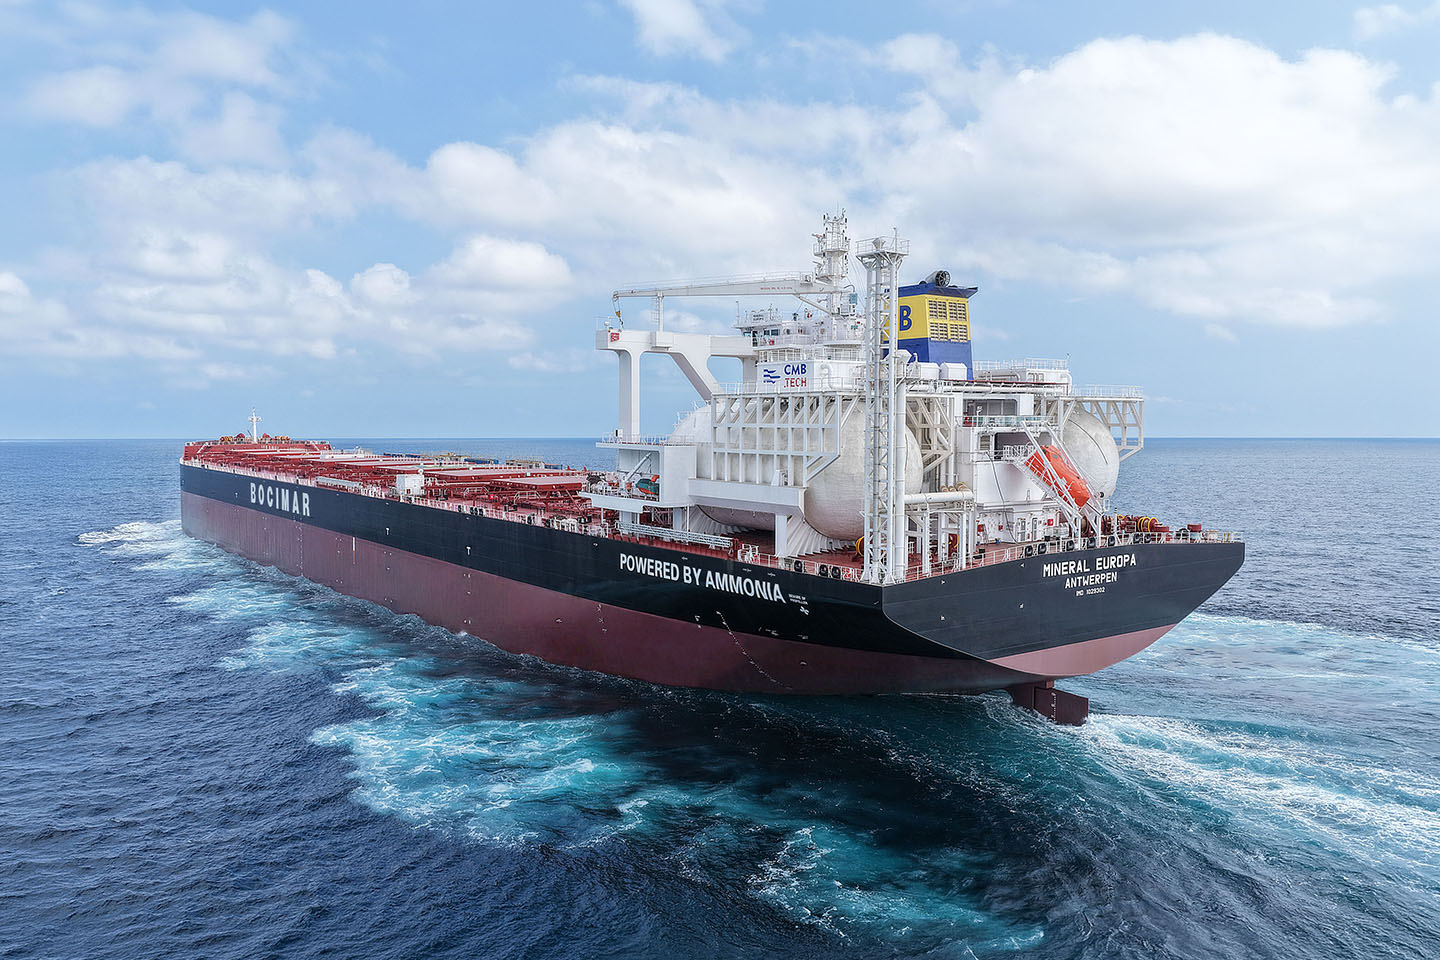
Ammonia-powered iron ore bulk carrier sets sail for the Pilbara
Lynas and Sonic Healthcare shares hit 52-week lows
Arafura signs larger rare earths offtake deal

Everest completes 7,877m of drilling at Revere gold project

BOA reports copper across more than 400m at Ricci Lee

Coles raises in-store paper bag price from 25 cents to 30 cents
WiseTech and Nextdc offer different prospects for investors
