5 days ago
₹12 Lakh Investments Exposed Emergency Cash Gap Despite Insurance
A Reddit user had money invested but could not quickly use most of it.
His mother needed emergency hospital care at about 2 am.
The hospital asked for an advance payment before admission.
The insurance process could not begin immediately because the TPA office was closed.
The user borrowed money through a friend’s UPI transfer and used his credit cards.
His mother later became stable.
The experience taught him that investments are not the same as cash that can be used instantly.
Other people advised keeping emergency savings in easily accessible accounts and having health insurance that is not only linked to a job.

An unnamed Reddit user said ₹12 lakh was invested while only ₹18,000 was immediately accessible.
The user’s mother needed hospital admission during a 2 am emergency, but the TPA office was closed until morning.
The user relied on a friend’s UPI transfer and maxed out credit cards to arrange the advance payment.
The experience highlighted that investments and corporate health insurance may not provide instant access to cash.
Other users recommended keeping six to 12 months of expenses in liquid emergency funds and maintaining separate health insurance.
- Who
- An unnamed Reddit user, his mother, and other members of the r/IndianPersonalFinance community.
- What
- A hospital emergency exposed the user’s difficulty accessing cash despite investments and health insurance.
- Where
- In a hospital casualty ward and on Reddit’s r/IndianPersonalFinance community.
- When
- The emergency occurred at about 2 am; the Reddit post was shared two weeks before the article.
- Why
- The hospital required an advance payment, while the TPA office was closed until morning, delaying access to the insurance process.
Liquidity and Independent Coverage
Investments and Employer Insurance
How to prepare for emergencies
Liquidity and Independent Coverage
Keep emergency money in readily accessible instruments such as fixed deposits or liquid funds, rather than prioritizing maximum returns.
Investments and Employer Insurance
The user had focused on stocks and long-term funds, but the experience showed that invested wealth may not be available instantly when needed.
Reliance on corporate health insurance
Liquidity and Independent Coverage
Corporate insurance may involve paperwork delays, out-of-pocket costs, and the risk of losing coverage if employment ends; commenters recommended separate policies for individuals and parents.
Investments and Employer Insurance
The user had ₹10 lakh of corporate health insurance, which was expected to help with medical costs but could not immediately solve the advance-payment problem.
Borrowing during emergencies
Liquidity and Independent Coverage
Commenters said liquid savings or an overdraft against a fixed deposit could reduce reliance on credit cards or gold.
Investments and Employer Insurance
The user used a friend’s transfer and maxed out credit cards because cash and insurance access were unavailable at the time.
Key facts
- Investments
- ₹12 lakh, according to the user
- Health insurance
- ₹10 lakh, reportedly through corporate health insurance
- Immediately accessible funds
- ₹18,000
- Emergency timing
- Around 2 am
- Short-term funding
- A friend arranged a UPI transfer, and the user maxed out credit cards
- Patient’s condition
- The user said his mother was doing okay afterward
- Suggested emergency reserve
- Some commenters recommended keeping six to 12 months of expenses liquid
Quotes
A Reddit commenter
A participant in the r/IndianPersonalFinance discussion
“You need to be investing in a proper health insurance policy, one for yourself and your spouse. If there is any, get one for your parents that at least covers up to ₹1 crore.”
 businesstoday.in
“This is precisely the reason why an emergency fund should be kept liquid for immediate access. Don’t try to maximise gains on emergency fund money.”
businesstoday.in
Sources
Related news
Why Indian Health Insurance Policyholders Still Pay Hospital Bills
Cashless Health Insurance Still Leaves Policyholders With Out-of-Pocket Costs

SEBI Financial Health Quiz Reviews Insurance, Savings, Debt
India Building Collapse Raises Questions About Health Insurance Coverage

Best Practices for Filing Health Insurance Claims in India

NPS Swasthya Sets 25% Medical Withdrawal and Insurance Rules
Indian Tech Workers Debate Shift From Salary Talk To Layoffs
Reddit User Quits Job Alleging Extreme Workplace Surveillance
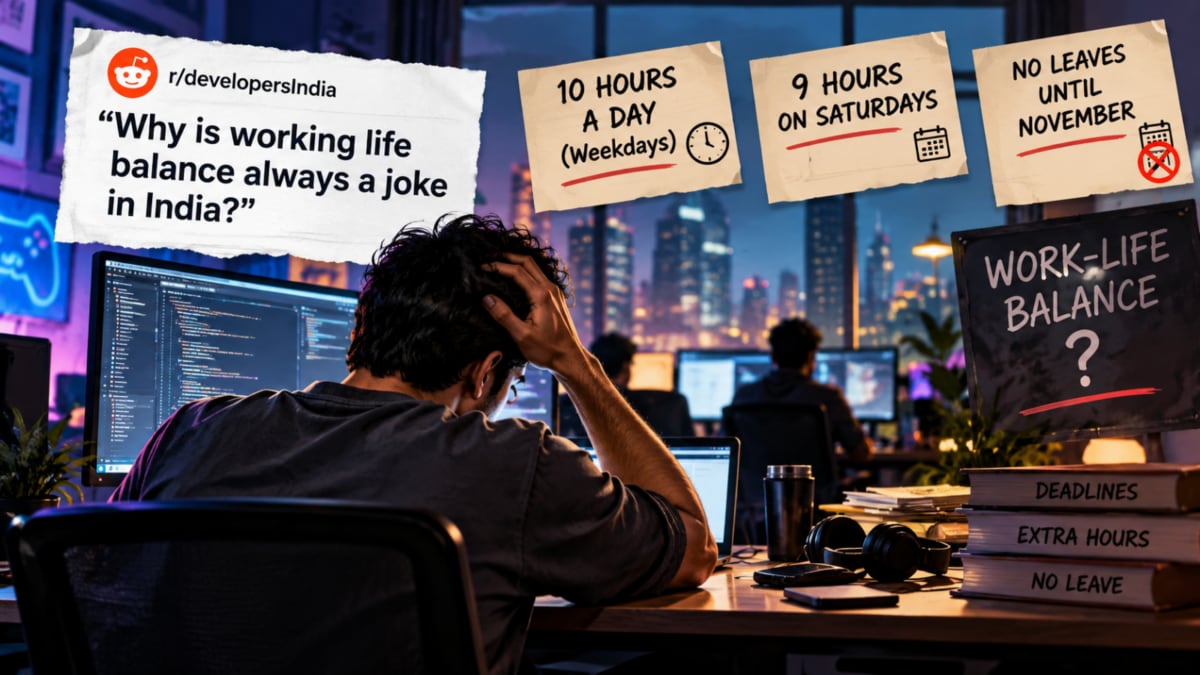
Bengaluru Gaming Firm Employee Claims Long Hours, Leave Freeze

Bengaluru 2BHK Rent, ₹4 Lakh Deposit Sparks Housing Debate