4 days ago
NPS Swasthya Sets 25% Medical Withdrawal and Insurance Rules

NPS Swasthya is a pension account designed to help people pay for certain healthcare costs.
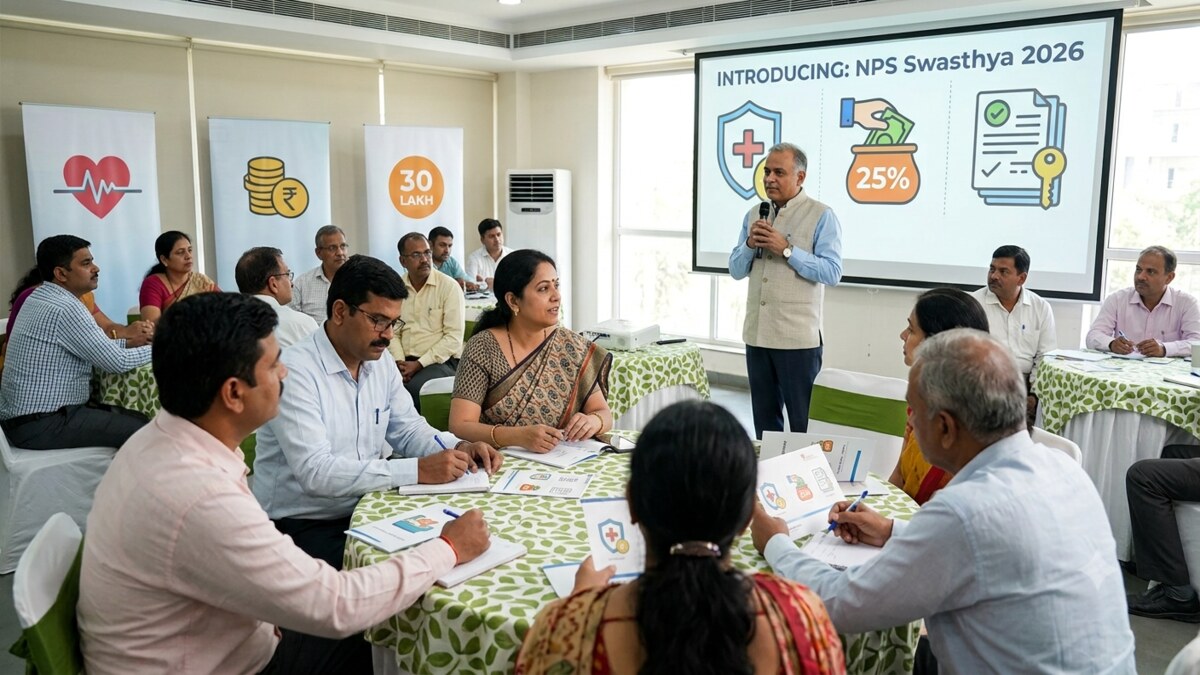
People can take out up to 25% of what they contributed for approved medical expenses.
The money is paid to a hospital or healthcare provider rather than directly to the subscriber.
Subscribers must also buy a separate family health insurance policy.
The policy can cover between ₹1 lakh and ₹30 lakh, depending on the deductible chosen.
It covers the subscriber, spouse and up to two dependent children, but not parents.
If there is not enough money to renew the insurance, the subscriber should receive advance warnings when possible.
If the premium is still unpaid, the account closes and is moved into another NPS arrangement.
The insurance has waiting periods, including 12 months for pre-existing and specified diseases or procedures.

Subscribers can withdraw up to 25% of their NPS Swasthya contributions for eligible healthcare expenses.
The scheme requires a separate super top-up family-floater insurance policy with cover options from ₹1 lakh to ₹30 lakh.
Healthcare withdrawals have no stated limit on frequency or mandatory waiting period, but payments go directly to providers.
If insurance premiums remain unpaid after the grace period, the account closes and transfers to an All Citizen Model NPS scheme.
Insurance covers the subscriber, spouse and up to two dependent children, with parents excluded.
- Who
- Individuals eligible to join the National Pension System can enrol in NPS Swasthya.
- What
- The Pension Fund Regulatory and Development Authority issued final rules for a healthcare-focused pension account linked to mandatory super top-up insurance.
- Where
- The rules apply to the NPS Swasthya account and its associated insurance policy; no specific location is stated.
- When
- The final guidelines were issued on September 18.
- Why
- The scheme is intended to combine retirement savings with access to healthcare benefits.
Key facts
- Healthcare withdrawal limit
- Up to 25% of contributions made to the NPS Swasthya account.
- Insurance requirement
- A separate super top-up health insurance policy is mandatory for enrolment.
- Insurance cover options
- Family-floater sums insured are ₹1 lakh, ₹5 lakh, ₹10 lakh or ₹30 lakh.
- Covered family members
- The subscriber, spouse and up to two dependent children; parents are excluded.
- Entry and renewal ages
- Standard policy entry is 18 to 70 years; renewal may continue through age 85, subject to policy terms and law.
- Insurance lapse consequence
- If the renewal premium remains unpaid after the grace period, the NPS Swasthya account closes and is transferred to an All Citizen Model NPS scheme.
- Waiting periods
- The initial waiting period is 30 days except for accidents; pre-existing and specified diseases or procedures have a 12-month waiting period, subject to policy terms.
Sources
Related news
NPS Swasthya Sets Health Cover, Withdrawal and Insurance Rules
PFRDA Nears NPS Swasthya Launch, Explores Guaranteed Returns

PFRDA Plans October Launch of Health-Focused NPS Swasthya Product

NPS Vatsalya Rules Govern Withdrawals, Exits, and Account Conversion
Cashless Health Insurance Still Leaves Policyholders With Out-of-Pocket Costs
India’s Health Insurance Providers Highlight Coverage, Cashless Care and Renewals

NPS Vatsalya: How Parents Can File Online Grievances
How Indian PPF and NPS Tier II Change After Relocation
PFRDA Plans UPI Pension Accounts, Guaranteed Returns and Health Cover