15 hrs ago
Titagarh Rail Systems Sees Growth From Passenger Rail Push
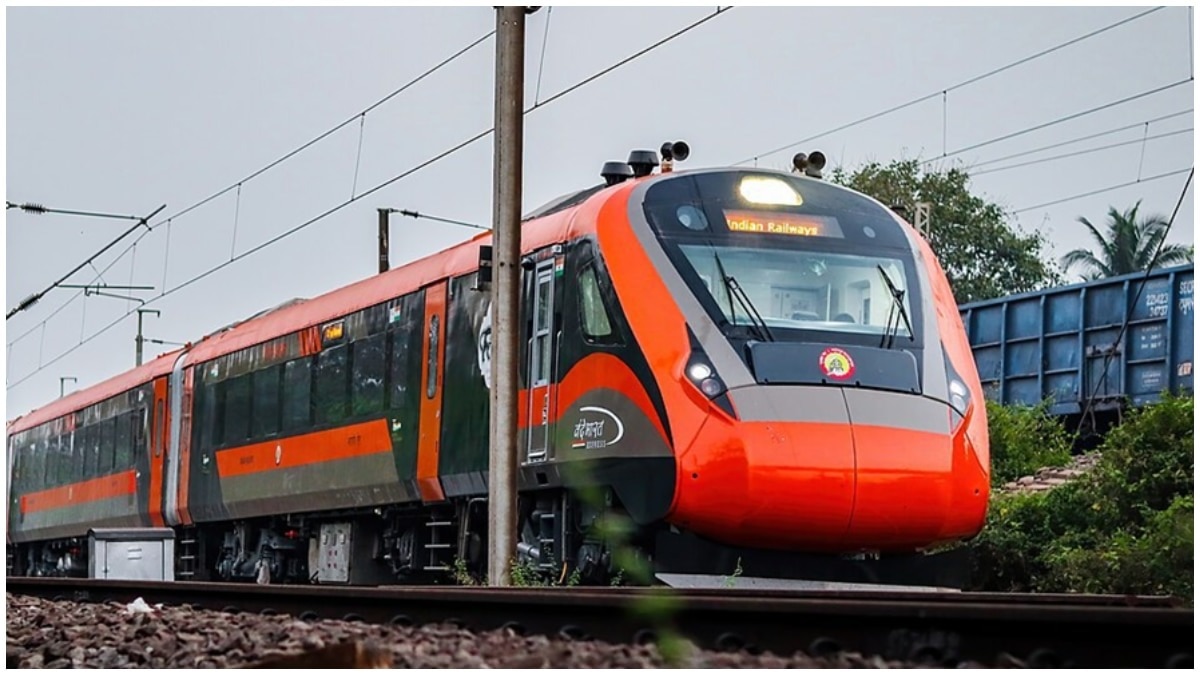
Titagarh Rail Systems makes train coaches and freight wagons.
It works on passenger trains such as metro coaches and Vande Bharat trains.
It also makes wagons used to carry goods by rail.
The company’s freight orders are currently not very large.
However, analysts think its passenger business could grow strongly.
Titagarh is also trying to make propulsion systems inside the company.
This could help it earn better margins over time.
ICICI Securities gave the stock an ADD rating and set a target price of Rs 966.
The analyst expects profits to grow quickly between FY26 and FY29.

Titagarh Rail Systems is positioned across passenger rolling stock, including metro coaches and Vande Bharat trains, and freight wagons.
ICICI Securities expects passenger-segment execution to support revenue and profit growth despite modest freight orders.
The company is developing in-house propulsion-system manufacturing capabilities to strengthen its passenger business and potentially expand margins.
Indian Railways aims to increase rail freight’s modal share to 45% from about 22% in 2025 and move 3.3 billion tonnes annually by 2030.
ICICI Securities initiated coverage with an ADD rating, a Rs 966 target price, and projected 52% annualized profit growth for FY26-FY29.
- Who
- Titagarh Rail Systems and ICICI Securities.
- What
- Titagarh Rail Systems is expected to grow through passenger rolling stock, while developing in-house propulsion capabilities and maintaining a freight business.
- Where
- The business is tied to India’s rail network and Indian Railways.
- When
- The outlook covers FY26 to FY29, with freight targets extending to 2030.
- Why
- Passenger-segment execution, potential propulsion-system capabilities, a diversified business, and a healthy balance sheet could offset slower freight-order growth.
Growth Case
Constraints and Risks
Passenger versus freight momentum
Growth Case
Strong execution in passenger rolling stock, including metro coaches and Vande Bharat trains, could sustain revenue and profit growth.
Constraints and Risks
The freight segment has a modest order book, and current orders may be completed within FY27, limiting near-term freight momentum.
Propulsion manufacturing
Growth Case
Building in-house propulsion-system capabilities could strengthen the passenger business and support margin expansion.
Constraints and Risks
The articles describe this as a plan for the next few years, so its eventual contribution is not yet established.
Long-term freight opportunity
Growth Case
Indian Railways’ targets for higher rail freight share and 3.3 billion tonnes of cargo by 2030 could support future tender activity.
Constraints and Risks
The timing of future tenders is uncertain, and the company’s near-term freight outlook remains muted.
Key facts
- Coverage view
- ICICI Securities initiated coverage with an ADD rating.
- Target price
- Rs 966 over 12 months.
- Profit outlook
- Profit after tax is projected to grow at a 52% compound annual growth rate from FY26 to FY29.
- Passenger products
- Metro coaches and Vande Bharat trains.
- Freight outlook
- Current freight orders could be executed within FY27, while the freight order book remains modest.
- Balance sheet
- Net debt to EBITDA is about 0.5 times, with return on equity around 10% to 13%.
- Rail freight target
- Indian Railways aims to handle 3.3 billion tonnes of cargo by 2030, compared with 1.67 billion tonnes in FY26.
Sources
Related news
Titagarh and Siemens explore international metro projects together

India’s Freight Corridor Gains Spur Push for National Grid

Railway Stocks Rise After Government Approves Major Infrastructure Projects
More Vande Bharat Sleeper Trains Delayed Until March 2027
Jefferies Cuts Jupiter Wagons Target, Sees 27% Downside
Indian Railways Expands Passenger Services as August Freight Loading Rises
Saraighat Bridge Completes Rs 7-Crore Rehabilitation for Safer Travel
Bulldozers Begin Ranchi Encroachment Drive Amid Protests Over Evictions
Jammu Railways Launches Cement Freight, Revises Station Access

Assam’s Railway Network Fully Electrified After Final Hill Section Completed