2 hrs ago
Jefferies Sees 22-46% Upside in Major Hospital Stocks
Jefferies is a brokerage that studies companies and recommends investments.
It believes several Indian hospital companies could see their share prices rise by 22-46%.
The companies include Apollo Hospitals, Fortis, Max Healthcare, Manipal, Medanta, and Dr Agarwal's Healthcare.
Hospitals may earn less if the government limits prices or profit margins on some medical supplies and cancer medicines.
Jefferies estimates this could reduce hospital EBITDA, a measure of operating profit, by 2-5%.
However, it says hospitals may respond by adjusting procedure prices and cutting costs.
Earlier rules on stents and implants also caused temporary pressure before some stocks recovered.
Jefferies therefore considers the recent correction a possible buying opportunity, although regulatory risks remain.

Jefferies recommended buying hospital stocks, citing strong demand for quality tertiary-care beds and sector fundamentals.
The brokerage set target prices of Rs 10,350 for Apollo Hospitals Enterprise Ltd, Rs 1,125 for Fortis Healthcare Ltd, and Rs 1,260 for Max Healthcare Institute Ltd.
It also set targets of Rs 870 for Manipal Health Enterprises Ltd, Rs 1,660 for Medanta Ltd, and Rs 600 for Dr Agarwal's Healthcare.
Jefferies estimated that price caps on consumables and oncology drugs could reduce hospital EBITDA by about 2-5% if hospitals cannot pass on the impact.
The brokerage said regulatory concerns have historically caused short-term stock consolidation but often created attractive buying opportunities.
- Who
- Jefferies and the hospital companies covered in its analysis, including Apollo Hospitals Enterprise Ltd, Fortis Healthcare Ltd, Max Healthcare Institute Ltd, Manipal Health Enterprises Ltd, Medanta Ltd, and Dr Agarwal's Healthcare.
- What
- Jefferies recommended buying the hospital stocks and assigned target prices implying potential upside of 22-46%.
- Where
- India.
- When
- In the latest Jefferies analysis; the Supreme Court gave the Government of India until 12 October for inter-departmental consultations on oncology-drug margins.
- Why
- Jefferies said strong demand and sector fundamentals outweigh the potential effect of price regulation, while recent stock corrections have lowered valuations.
Regulatory Risk View
Jefferies' Bullish View
Price controls and profitability
Regulatory Risk View
A 16% margin cap on oncology drugs and a 5% margin cap on consumables could reduce hospital EBITDA by about 2-5% if the costs cannot be passed on.
Jefferies' Bullish View
Hospitals have several ways to offset price reductions, including staggered procedure-price increases and cost rationalisation.
Stock-market outlook
Regulatory Risk View
Reports about possible regulation of hospital charges, medical devices, consumables, and drug margins have pressured hospital stocks.
Jefferies' Bullish View
Jefferies said earlier regulatory episodes typically caused three to six months of consolidation before recovery and created attractive entry points.
Sector valuation
Regulatory Risk View
Regulatory uncertainty could weigh on hospital earnings and investor sentiment.
Jefferies' Bullish View
Jefferies said valuations have corrected to 20x-27x FY28 EV/EBITDA from 25x-35x a year earlier, making companies with sustainable high-teens EBITDA growth attractive.
Key facts
- Brokerage view
- Jefferies recommended buying hospital stocks.
- Potential upside
- The target prices imply 22-46% upside.
- Apollo target
- Rs 10,350 for Apollo Hospitals Enterprise Ltd.
- Other targets
- Rs 1,125 for Fortis Healthcare Ltd; Rs 1,260 for Max Healthcare Institute Ltd; Rs 870 for Manipal Health Enterprises Ltd; Rs 1,660 for Medanta; and Rs 600 for Dr Agarwal's Healthcare.
- Revenue exposure
- Consumables account for 12-15% of hospital revenue, while oncology drugs account for 4-6%.
- Estimated EBITDA impact
- Jefferies estimated a 2-5% EBITDA hit under assumed margin-cap scenarios if hospitals cannot pass on the impact.
- Current valuation
- Hospital stocks were estimated to trade at an implied 20x-27x FY28 EV/EBITDA, compared with 25x-35x a year earlier.
Quotes
Jefferies
Brokerage providing the hospital-sector investment recommendation
“We believe sector fundamentals remain strong with robust demand for quality tertiary care beds. Post the correction, hospitals stocks trade at an implied 20x-27x FY28 EV/Ebitda valuation as compared to 25-35 times valuation a year ago. For companies which can offer sustainable high-teens Ebitda growth, we believe the correction offers an excellent entry point. Fortis, Manipal, Apollo, Max Health and Medanta is our pecking order.”
 businesstoday.in
“Past regulatory overhangs have led to stock consolidation, but have typically proved attractive entry points in a sector with strong fundamentals. BUY Hospitals,”
businesstoday.in
Sources
Related news
Brokerages See Hospital Stocks Rising Despite Supreme Court Scrutiny

Nomura Maintains Neutral Fortis Healthcare Rating Amid Growth Concerns

PL Capital Recommends Fortis Healthcare Shares, Sets ₹1,050 Target
Jefferies names four healthcare stocks with earnings upside
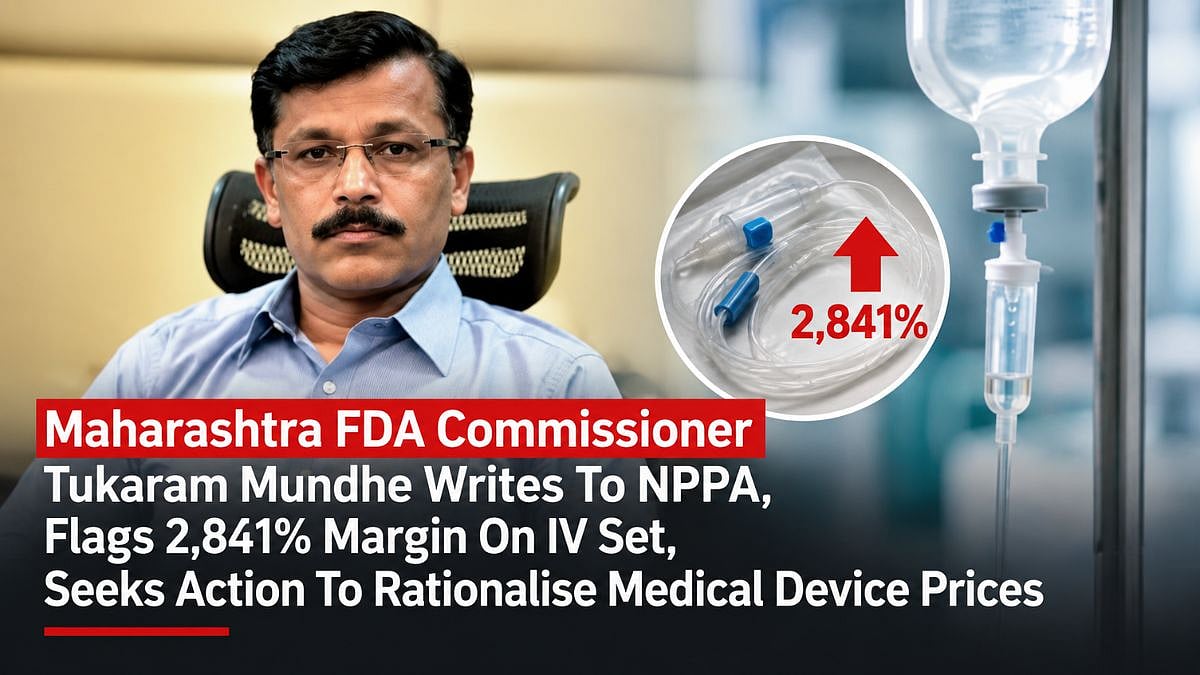
Maharashtra FDA Flags Huge Markups on Hospital Consumables

Supreme Court Draws Line Between Tax Delay and Default
Supreme Court Weighs Balanced Firecracker Curbs for Dussehra, Diwali
Letters Debate Bulk Buying, Elections, Drug Prices And Food Standards