15 hrs ago
India Property Market Balances Higher Rates Against Growth Prospects

India’s central bank raised the cost of borrowing money.
This could make home loans more expensive and make some people wait before buying a home.
Real estate executives say people still need homes, and businesses still need places to work and serve customers.
They also say better roads, connections and growing cities can help property markets.
Different kinds of property may be affected in different ways.
Homes depend a lot on what buyers can afford.
Offices and shops depend more on businesses and customers.
In places such as Shirdi, hotels and other visitor-related properties depend on people travelling there.
The market’s future will depend on how costs and demand change.

The Reserve Bank of India raised its repo rate by 25 basis points to 5.5% and shifted its policy stance from Neutral to Calibrated Tightening.
Higher borrowing costs could affect mortgage affordability, buyer sentiment and the timing of property purchases.
Industry executives say long-term housing needs, business expansion, infrastructure development and demand for quality spaces could support real estate activity.
Residential demand is especially sensitive to financing costs, while commercial property depends more on occupier demand, business activity and investment interest.
Executives highlighted emerging-market opportunities in Dehradun and Shirdi, where housing demand and hospitality prospects are linked to local development and visitor flows.
- Who
- The Reserve Bank of India and India’s real estate sector, including residential, commercial, retail and hospitality businesses.
- What
- The RBI raised the repo rate by 25 basis points to 5.5% and changed its policy stance from Neutral to Calibrated Tightening, prompting discussion about effects on property markets.
- Where
- India, with examples including the Tricity region, Punjab, Dehradun and Shirdi.
- When
- The article is dated October 9; it does not state the year.
- Why
- The article attributes the rate increase to inflationary pressures, including elevated crude prices and the evolving global financial environment.
Near-term rate pressures
Long-term demand supports
Housing affordability
Near-term rate pressures
Higher borrowing costs may raise mortgage payments, affect purchasing power and influence when buyers purchase homes.
Long-term demand supports
Executives say enduring housing needs and end-user demand may remain resilient, and that a single rate increase is unlikely to change underlying demand.
Property investment outlook
Near-term rate pressures
The effects of tighter financing, inflation, liquidity and interest-rate changes could weigh on financing decisions and consumer sentiment.
Long-term demand supports
Executives point to business expansion, infrastructure development, urbanisation and demand for quality assets as reasons the sector’s longer-term prospects remain positive.
Key facts
- Repo rate increase
- 25 basis points
- New repo rate
- 5.5%
- Policy stance
- Changed from Neutral to Calibrated Tightening
- Potential residential impact
- Higher financing costs may affect affordability, purchasing power and purchase timing.
- Commercial property factors
- Occupier demand, business expansion, infrastructure and investment appetite.
- Emerging-market examples
- Dehradun housing demand and Shirdi hospitality opportunities.
Quotes
Uddhav Poddar
CMD of Bhumika Group
“While higher borrowing costs may create some near-term pressure on financing and consumer sentiment, we believe the long-term outlook for real estate and hospitality remains positive.”
 theprint.in
“The RBI’s decision to raise the repo rate is a measured response to the renewed inflationary pressures from elevated crude prices and the evolving global financial environment.”
theprint.in
Sources
Related news
Rate Hike Pressures Affordable Buyers as Luxury Housing Holds Firm
RBI Rate Hike Tests Festive Housing Demand, Experts See Resilience
RBI Rate Hike May Test Housing Demand, Auto Impact Limited
RBI Rate Hike May Gradually Pressure Affordable Housing
RBI Rate Hike Could Affect Home, Car and Property Decisions
RBI Raises Repo Rate to 5.50% as Inflation Pressures Broaden
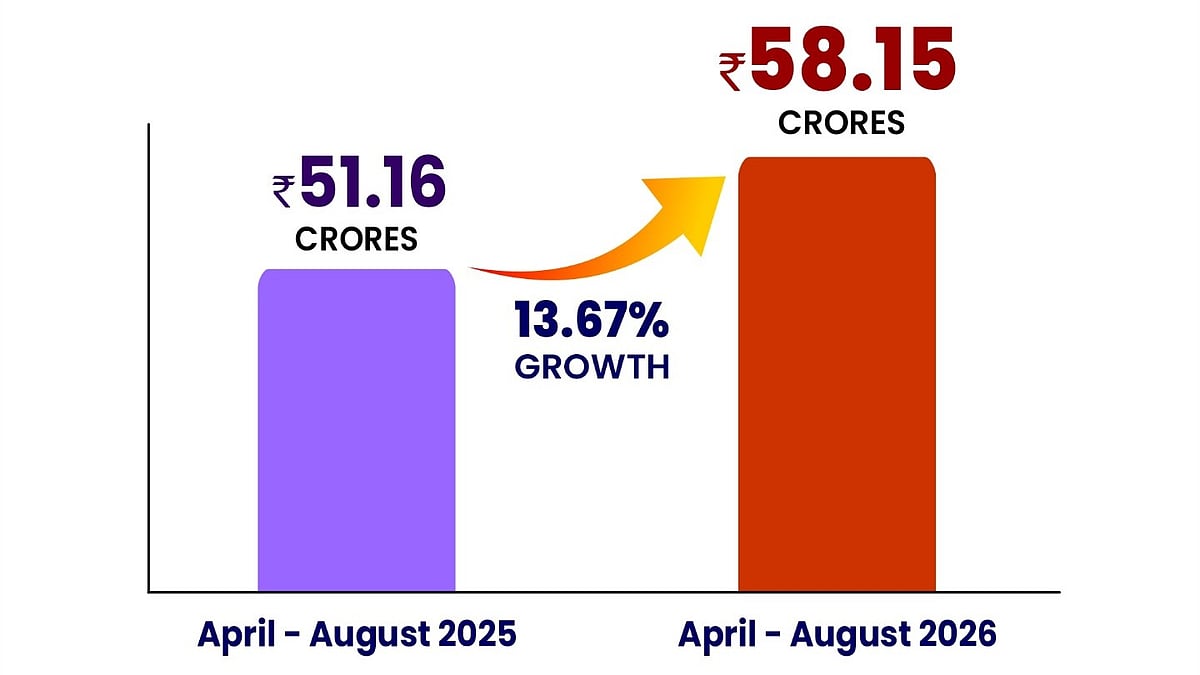
Central Railway Reports Rs 58.15 Crore Non-Fare Revenue
Cyber fraud victims and innocent account holders face frozen funds
84 Religious Organisations Register Online For Simhastha Kumbh 2027
Rishi Kapoor’s Karz Struggle: Depression, Drinking and Blaming Marriage