1 hr ago
Retirement at 60 May Not Cover Care Costs at 80
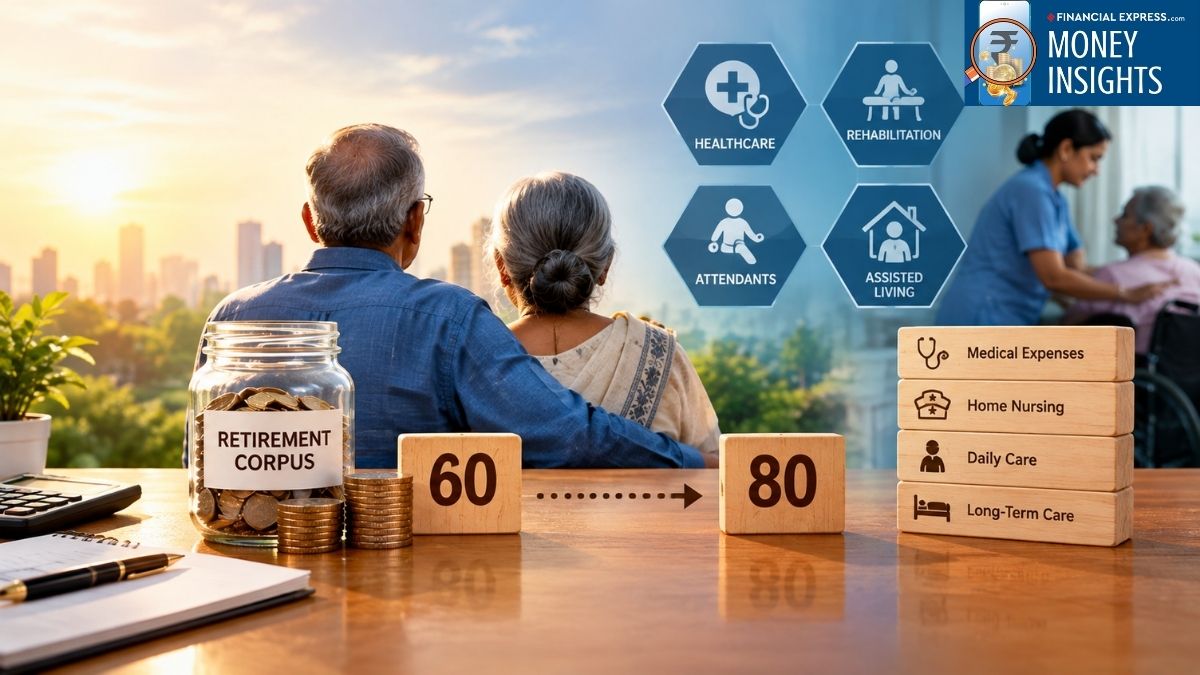
Many people save money so they can stop working at 60.
But people may live for many more years, and their needs can change as they get older.
They may need more medicine, therapy, help at home, or professional caregivers.
These costs can rise faster than ordinary prices.
The article says a retirement plan should set aside money that can be accessed quickly in an emergency.
It also suggests planning how to take money out of investments and considering possible care needs, not just current bills.
This can help savings last longer.

The article warns that a retirement corpus sized for routine expenses at 60 may not cover later-life healthcare and caregiving needs.
India’s elderly population is projected to reach nearly 193 million by 2030, while government projections put the number aged 60 and above at around 23 crore by 2036.
Medical inflation in India is forecast at 11.5% in 2026; the article estimates a ₹1 lakh treatment today could cost about ₹8.8 lakh in 20 years at that rate.
Financial experts recommend planning for long-term care, accessible emergency funds, healthcare costs beyond current spending, and tax-aware withdrawal strategies.
Paid caregiving could add substantial recurring costs: the article estimates three years at ₹30,000 monthly would cost ₹10.8 lakh.
- Who
- People planning for retirement in India, especially those who may need healthcare or caregiving in later life.
- What
- The article outlines six costs and planning risks that may make a retirement corpus inadequate in old age.
- Where
- India.
- When
- The risks may arise during retirement, particularly as people age beyond 60; some projections cited are for 2030, 2036 and 2026.
- Why
- Longer lifespans, rising medical costs, changing care needs and paid caregiving can put pressure on retirement savings.
Conventional planning assumptions
Risks highlighted by the article
How spending changes
Conventional planning assumptions
Retirement may reduce expenses such as commuting, work clothes and children’s education.
Risks highlighted by the article
Later-life medicines, rehabilitation, home nursing and paid caregiving can add significant recurring costs.
Estimating healthcare costs
Conventional planning assumptions
A general inflation assumption or current medical spending may seem sufficient for projecting future expenses.
Risks highlighted by the article
The article argues medical inflation can be much higher than general inflation, and future care needs may differ from current spending.
Retirement savings strategy
Conventional planning assumptions
A large accumulated corpus may appear to be the main measure of readiness.
Risks highlighted by the article
The article says retirees also need accessible reserves and a tax-aware withdrawal plan to meet expenses without mistiming asset sales.
Key facts
- Elderly population projection
- A 2025 UNFPA India–ORF report projects nearly 193 million older people in India by 2030.
- Government projection
- The number of Indians aged 60 and above could reach around 23 crore by 2036.
- Daily living limitations
- Government data citing the Longitudinal Ageing Study in India says 23.8% of people aged 60 and above have at least one limitation in activities of daily living.
- Medical inflation forecast
- Aon’s 2026 Global Medical Trend Rates Report forecasts Indian medical inflation of 11.5%.
- Illustrative treatment cost
- At 11.5% annual increases, a ₹1 lakh treatment would cost roughly ₹8.8 lakh after 20 years.
- Caregiving estimate
- Three years of caregiving at ₹30,000 per month would cost ₹10.8 lakh; at ₹50,000 per month, it would cost ₹18 lakh.
- Retirement horizon
- The article says someone retiring at 60 may need a corpus to support them for another 25 to 35 years.
Sources
Related news
Why a Large Retirement Corpus May Still Fall Short
Indians Raise Retirement Corpus Target as NPS Interest Grows

India’s ₹1 Crore Retirement Benchmark Faces Growing Doubts

Three-Bucket Retirement Strategy Targets Income, Goals and Growth
Most Urban Indians Want Early Retirement, Report Finds

FIRE Aspirations Grow as Indians Rethink Retirement Security
Central Team Begins Maharashtra Drought Assessment Visit
Banks Prepare for Quantum Computing’s Future Encryption Threat
India Needs to Rethink Skills for Changing Job Markets
Rajiv Kumar Says Private Investment Is Key to Double-Digit Growth