1 hr ago
India’s Insurance Reforms Aim to Curb Commissions, Expand Coverage

India’s insurance industry covers fewer people than it could.
Some insurers pay very large commissions to distributors who sell their policies.
These payments grew much faster than new insurance business between FY23 and FY25.
High commissions can leave less money available for policyholders.
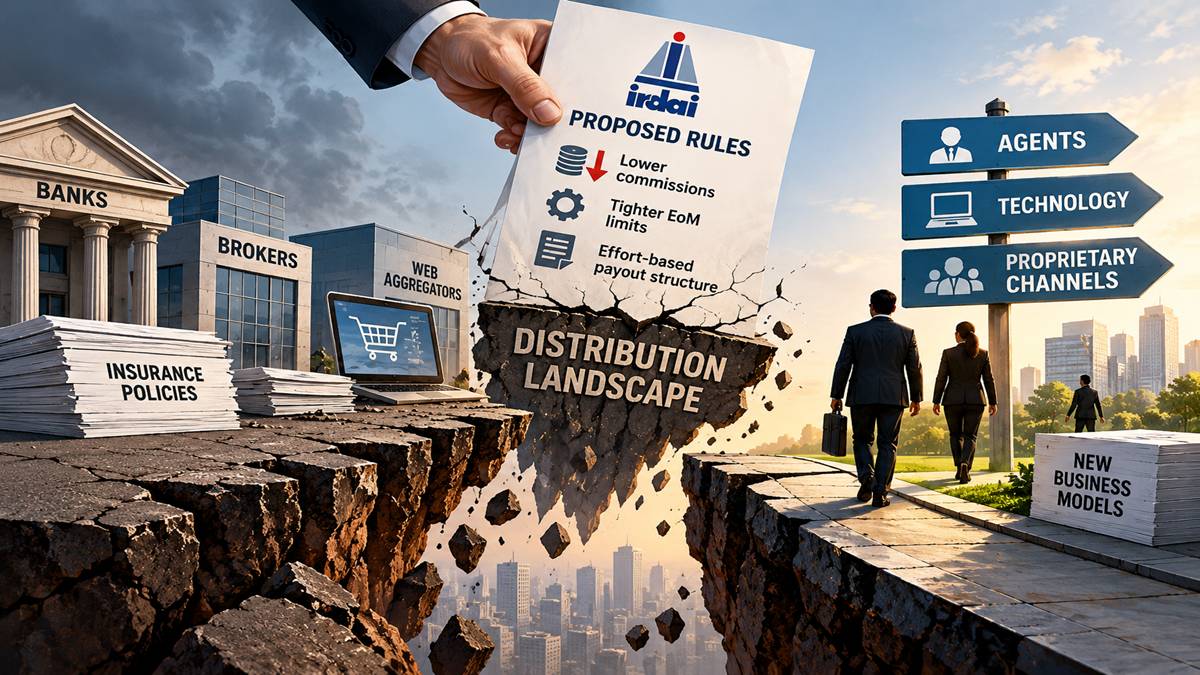
A new consultation paper suggests reducing insurers’ allowed expenses over five years.
It also proposes limits on commissions for life, health, motor and other insurance products.
Policies sold with loans would have commissions below 5%, while some mandatory motor-insurance commissions would be removed.
The regulator is also being urged to audit companies, punish violations and teach customers more about insurance.

India’s insurance sector ranks tenth globally but faces low penetration, mis-selling and poor policy persistency.
Distributor remuneration rose 125% from FY23 to FY25, while new business premiums increased 28%.
Commissions now represent 27% of first-year premiums and can reach 45% for policies bundled with loans.
The Insurance Regulatory and Development Authority of India proposed lower expense limits and category-specific commission caps.
The regulator should strengthen audits, penalize non-compliance and improve policyholder education, the editorial argues.
- Who
- The Insurance Regulatory and Development Authority of India, insurers, distributors and policyholders.
- What
- A consultation paper proposes tighter controls on insurer expenses and distributor commissions while seeking broader insurance coverage.
- Where
- India’s insurance sector.
- When
- The editorial was published on September 28, 2026; the consultation paper was released the previous week.
- Why
- To curb mis-selling and excessive payouts, protect policyholders and expand insurance access, including among underserved informal MSME sectors.
Consumer protection and stricter controls
Operational flexibility and industry discretion
Commission limits
Consumer protection and stricter controls
Caps are needed to reduce excessive distributor payouts, prevent malpractices and preserve more value for policyholders.
Operational flexibility and industry discretion
Category-wise limits may reduce insurers’ operational freedom and should be reviewed after five years.
Insurance bundled with loans
Consumer protection and stricter controls
Commissions below 5% could help limit incentives for policies sold alongside bank and NBFC loans.
Operational flexibility and industry discretion
The proposed channel-specific limits may constrain how insurers design and distribute products.
Regulatory enforcement
Consumer protection and stricter controls
Cost audits, surveillance and temporary bans on issuing fresh policies could improve compliance.
Operational flexibility and industry discretion
The consultation paper’s rules will need effective implementation without unnecessarily restricting legitimate business activity.
Key facts
- Global standing
- India’s insurance sector is described as the tenth largest globally.
- Premium growth
- New business premiums grew 28% from FY23 to FY25.
- Distributor remuneration
- Total distributor remuneration increased 125% over the same period.
- First-year commissions
- Commissions account for 27% of first-year premiums.
- Loan-linked policies
- Commissions on some policies sold with bank and NBFC loans can reach 45%.
- Proposed life-insurance EoM limit
- Expenses of Management would move down to 10% over five years.
- Proposed general-insurance EoM limit
- Expenses of Management would move down to 20% over five years.
- Proposed audit threshold
- Cost audits would cover insurers and distributors earning more than ₹100 crore in commissions.
Sources
Related news
IRDAI Proposes Hard Commission Caps and Lower Insurer Expenses
IRDAI Proposes Insurance Distribution Overhaul To Curb Mis-Selling

IRDAI Proposes Sweeping Overhaul of Insurance Distribution Rules
IRDAI Proposes Overhaul to Cut Commissions and Mis-selling
IRDAI Commission Cuts Set to Reset Insurance Distribution Models
IRDAI Proposes Insurance Reforms Targeting Commissions, Bundling and Dark Patterns
IRDAI Plans Claims, Grievance and Product Reforms After Distribution Overhaul
Generali Central Warns EoM Cuts Could Strain Smaller Insurers

Insurance Stocks Face Pressure as IRDAI Proposes Distribution Reforms