

16 hrs ago
IRDAI Commission Cuts Set to Reset Insurance Distribution Models
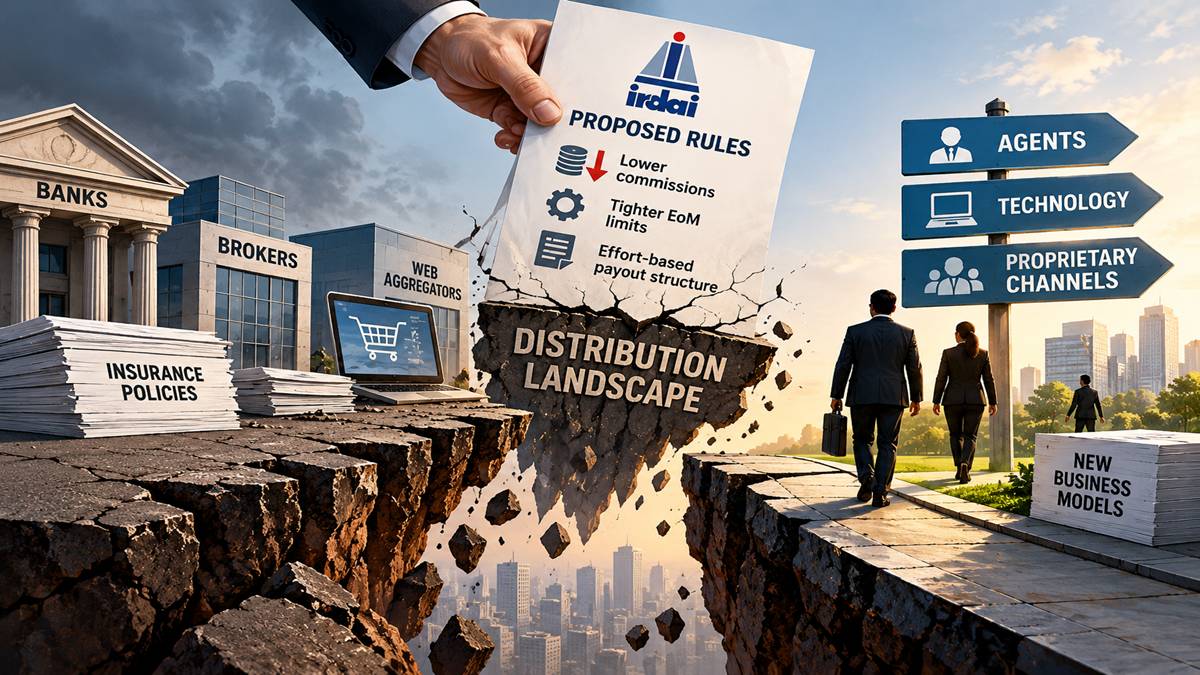
India’s insurance regulator wants to change how insurance sellers are paid.
The plan would lower commissions and limit how much insurers can spend on selling policies.
It would pay agents and other sellers differently depending on the work they do.
Some insurers and distributors worry that the cuts could make parts of their businesses too difficult to run.
They say some sellers may leave and insurance growth could slow.
Banks could also earn less because they receive fees for selling insurance.
The regulator says the changes could make insurance cheaper and reduce misleading sales.
Supporters also believe spreading payments over time could discourage people from cancelling policies unnecessarily.
Insurers may need to invest more in technology and their own agent networks.

IRDAI has proposed lower commissions and stricter expense-of-management limits across life, health and general insurance.
Life insurers would face EoM limits of 15% within two years and 12.5% within five years, while non-life insurers would face a 20% limit within five years.
The effort-based structure would favor agency distribution, with first-year life commissions proposed at 6.25%-25% for agents and 5%-20% for other intermediaries.
Industry executives and analysts warn that sharp cuts could make some distribution models unviable, slow insurance growth and reduce bank fee income.
Supporters say staggered and lower commissions could reduce policy costs, mis-selling and policy churn, while analysts expect limited overall profit effects for most banks.
- Who
- The Insurance Regulatory and Development Authority of India, insurers, agents, brokers, banks, distributors and policyholders are affected.
- What
- The regulator has proposed lower insurance commissions, effort-based payouts and stricter expense-of-management limits across life, health, motor and other general insurance products.
- Where
- India.
- When
- The consultation paper was published on September 24, 2026; the proposed EoM limits would be implemented over two and five years.
- Why
- The regulator says the reforms would lower distribution costs, curb mis-selling and produce more sustainable outcomes for policyholders.
Reform Supporters
Industry Critics
Consumer protection
Reform Supporters
IRDAI and consumer advocates say lower or staggered commissions could reduce policy costs, mis-selling and unnecessary policy churn while encouraging need-based advice.
Industry Critics
An insurance distributor official said the proposals reverse the 2023 EoM changes and could increase compliance costs without benefiting policyholders.
Distribution viability
Reform Supporters
Supporters argue that reducing distribution costs can make insurance more affordable and improve long-term value for customers.
Industry Critics
Insurers, distributors and analysts warn that steep cuts could make non-agency distribution unviable, reduce growth and make insurance selling a less attractive profession.
Impact on banks and distributors
Reform Supporters
Analysts expect the effect on most banks’ profits to remain limited, while lower commissions could reduce costly distribution practices.
Industry Critics
Reduced bancassurance commissions could affect private-sector banks’ fee income, while companies such as PB Fintech and Turtlemint could face significant earnings pressure.
Key facts
- Life-insurance EoM limits
- 15% of gross direct premium income within two years and 12.5% within five years.
- Non-life EoM limit
- 20% of gross direct premium income within five years, compared with the existing 30%.
- Proposed life commissions
- First-year commissions of 6.25%-25% for agents and 5%-20% for brokers, bancassurance entities and web aggregators.
- Health commissions
- First-time-policy commissions for distributors are proposed at 15%-20%; renewal and porting commissions are proposed at 5% for distribution entities and 10% for agents.
- Credit-life commission
- Single-premium credit-life commissions would be capped at 2%, compared with reported average effective payouts of about 45%.
- Bancassurance pool
- IIFL Capital estimated the banking-system bancassurance pool at $2.2 billion, equal to 10% of banks’ fee income.
- Estimated bank impact
- IIFL Capital expects the effect on banks’ profit after tax to be in the low single digits.
Quotes
Insurance Regulatory and Development Authority of India
India’s insurance regulator explaining its assessment of bancassurance costs and commissions
“The bancassurance channel therefore emerged as one of the costliest channels for insurance distribution. Rather than translating into lower costs or better outcomes for customers, the significant customer access available to bancassurance entities appears to be contributing to the maximisation of commission income”
 financialexpress.com
“We all have to go back to our shareholders. We have to go back and understand the basics of the business when we started. What were the assumptions of these models?”
financialexpress.com
financialexpress.com
Emkay Research
Research firm commenting on the proposed distribution reforms
“Bancassurance commissions constitute an important source of fee income for many banks, particularly private sector banks. Any reduction in commission payouts could therefore affect earnings from this business, though the impact is not expected to be material for most banks,”
 thehindubusinessline.com
“However, the drastic cut in distribution commission would also make insurance distribution an unviable business and an unattractive vocation. And this could severely backfire, hurting the regulator’s growth agenda and ‘Insurance for All’ by 2047,”
thehindubusinessline.com
Bejon Kumar Misra
Consumer policy expert and General Insurance Council executive committee member
“For too long, high upfront commissions have created incentives to sell what is most rewarding to the distributor rather than what is most suitable for the consumer. Staggering commissions over the life of a policy can better align the interests of the insurer, intermediary and policyholder and discourage mis-selling and unnecessary policy churn,”
thehindubusinessline.com
Sources

Related news

IRDAI Proposes Sweeping Overhaul of Insurance Distribution Rules
IRDAI Proposes Hard Commission Caps and Lower Insurer Expenses
Irdai Commission Overhaul Pressures PB Fintech and Turtlemint Business Models
Insurance Shares Tumble as Regulator Proposes Commission Cuts
IRDAI Proposes Insurance Distribution Reset With Commission Caps
IRDAI Proposes Insurance Reforms Targeting Commissions, Bundling and Dark Patterns
Insurance Stocks Slide After IRDAI Proposes Distribution Reforms

Why Couples May Need Separate Term Insurance Plans

Turtlemint Shares Rise as Jefferies Sees Strong Upside
