

3 days ago
Credit Card EMI or Personal Loan: Which Costs Less?

Credit-card EMI lets you pay for a purchase in smaller monthly instalments.
It can be convenient for items like phones, laptops and appliances.
Personal loans may be better for bigger expenses or purchases that cannot go on a card.
A no-cost EMI is not always completely free because fees and GST may apply.
A personal loan with smaller monthly payments can still cost more overall if it lasts longer.
Paying only the minimum on a credit-card bill can cause interest to keep growing.
A large card purchase can also use much of your credit limit.
The best choice is the one with the lowest total cost that you can comfortably repay.

Credit-card EMI can simplify smaller purchases such as gadgets, furniture and home appliances.
Personal loans may suit larger expenses or purchases that cannot be charged to a credit card.
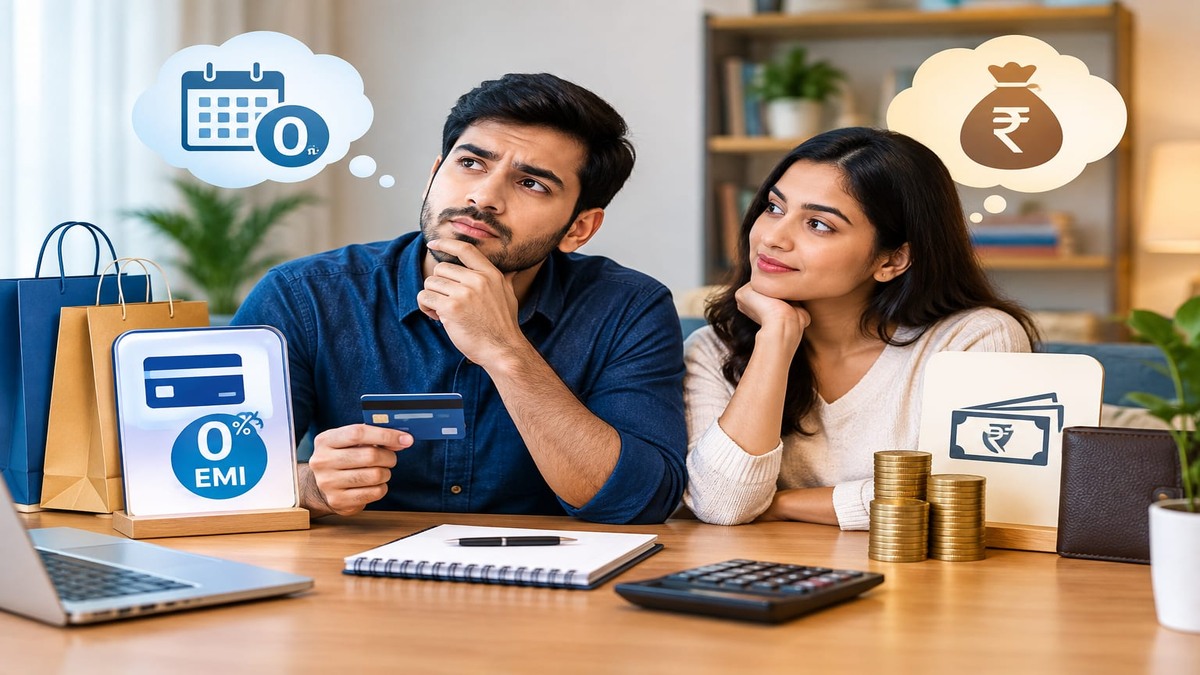
“No-cost EMI” offers may still include processing fees, GST or lost instant-payment discounts.
A longer personal-loan tenure can reduce monthly instalments but increase total interest paid.
Borrowers should compare total repayment costs, credit utilisation, fees, tenure and prepayment charges.
- Who
- Consumers deciding how to finance large purchases.
- What
- A comparison of credit-card EMIs and personal loans, including their costs, fees and repayment effects.
- Where
- Through a credit-card issuer or personal-loan lender.
- When
- Before financing a big-ticket purchase.
- Why
- To choose an affordable borrowing option and avoid paying unnecessary interest or fees.
Credit-card EMI
Personal loan
Convenience and eligibility
Credit-card EMI
A credit-card EMI can be arranged without a separate loan application and may work well for eligible smaller purchases.
Personal loan
A personal loan can provide financing for larger expenses or purchases that cannot be charged to a credit card.
Potential borrowing cost
Credit-card EMI
A genuine low-cost or no-cost EMI may be useful when fees and other charges are limited, but the terms must be checked carefully.
Personal loan
Personal-loan rates vary with income, credit history and existing debt, while processing fees and longer tenures can increase the final cost.
Credit and repayment risk
Credit-card EMI
A large card purchase can raise credit utilisation, and unpaid balances may attract continuing interest.
Personal loan
A personal loan avoids using the card limit, but borrowers must be able to manage the scheduled repayments and total borrowing cost.
Key facts
- Credit-card EMI use
- Often used for televisions, laptops, smartphones, furniture and home appliances.
- Personal-loan suitability
- Generally better suited for substantial borrowing needs or expenses that cannot be charged to a credit card.
- No-cost EMI caution
- Processing fees and GST may apply, and some offers may replace an instant full-payment discount.
- Tenure effect
- A longer repayment period can lower the monthly instalment but increase total interest.
- Credit utilisation
- A large card purchase can consume much of the available limit and potentially affect the borrower’s credit profile.
- Unpaid balances
- Paying only the minimum amount due does not clear the credit-card balance, allowing interest to continue building.
- Comparison factors
- Review total repayment, interest rate, processing fee, GST, tenure, and prepayment or foreclosure charges.
Sources
Related news

Credit Card EMIs May Ease Payments, Not Lower Costs

When Personal Loans Make Sense for Credit Card Debt
How Smart Borrowing Can Build Wealth Without Straining Budgets
Zero-cost EMI May Cost More Than Paying Upfront

Consumer Durable Loans Carry Costs Beyond Advertised EMIs
