

3 days ago
Zero-cost EMI May Cost More Than Paying Upfront
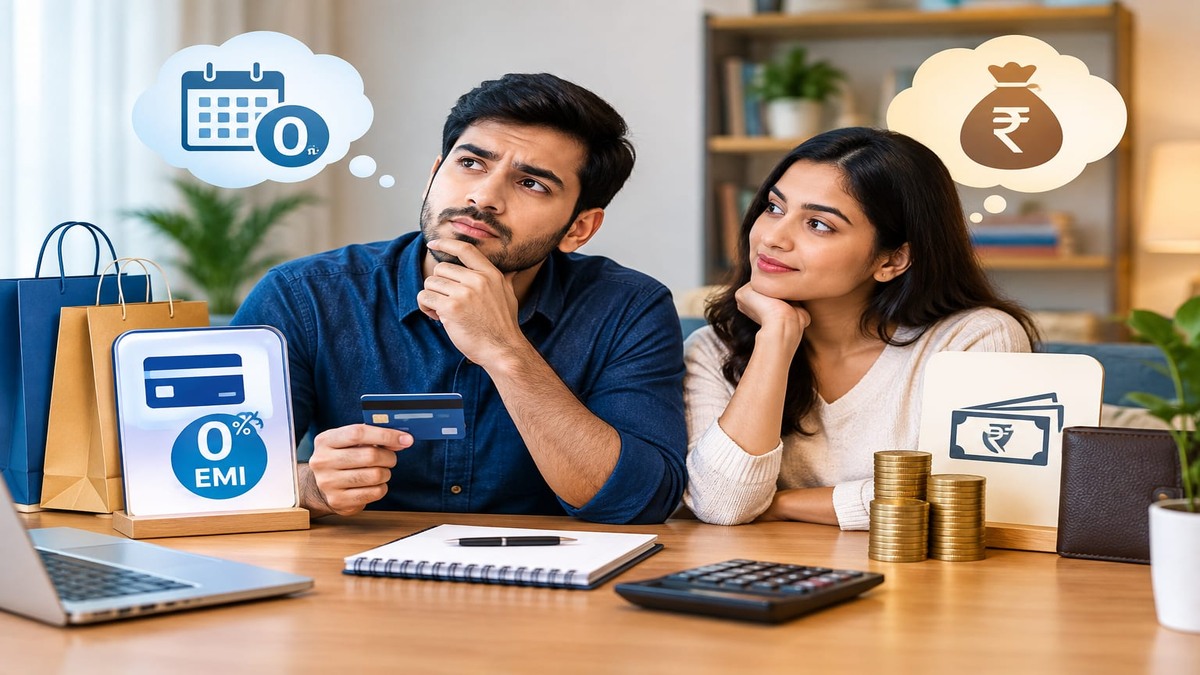
A zero-cost EMI lets you pay for an expensive item in smaller monthly amounts.
The bank may still charge interest, but the seller gives a discount to cancel out that interest.
However, you may still have to pay processing fees and taxes.
You could also lose an instant discount or cashback offered for paying upfront.
In one example, a Rs.
50,000 item costs Rs.
50,659 through EMI.
The same item costs Rs.
47,500 upfront after a Rs.
2,500 discount.
EMI can still be useful if it costs nearly the same and helps you keep cash available.
Before choosing, compare the complete cost rather than only the monthly payment.

Zero-cost EMI offsets interest through a merchant discount, but other charges may still apply.
Processing fees, GST, foreclosure fees and late-payment charges can increase the total cost.
A Rs. 50,000 six-month EMI example costs Rs. 50,659 after fees and taxes.
The same purchase costs Rs. 47,500 upfront when a Rs. 2,500 discount applies.
Consumers should compare total net costs, discounts, cashback and repayment flexibility before choosing.
- Who
- Credit card users considering zero-cost or no-cost EMI purchases.
- What
- The article explains how to compare the total cost of zero-cost EMI with paying upfront.
- Where
- For purchases made through credit cards at eligible merchants or on eligible products.
- When
- At checkout and before converting a credit card purchase into an EMI.
- Why
- To determine whether fees, taxes, lost discounts or cashback make EMI more expensive than upfront payment.
Pay Upfront
Choose Zero-cost EMI
Overall cost
Pay Upfront
Paying upfront may be cheaper when it qualifies for a larger instant discount or cashback and avoids EMI fees and taxes.
Choose Zero-cost EMI
A zero-cost EMI can have a similar effective cost when its interest is offset and additional charges are absent or marginal.
Cash-flow management
Pay Upfront
Paying in full avoids monthly repayment obligations, credit-limit usage and possible late or foreclosure charges.
Choose Zero-cost EMI
EMI spreads a large purchase across monthly payments and can preserve cash for other expenses or an emergency fund.
What consumers should compare
Pay Upfront
The relevant figure is the discounted upfront price, not merely the listed product price.
Choose Zero-cost EMI
Consumers should calculate total EMI payments plus fees and taxes, then subtract applicable discounts or cashback.
Key facts
- Example product price
- Rs. 50,000
- Example EMI tenure
- Six months
- Illustrative interest rate
- 15.99% per annum
- Interest in example
- Rs. 2,358, offset by a merchant discount
- Processing fee
- Rs. 199
- Total EMI cost
- Rs. 50,659 after listed fees and taxes
- Upfront cost with discount
- Rs. 47,500 after a Rs. 2,500 instant discount
Quotes
Santosh Agarwal
CEO of Paisabazaar, quoted on the relative costs of credit-card EMI options
“A zero-cost EMI can be preferable instead of a regular credit card EMI because the interest component is effectively offset by the merchant through a discount.”
 financialexpress.com
Sources
Related news

Credit Card EMIs May Ease Payments, Not Lower Costs

Consumer Durable Loans Carry Costs Beyond Advertised EMIs

Credit Card EMI or Personal Loan: Which Costs Less?
Proposed UPI Fees Above Rs 2,000 Versus Credit Cards
Keep UPI Free by Funding It From Savings

UPI payments stay free for customers under revised rules

PSU Car Loan Rates Start at 7.35% in September 2026
Indian Stocks React to Corporate Actions, Orders and Governance Developments
Tata Governance Dispute Puts Group Stocks In Focus
PB Fintech Growth Hinges on Regulatory Clarity and Execution
