

1 hr ago
IRDAI Insurance Commission Overhaul Sparks Debate Over Costs
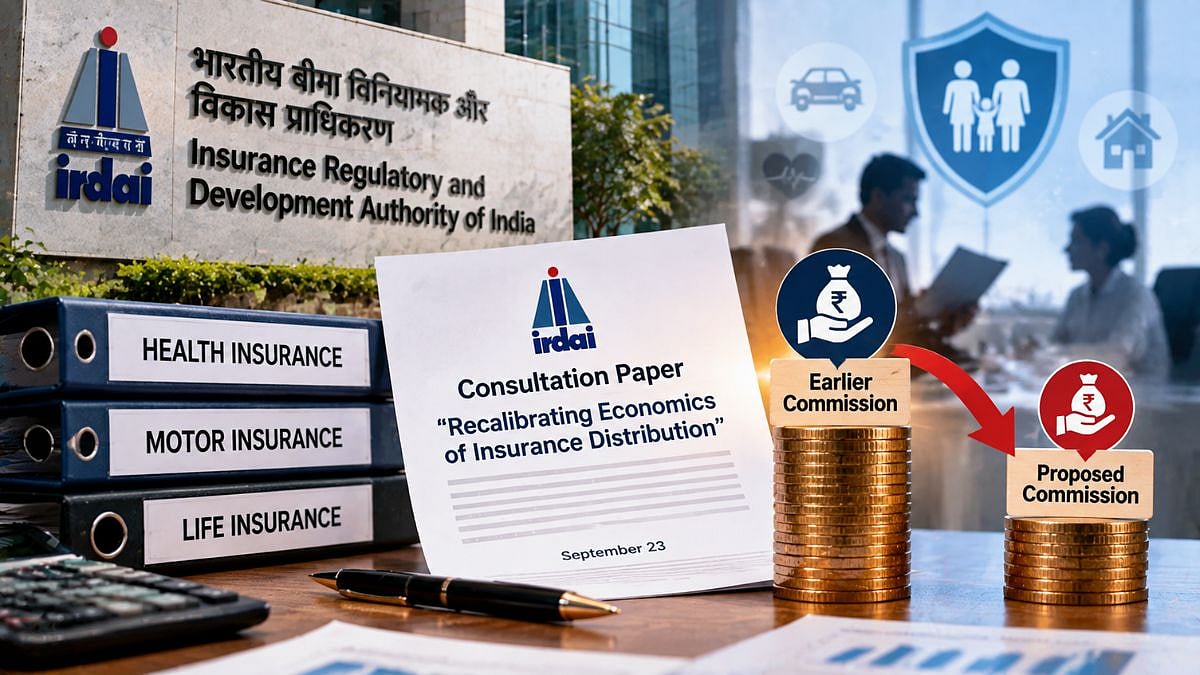
India's insurance regulator wants to change how much insurers can pay companies and agents that sell policies.
The proposal comes after commissions grew much faster than premiums in some insurance markets.
For example, motor commissions rose much more quickly than motor premiums between FY23 and FY25.
Some banks can receive a large share of premiums for insurance sold with loans.
The draft would reduce several commission limits, including one example involving credit-linked life insurance.
Supporters may see this as a way to reduce excessive distribution costs.
Critics worry that sudden cuts could make companies and agents less willing to sell insurance.
The regulator is accepting feedback before deciding what rules should finally be adopted.

IRDAI's September 23 consultation paper proposes major changes to insurance distribution commissions.
Motor premiums grew 34% while motor commissions rose 259% between FY23 and FY25.
Retail health premiums increased 53%, compared with 118% growth in commissions.
The draft would sharply reduce some payouts, including a proposed cut from Rs 57,000 to Rs 2,000 on a Rs 1 lakh credit-linked life policy.
Feedback is open until October 25, with debate over affordability, distributors' incentives and policyholder interests.
- Who
- The Insurance Regulatory and Development Authority of India, insurers, banks, brokers, agents and policyholders are involved.
- What
- IRDAI has proposed recalibrating insurance-distribution economics, including new commission and expense ceilings.
- Where
- The proposal concerns India's insurance sector.
- When
- The consultation paper was released on September 23, and feedback is open until October 25.
- Why
- IRDAI says the changes address rapidly rising commissions, while the article says the rules should also protect affordability, distribution and policyholders.
Curb Excessive Commissions
Protect Distribution Incentives
Commission levels
Curb Excessive Commissions
Rapid commission growth and payouts approaching half of some premiums justify tighter limits.
Protect Distribution Incentives
A drastic reduction could punish distributors for operating under rules previously permitted by IRDAI.
Equal treatment
Curb Excessive Commissions
A common structure and common norms could prevent excessive rewards for selling identical products.
Protect Distribution Incentives
Different caps for agents and banks or brokers may be intended to protect the agent workforce, but they create unequal treatment for similar work.
Effect on customers
Curb Excessive Commissions
Lower distribution expenses could help prevent policyholders from being short-changed.
Protect Distribution Incentives
Lower insurer payouts do not automatically make insurance cheaper, and abrupt cuts could weaken incentives to sell insurance in a market with penetration below 4% of GDP.
Key facts
- Consultation paper
- “Recalibrating Economics of Insurance Distribution”
- Motor sector trend
- Premiums grew 34% and commissions grew 259% between FY23 and FY25.
- Retail health trend
- Premiums rose 53% while commissions increased 118% between FY23 and FY25.
- Credit-linked example
- A bank commission on a Rs 1 lakh single-premium policy could reach Rs 57,000 under existing arrangements and Rs 2,000 under the draft.
- General insurance ceiling
- The proposed limit would decline from 30% to 25% in two years and 20% in five years.
- Life insurance limits
- The proposed overall limit would fall from 15% to 12.5%; distribution entities would receive 20% in the first year and 3% on renewals for long-term policies.
- Feedback deadline
- October 25
Sources
Related news
IRDAI Proposes Hard Commission Caps and Lower Insurer Expenses

IRDAI Distribution Reforms Could Lower Premiums, Reshape Insurance
IRDAI Proposes Insurance Distribution Overhaul To Curb Mis-Selling
Insurance Commission Caps Must Protect Consumers Without Shrinking Access
IRDAI Proposes Insurance Changes That Could Lower Costs
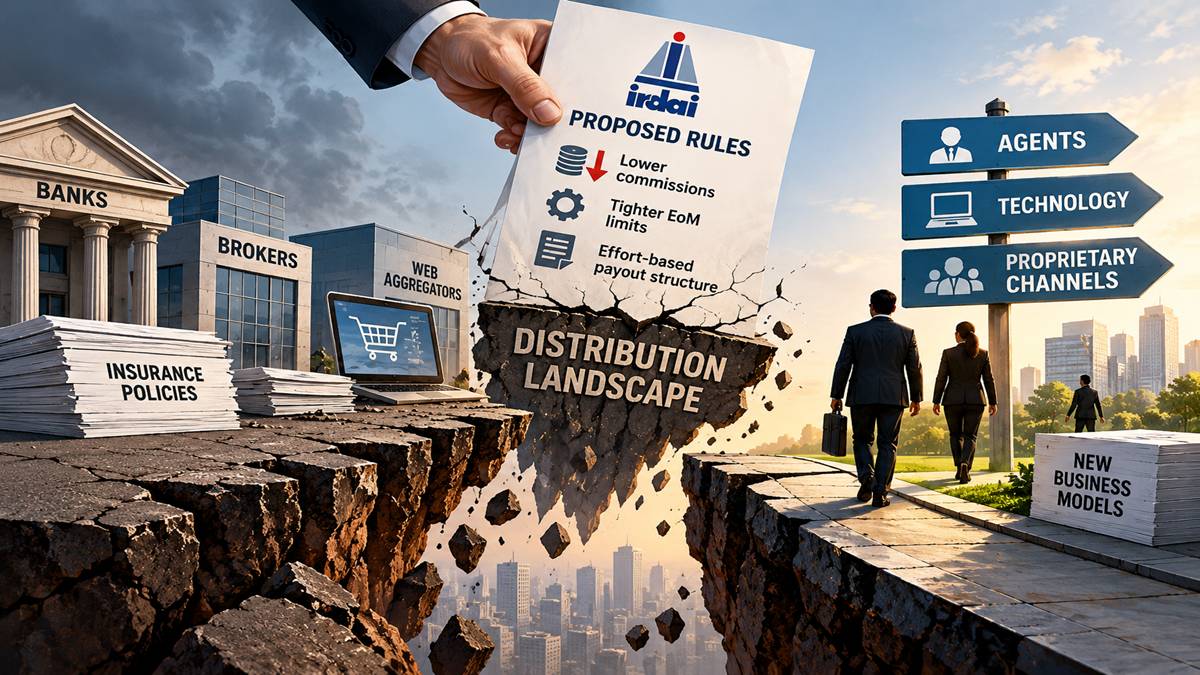
IRDAI Commission Cuts Set to Reset Insurance Distribution Models

Indian Bureaucratic Appointments Feature Alongside Political and Policy Developments
Nationwide Bank Strike Begins Monday Over Five-Day Week Demand
LIC and New India Assurance veterans appointed as IRDAI members
Indian Markets Recover as AI Hotline, LIC Shift Lead Roundup
