

17 hrs ago
IRDAI Distribution Reforms Could Lower Premiums, Reshape Insurance

India’s insurance regulator has proposed new rules for how insurance products are sold.
The proposal is not final because it is still a consultation paper.
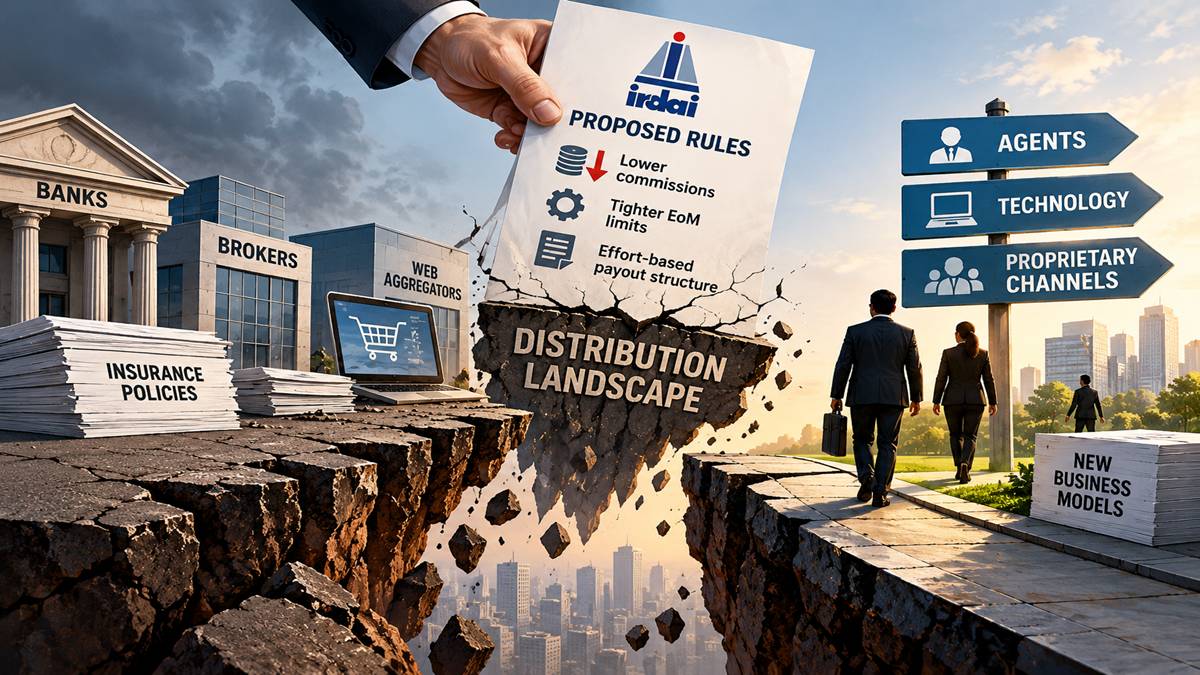
It would limit how much distributors can earn through commissions.
The regulator believes this could make health and motor insurance cheaper.
It could also give people better returns on some life-insurance savings products.
The rules would require more disclosure and could recover payments when customers are mis-sold policies.
Insurance companies may need time to change their business models.
Some industry members support the plan, while another executive says it could slow growth and reduce innovation.

IRDAI has proposed lower expense limits, commission caps, remuneration disclosures and clawbacks for mis-selling.
The reforms aim to reduce motor and health premiums, improve life-insurance returns and strengthen claims service.
First-year health commissions would be capped at 15% for distribution entities and 20% for agents and associates.
Life-insurance commission caps would vary by policy term, while higher limits would be allowed in rural and smaller cities.
Industry representatives expect greater transparency but warn that insurers may face slower growth and less room for innovation.
- Who
- The Insurance Regulatory and Development Authority of India, insurers and insurance distributors are involved; industry views include those of Nisha Sanghavi and Venky Iyer.
- What
- IRDAI has proposed reforms to insurance distribution economics, including commission caps, lower expense limits, remuneration disclosures and clawbacks for mis-selling.
- Where
- The proposals apply to India, with higher commission limits planned for rural areas and towns and cities with populations below 10 lakh.
- When
- The consultation paper was issued late Wednesday; proposed expense-limit reductions would begin in FY27-28 and continue for five years.
- Why
- IRDAI says high distribution expenses are limiting policyholder benefits, insurance penetration and expansion into less-served areas.
Consumer benefits and efficiency
Industry growth and innovation concerns
Premiums and policyholder value
Consumer benefits and efficiency
The regulator and supporters say lower distribution costs could reduce motor and health premiums, increase returns on life-insurance savings products, and improve claims and service standards.
Industry growth and innovation concerns
A life-insurance company’s managing director and chief executive said premiums may fall but warned that insurers could have less money and room to develop new business models or innovate.
Distribution reform
Consumer benefits and efficiency
Supporters, including Venky Iyer, favor greater transparency, cost efficiency and limits on upfront commissions to improve consumer outcomes.
Industry growth and innovation concerns
The industry may need time to realign, and the proposed limits could slow the sector in the short term, according to industry commentary.
Insurance expansion
Consumer benefits and efficiency
IRDAI says lower distribution costs and higher commission limits for rural and smaller cities could help expand insurance penetration beyond tier 1 cities.
Industry growth and innovation concerns
Critics argue that reduced expense limits could constrain business expansion, particularly while insurers adjust to the new structure.
Key facts
- Proposal status
- The reforms are contained in a two-part consultation paper and are not yet final.
- Health commission caps
- Proposed first-year caps are 15% for distribution entities and 20% for agents and associates; renewal caps are 5% and 10%, respectively.
- Long-term life policies
- For policies lasting 10 years or more, proposed first-year commissions are 25% for agents and 20% for distribution entities, with renewal caps of 5% and 3%.
- Expense limits
- By the end of a five-year reduction period, proposed limits would be 12.5% of premium income for life insurers and 20% for general and health insurers.
- Commission levels identified
- IRDAI found average first-year life commissions ranging from 14% to 51%, with maximums reaching 81% in some categories; some health segments had maximum general-insurance commissions of 93%.
- Remuneration growth
- In a representative sample, new business premium rose 28% between FY23 and FY25, while total distributor remuneration increased 125%.
- Potential premium impact
- Promore Fintech director Nisha Sanghavi said premiums could fall 15%-20%, while noting that the proposal remains subject to consultation.
Quotes
Nisha Sanghavi
Director at Promore Fintech
“Premiums could reduce by 15-20 per cent but we need to wait and watch as this is still a consultation paper. They are trying to emulate the mutual fund model to stop upfront commissions.”
 deccanchronicle.com
“I support these reforms given that they propose to bring in greater transparency and cost efficiencies in distribution leading to better consumer outcomes.”
deccanchronicle.com
Insurance official familiar with the regulator’s thinking
An insurance official familiar with IRDAI’s proposed reforms
“Why should customers bear 30 per cent acquisition cost on mandatory motor third party insurance? These gaps are constraining higher insurance penetration and expansion of insurance to far flung areas”
deccanchronicle.com
Sources
Related news
IRDAI Proposes Hard Commission Caps and Lower Insurer Expenses

IRDAI Proposes Sweeping Overhaul of Insurance Distribution Rules
IRDAI Proposes Insurance Changes That Could Lower Costs
IRDAI Proposes Insurance Distribution Overhaul To Curb Mis-Selling
IRDAI Commission Cuts Set to Reset Insurance Distribution Models
Insurers May Lower Premiums as Regulator Proposes Commission Cuts

Why Couples May Need Separate Term Insurance Plans
How Families Should Choose Between Single and Split Life Cover

Telangana Panel Orders Tata AIA to Pay ₹1 Crore Claim

Shiprocket raises ₹727 crore from anchor investors ahead of IPO
