2 days ago
NPS Swasthya Sets Health Cover, Withdrawal and Insurance Rules
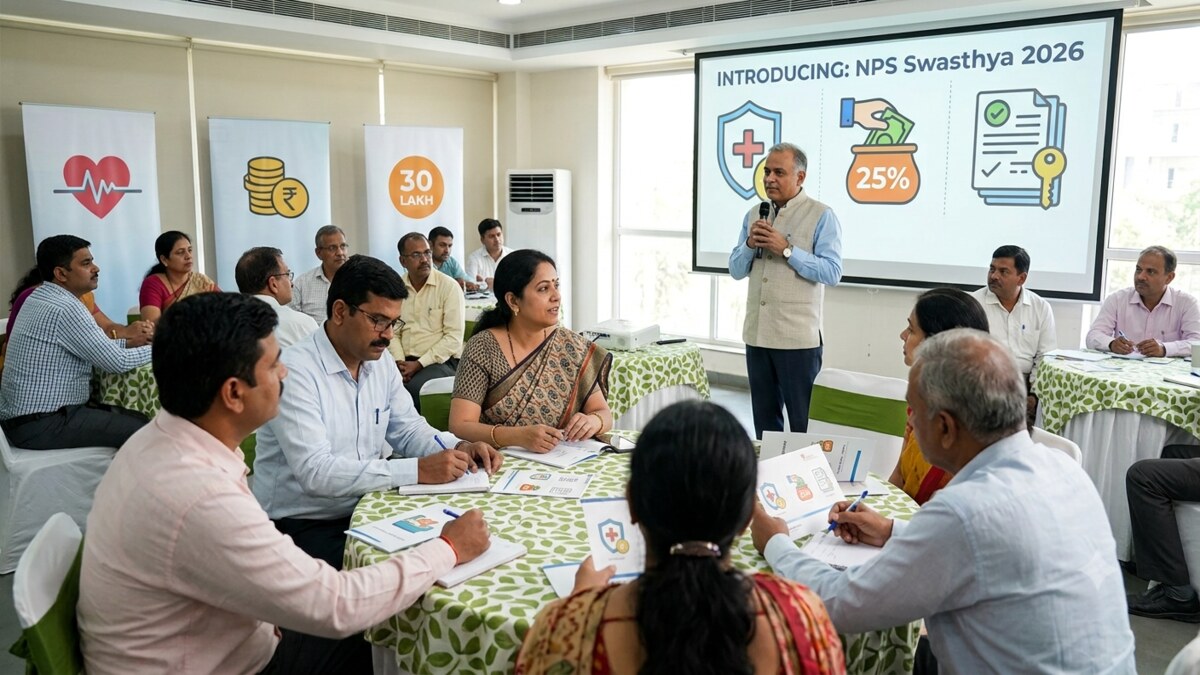
NPS Swasthya is a retirement account linked to health insurance.
A person must have both the account and a separate super top-up insurance policy.
The policy can cover the subscriber, spouse and up to two dependent children.
Depending on the deductible, the family’s insurance cover can be as high as Rs 30 lakh.
Money in the account can be used for eligible medical bills.
Each partial withdrawal can use up to 25% of the subscriber’s contributions, and there is no limit on the number of withdrawals.
The money is paid directly to a hospital or other eligible healthcare provider rather than to the subscriber.
If insurance cannot be renewed or the account is closed, the remaining money is moved into an All Citizen Model NPS account under the stated rules.

PFRDA’s 2026 guidelines require subscribers to hold both an NPS Swasthya account and a separate super top-up health insurance policy.
The standard family-floater policy covers the subscriber, spouse and up to two dependent children, with sums insured ranging from Rs 1 lakh to Rs 30 lakh.
Subscribers may make unlimited partial withdrawals for eligible healthcare expenses, but each withdrawal is limited to 25% of their NPS Swasthya contributions.
The initial contribution must cover the first-year insurance premium, Rs 200 in annual maintenance charges plus taxes, and at least Rs 1,000 for investment.
Coverage includes specified hospitalisation and healthcare services, with waiting periods, deductibles, exclusions and claim-service standards applying under the insurance policy.
- Who
- Eligible National Pension System subscribers, pension funds, insurers and Health Benefit Administrators are covered by the guidelines.
- What
- The Pension Fund Regulatory and Development Authority issued operational rules for NPS Swasthya, combining a retirement corpus with access to a standard super top-up health insurance policy.
- Where
- The rules apply within the National Pension System framework and to PFRDA-registered intermediaries.
- When
- The guidelines were issued in a circular dated September 18, 2026, and are identified as NPS Swasthya 2026 rules.
- Why
- The scheme is intended to help subscribers build a retirement healthcare corpus while providing insurance and healthcare-related withdrawal options.
Key facts
- Maximum family-floater sum insured
- Rs 30 lakh
- Partial withdrawal limit
- 25% of the subscriber’s contributions to the NPS Swasthya account
- Partial withdrawal frequency
- No limit on the total number of partial withdrawals
- Covered family members
- Subscriber, spouse and up to two dependent children; parents are excluded
- Subscriber entry age
- 18 to 70 years
- Insurance renewal age
- May continue until age 85, subject to the policy, premium and applicable law
- Minimum subsequent contribution
- Rs 10
Quotes
PFRDA
Pension Fund Regulatory and Development Authority, the regulator issuing the guidelines
“All concerned intermediaries shall take necessary steps to ensure compliance with the provisions of the Guidelines attached to this Circular and shall establish appropriate systems, processes and controls for effective implementation of NPS Swasthya.”
 financialexpress.com
“NPS Swasthya seeks to enable subscribers to build a dedicated corpus for meeting retirement expenses while facilitating access to health insurance and healthcare-related services through the ecosystem established under NPS architecture.”
financialexpress.com
Sources
Related news

NPS Swasthya Sets 25% Medical Withdrawal and Insurance Rules

PFRDA Plans October Launch of Health-Focused NPS Swasthya Product
PFRDA Nears NPS Swasthya Launch, Explores Guaranteed Returns

NPS Vatsalya Rules Govern Withdrawals, Exits, and Account Conversion
NPS PoP Charges Standardized From October 1, 2026
PFRDA Orders NPS Scheme Names, Risk Categories Within 30 Days

NPS Vatsalya: How Parents Can File Online Grievances
How Indian PPF and NPS Tier II Change After Relocation
PFRDA Plans UPI Pension Accounts, Guaranteed Returns and Health Cover