

3 days ago
Advance Tax Deadline: When Salaried Indians Must Pay More
Advance tax means paying some income tax during the year instead of waiting until the end.
Salaried workers often have their employer pay this tax through monthly TDS deductions.
They may still owe more if they earn money from rent, bank interest, investments, dividends or freelance work.
A separate payment is generally needed when the remaining estimated tax liability is at least Rs 10,000.
By September 15, eligible taxpayers must have paid 45% of their expected yearly advance tax in total.
This includes the 15% that was due in June.
For example, someone expecting to owe Rs 1 lakh and having paid Rs 15,000 in June would pay another Rs 30,000 by September 15.
A qualifying resident senior citizen without business or professional income does not have to pay advance tax.

September 15 is the deadline for the second advance-tax instalment for tax year 2026-27.
Taxpayers liable for advance tax must have paid a cumulative 45% of their estimated annual liability by September 15.
Salaried employees generally need not pay separately when employer-deducted TDS covers their full tax liability.
Additional income from rent, interest, dividends, shares, mutual funds or freelance work can create an advance-tax shortfall.
Advance-tax instalments are cumulatively 15% by June 15, 45% by September 15, 75% by December 15 and 100% by March 15.
- Who
- Salaried individuals and other taxpayers whose estimated net tax liability is at least Rs 10,000 may be required to pay advance tax; qualifying resident senior citizens are exempt.
- What
- The second instalment of advance tax for tax year 2026-27 is due, with cumulative payments reaching 45% of estimated annual liability.
- Where
- India.
- When
- The instalment deadline is September 15, 2026; the article was updated and first published that day.
- Why
- Additional taxable income or insufficient employer TDS can leave a tax shortfall requiring advance-tax payment.
Key facts
- September instalment
- Cumulative 45% of estimated annual advance tax liability by September 15.
- Minimum liability
- Advance tax generally applies when estimated net tax liability is Rs 10,000 or more after accounting for TDS and TCS.
- June instalment
- 15% cumulatively due on or before June 15.
- December instalment
- 75% cumulatively due on or before December 15.
- March instalment
- 100% of estimated advance tax due on or before March 15.
- Common additional income
- Rent, bank interest, bond interest, dividends, capital gains and freelance or consulting income.
- Senior-citizen exemption
- A resident senior citizen aged 60 or above without business or professional income is exempt.
Quotes
CA Suresh Surana
Tax expert quoted on advance-tax obligations for salaried individuals
“A salaried individual is required to pay advance tax under Section 404 of the Income-tax Act, 2025, if the estimated tax payable for the tax year is Rs 10,000 or more.”
 news18.com
“A salaried individual can disclose income from other sources and the related tax details to the employer so that the employer can deduct additional tax from salary.”
news18.com
Sources
Related news
September 15 Advance Tax Deadline: Who Pays and How Much

Missed June Advance Tax Instalment? September 15 Deadline Explained

Salary TDS May Not Cover FD Income, Risking September Penalties

How Salaried Employees Should Report Side-Business Income in Tax Returns
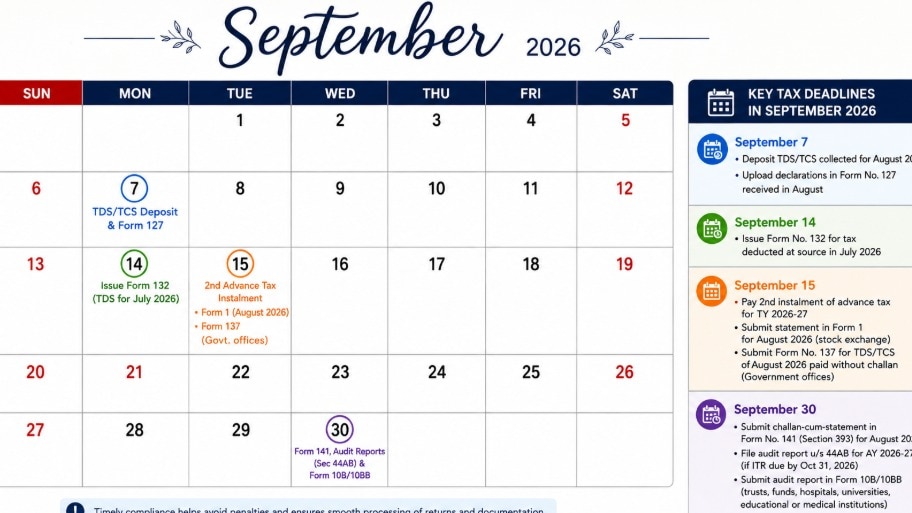
September 2026 Income Tax Deadlines Cover Payments, Audits

Upcoming 2026 Income Tax Return Deadlines for Taxpayers
Railway Claims Inter-Department Hockey Title After Beating Police
ITR Filing Deadline Today: Who Must File Now
HIL Teams Aim for Strong Start

Cricketers and Their Superfans: Exploring Hidden Passions
