

1 hr ago
Choice Says IRCTC Warrants Premium as Businesses Expand
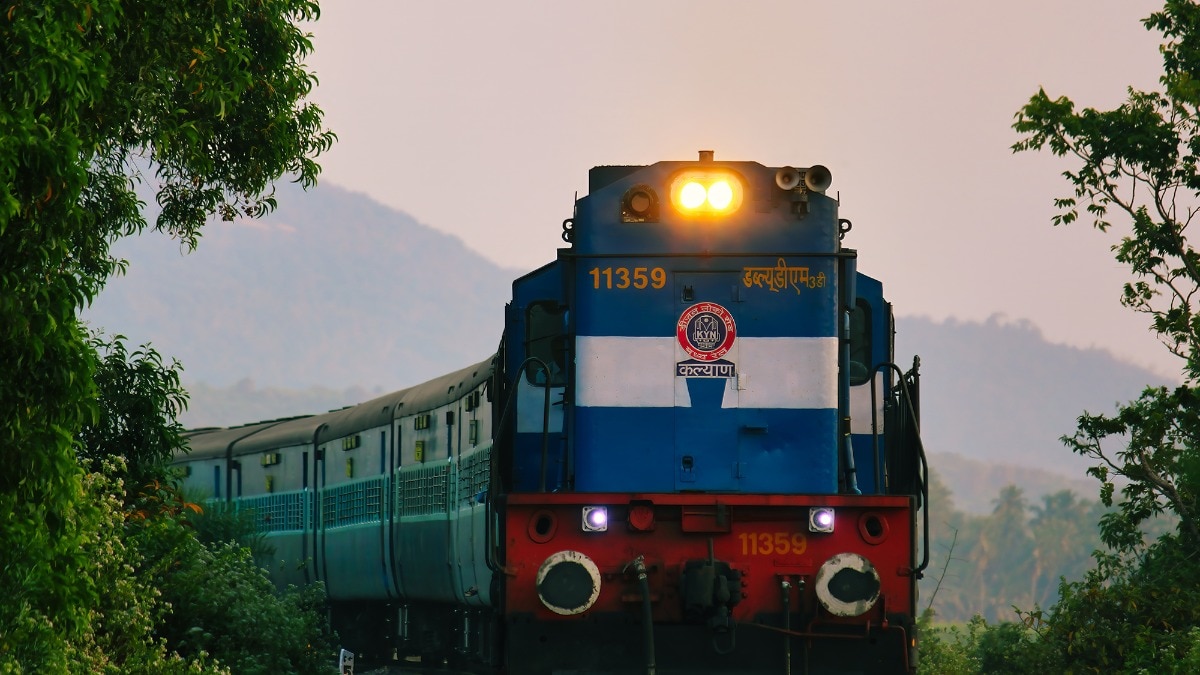
Choice is a brokerage that believes IRCTC deserves a higher valuation than some other railway businesses.
IRCTC sells train tickets online and has reached a high level of digital use.
However, Choice says online ticketing may not grow as quickly in the near term.
The company is therefore developing other businesses, such as catering, tourism and packaged drinking water.
More passengers are choosing air-conditioned trains, including Vande Bharat trains.
This may allow IRCTC to earn more from convenience fees.
IRCTC also plans one travel platform for trains, flights, hotels, buses and tourism.
Choice expects profits to face some pressure before improving as newer businesses become larger and catering operations improve.

Choice said Indian Railway Catering and Tourism Corporation warrants a premium because it is expanding beyond online ticketing into a broader mobility platform.
E-ticketing reached 89% of reserved bookings in FY26, although Choice expects near-term saturation in Internet Ticketing.
A 51% AC passenger mix and growing Vande Bharat adoption could support higher convenience-fee realisation.
A proposed unified platform would combine rail, air, hotel, bus and tourism services to increase customer engagement and retention.
Bharat Gaurav contributes 40% of Tourism revenue, while Rail Neer production is planned to rise from 15.5 lakh to 20 lakh bottles daily.
- Who
- Choice and the Indian Railway Catering and Tourism Corporation (IRCTC).
- What
- Choice said IRCTC warrants a premium as it expands beyond online railway ticketing into mobility, catering, tourism and Rail Neer.
- Where
- The businesses described operate across India’s railway and domestic travel network.
- When
- The assessment refers to FY26 and projections through FY27E; no publication date is provided.
- Why
- Choice cited IRCTC’s exclusive online railway-ticketing position, large user base, rising AC passenger mix, Vande Bharat adoption and expansion into other travel-related businesses.
Key facts
- Brokerage view
- Choice said IRCTC warrants a premium.
- E-ticketing penetration
- 89% of reserved bookings in FY26.
- AC passenger mix
- 51%.
- FY27E EBITDA margin
- Expected to decline to 29% before recovering as new initiatives scale and catering economics improve.
- Tourism revenue contributor
- Bharat Gaurav accounts for 40% of Tourism segment revenue.
- Rail Neer production
- Current daily actual supply is around 15.5 lakh bottles, with a long-term goal of 20 lakh bottles per day.
Quotes
Choice
Domestic brokerage providing analysis of IRCTC’s business outlook
“With near-term saturation in Internet Ticketing, the company is increasingly focusing on scaling other high-growth businesses. Rising AC mix (51 per cent) and adoption of Vande Bharat trains should support higher convenience fee realisation. We expect Ebitda margin to decline to 29 per cent in FY27E due to an evolving business mix, before recovering as new initiatives scale and Catering unit economics improve.”
 businesstoday.in
“The company benefits from a large user base, providing multiple opportunities for monetisation through convenience fees, payments, advertising and cross-selling of travel services. The ongoing premiumisation of passenger travel, driven by a rising AC mix (51 per cent) and increasing adoption of Vande Bharat trains, further enhances revenue potential through higher convenience fee realisation.”
businesstoday.in
Sources
Related news

IRCTC Records First 20-Lakh Ticket Booking Day
Titagarh Rail Systems Sees Growth From Passenger Rail Push
Railway UPI Tickets Above Rs 2,000 Face Rs 5 MDR
Five Indian Monopoly Stocks With Strong Moats and Pricing Power
Pine Labs Shares Rise as MOFSL Forecasts Further Upside

ITC Stock Faces Cigarette Pressure, But Brokerage Sees 68% Upside
Jai Hind College Symposium Examines AI’s Future in Tourism

Dividend Record Date Alert: 62 Companies Set September 22
178 Indian Stocks Set to Turn Ex-Dividend This Week
