1 hr ago
Motilal Oswal backs Tata Steel, JSW Steel as prices rise
Steel prices in India have risen sharply, even though demand is often weaker during this season.
Hot-rolled coil prices reached their highest level in four years in September.
Rebar prices also increased between June and September.
More steel was used than produced in India between April and August 2026, which helped keep supplies tight.
Motilal Oswal believes this could support steel companies’ earnings.
It especially likes JSW Steel and Tata Steel because they may have cost advantages and access to raw materials.
However, coking coal has become more expensive, which can reduce profits.
The companies will need to keep raising prices or control costs to protect their margins.

Motilal Oswal has rated JSW Steel and Tata Steel as its top metal-sector picks with a ‘Buy’ recommendation.
Domestic hot-rolled coil prices reached a four-year high in September, while rebar prices rose to Rs 56,800 per tonne.
India’s finished steel consumption grew 7.2% year-on-year to 70.3 million tonnes between April and August 2026.
The brokerage expects steel pricing to remain supportive as the sector shifts toward pricing- and cost-led earnings growth.
Higher coking coal costs could pressure margins, making price pass-through and cost advantages important for steel mills.
- Who
- Motilal Oswal, JSW Steel and Tata Steel are the main companies discussed.
- What
- Motilal Oswal has given JSW Steel and Tata Steel a ‘Buy’ rating as steel prices rise.
- Where
- The main market discussed is India, with global and Chinese steel production also considered.
- When
- The pricing trend was assessed during Q2FY27, with production and consumption data covering April to August 2026.
- Why
- Motilal Oswal expects stronger steel realisations and potentially improved post-monsoon demand, while noting that higher raw-material costs could pressure margins.
Bullish Brokerage View
Margin and Demand Risks
Steel pricing
Bullish Brokerage View
Motilal Oswal expects domestic steel prices to remain constructive and believes the sector is moving toward pricing- and cost-led earnings growth.
Margin and Demand Risks
Higher raw-material costs could offset the benefit of stronger steel prices unless mills successfully pass those costs on to customers.
Company outlook
Bullish Brokerage View
JSW Steel and Tata Steel are favored because of stronger cost positions, captive raw-material access and exposure to downstream or value-added products.
Margin and Demand Risks
The earnings benefit depends on continued price strength and an expected improvement in post-monsoon demand, so weaker demand could limit gains.
Key facts
- Brokerage view
- Motilal Oswal rates JSW Steel and Tata Steel ‘Buy’.
- HRC prices
- Domestic hot-rolled coil prices reached a four-year high in September.
- Rebar prices
- Rebar prices rose from Rs 48,850 per tonne in June to Rs 56,800 per tonne in September.
- Indian production
- India produced about 67.4 million tonnes of finished steel from April to August 2026, up 3.7% year-on-year.
- Indian consumption
- Finished steel consumption reached about 70.3 million tonnes during the same period, up 7.2% year-on-year.
- Raw-material impact
- Every $10-per-tonne increase in coking coal prices may add about $7-8 per tonne to input costs.
- Global production
- Global crude steel production fell 0.6% year-on-year during January-July, while China’s production declined 3.1%.
Quotes

Motilal Oswal
Brokerage house providing the steel-sector research report
“margin sustainability will depend on mills’ ability to pass through further price increases as the impact of cost inflation will be evident steadily in the coming quarters.”
 financialexpress.com
“we remain constructive on domestic steel pricing as we believe the domestic steel cycle is transitioning from volume-led recovery to pricing- and cost-led earnings growth.”
financialexpress.com
Sources
Related news
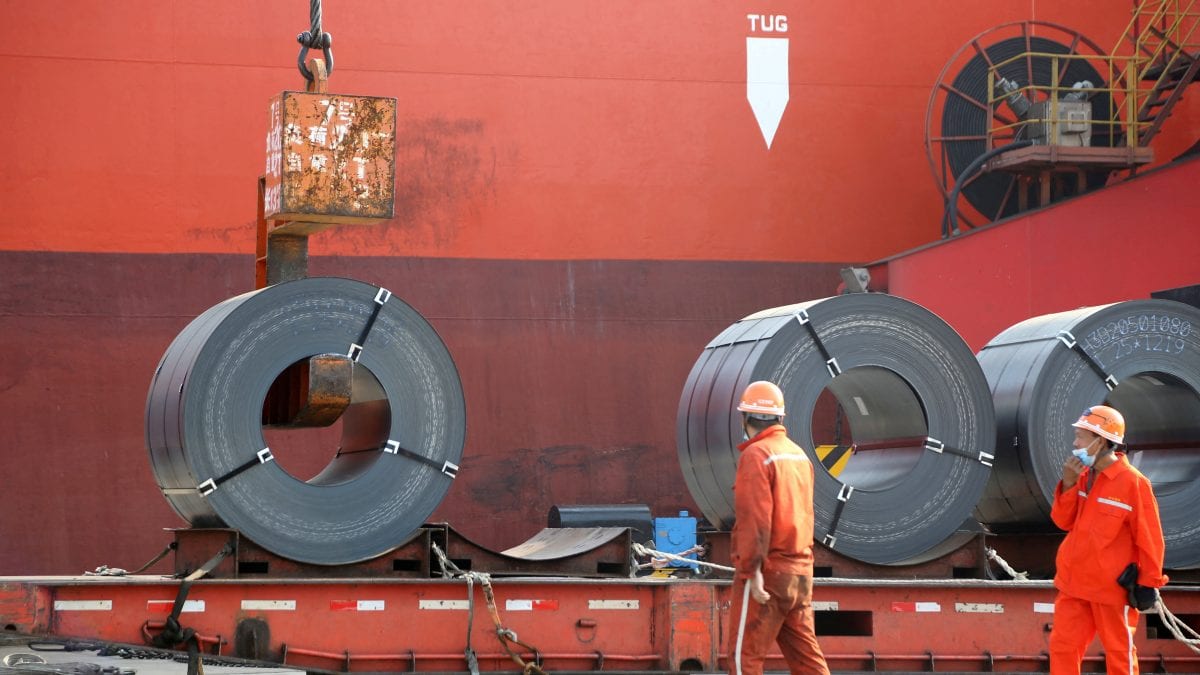
Indian Steel Prices Poised Higher as Coal Costs Rise

Metal Prices Recover as Rising Input Costs Threaten Sustainability
SAIL Profit Surges, But Investors Still Price It Below Rivals
Rising Crude and Metal Prices Threaten Corporate Margins Despite Resilience
Expert Outlines Conditional Outlook For Five Indian Stocks
Brokerages Flag Ten Indian Stocks for Potential Returns
Brokerages See Upside in HDFC Bank, Coforge, GMR Airports

Motilal Oswal’s Taparia Recommends Three Stocks to Buy
India Ratings Upgrades Motilal Oswal Financial Services Rating

LCC Projects IPO Set for NSE, BSE Listing Tomorrow