3 hrs ago
ICICI Securities Sees 27% Upside in Chalet Hotels

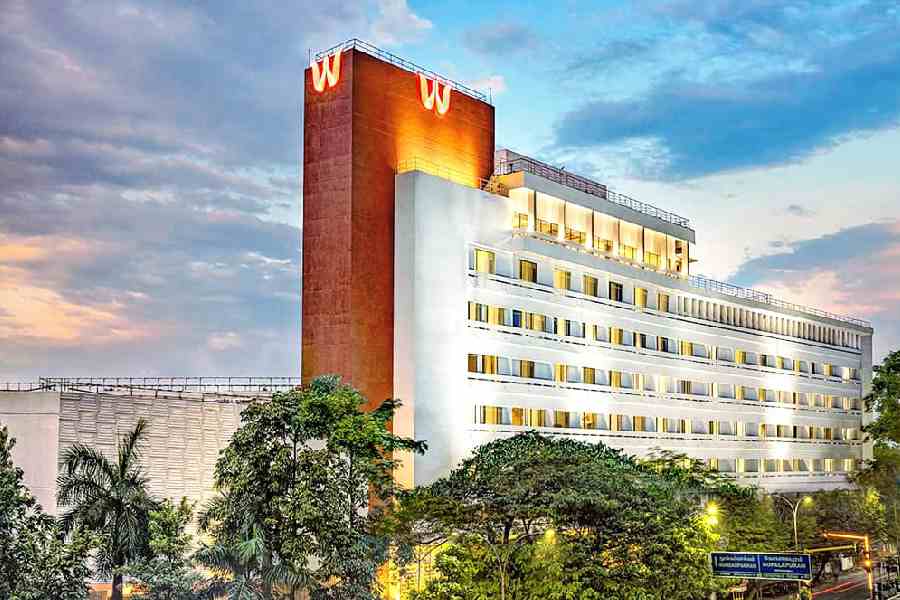
Chalet Hotels owns and operates hotels in India.
Its shares rose 1.20% to ₹883 on the reported trading day.
ICICI Securities thinks the shares could reach ₹1,095.
That would be about 27% higher than the reported closing price.
The brokerage expects the company’s hotel business to grow strongly through FY29.
Chalet is also adding more hotel rooms and developing its own Athiva lifestyle brand.
Its operational hotel portfolio is expected to exceed 5,000 rooms by March 2030.
However, weaker hotel demand or slower office leasing could hurt the company.
The dates in the report appear inconsistent because it mentions both September 2025 and March 2026 market milestones.

Chalet Hotels shares closed 1.20% higher at ₹883 on September 23.
ICICI Securities maintained a ‘Buy’ rating and a ₹1,095 target price.
The brokerage expects hotel revenue to grow at a 15% CAGR through FY29E.
Chalet Hotels plans to add 1,655 keys, taking its portfolio above 5,000 by March 2030.
Analysts cited slower hotel demand and office leasing as key risks to the outlook.
- Who
- Chalet Hotels Limited and ICICI Securities.
- What
- ICICI Securities maintained a Buy rating and a ₹1,095 target price for Chalet Hotels shares.
- Where
- The company is headquartered in Mumbai, and the shares are traded on the BSE.
- When
- The shares closed on Wednesday, September 23; the report also cites milestones dated September 24, 2025, and March 30, 2026.
- Why
- ICICI Securities expects hotel revenue, hotel EBITDA, and the company’s room portfolio to expand.
Bullish outlook
Risks and caution
Share-price potential
Bullish outlook
ICICI Securities retained its Buy rating and ₹1,095 target, implying nearly 27% upside from the reported ₹883 close.
Risks and caution
The target is an analyst estimate, and the report identifies slower hotel demand and office leasing as risks.
Business expansion
Bullish outlook
Chalet Hotels is expanding its operational portfolio, launching the Athiva premium lifestyle brand, and using hotel franchise and asset-ownership models.
Risks and caution
The success of new brownfield and greenfield projects, brand expansion, and the annuity portfolio depends on execution and stabilization.
Financial growth
Bullish outlook
ICICI Securities forecasts hotel revenue to rise at a 15% CAGR and hotel EBITDA at a 16% CAGR through FY29E.
Risks and caution
The forecasts are estimates, and the article does not guarantee that the projected revenue or EBITDA will be achieved.
Key facts
- Reported closing price
- ₹883 per share
- Brokerage target price
- ₹1,095 per share
- Implied upside
- Nearly 27%
- Brokerage rating
- Buy
- Expected hotel revenue growth
- 15% CAGR during FY26–29E
- Expected FY29E hotel revenue
- ₹26.9 billion
- Planned room additions
- 1,655 keys, taking the portfolio to more than 5,000 keys by March 2030
- Key risks
- Slower hotel demand and office leasing
Quotes
ICICI Securities
Brokerage that published the research report on Chalet Hotels.
“We estimate CHALET’s hotel revenue growing at a 15% CAGR over FY26–29E (assuming 6% LTL ARR growth) to INR 26.9bn in FY29E, while its hotel EBITDA grows at a 16% CAGR to INR 11.8bn over the same period. Further, its annuity asset portfolio could generate over INR 4bn of annual EBITDA upon full stabilisation in FY29.”
 livemint.com
“We retain BUY with an unchanged SoTP-based TP of INR 1,095, based on 22x Mar’28E hotel EV/EBITDA. Brownfield/greenfield additions could provide a further fillip to earnings. Key risks: Slowdown in hotel demand/office leasing.”
livemint.com
Sources
Related news
Analysts recommend five hotel stocks with up to 49% upside
ICICI Securities Sees 28% Upside in Indian Hotels Shares
Seven Indian Hotel Stocks Prepare for Festive Season Demand

PL Capital Recommends Fortis Healthcare Shares, Sets ₹1,050 Target
Jefferies Sees Higher Upside Potential in ITC Hotels
ITC Hotels Plans Premium Expansion Across India and Abroad
Novotel Kolkata Hosts Five-Day Awadhi Culinary Festival in September
BMW i5 LWB Pairs Electric Luxury With Spicy Duck Flavours
SMARTIES India 2026 Shortlist Highlights Marketing Innovation and Impact
AAGHOSHAM Brings Kerala’s Heritage, Cuisine and Arts to Mumbai