1 hr ago
JPMorgan Sees India Capex, Manufacturing Driving New Growth Cycle
JPMorgan studied India’s economy and identified areas it believes could grow strongly.
It expects companies to spend more money on factories, power systems, technology and infrastructure.
Banks could benefit if lending stays strong and loan quality remains healthy.
Larsen & Toubro is highlighted for projects in energy, data centres, electronics and defence.
Dixon Technologies is expanding electronics production and exports.
Hospitals and premium consumer businesses are also expected to benefit from demand.
JPMorgan prefers many mid-sized and smaller companies, but it is less positive about information technology.
The firm says global interest rates, tariffs, currency movements and geopolitical events could affect these expectations.

JPMorgan identifies financials, private capital expenditure and manufacturing as the main themes in India’s emerging growth cycle.
The firm expects private capex to recover across power, renewables, semiconductors, electric vehicles, metals, mining and real estate.
ICICI Bank, Larsen & Toubro, Dixon Technologies and several other companies receive ‘Overweight’ ratings among JPMorgan’s preferred picks.
JPMorgan favors mid- and small-cap stocks, citing stronger recent profit growth and fund flows, while remaining underweight on information technology.
Higher global bond yields, a stronger US dollar, tariffs, inflation, liquidity and geopolitical developments remain key risks to India’s outlook.
- Who
- JPMorgan Chase & Co., Indian companies and their management teams discussed in the firm’s India conference.
- What
- JPMorgan outlined its preferred Indian investment themes and stocks, emphasizing financials, private capex, manufacturing and selected consumer and healthcare businesses.
- Where
- India, with implications for exports and overseas markets including the United States and Europe.
- When
- The views were presented at JPMorgan’s 11th India Conference and refer to the outlook through the company and fiscal-year timelines cited in the report.
- Why
- JPMorgan expects private investment, power demand, manufacturing, credit growth and premium consumption to support India’s next growth cycle.
Growth Case
Risk Case
Private investment
Growth Case
JPMorgan expects private capital expenditure to recover across power, renewables, semiconductors, electric vehicles, metals, mining and real estate.
Risk Case
The recovery depends on sustained demand and actual execution of planned projects, while global rates, tariffs and geopolitical developments could delay spending.
Equity selection
Growth Case
JPMorgan prefers quality mid- and small-cap companies, citing stronger recent profit growth and stronger fund flows than large caps.
Risk Case
Mid- and small-cap stocks carry richer valuations, and the firm says investors should focus on earnings momentum rather than value.
Information technology
Growth Case
India’s broader manufacturing, infrastructure and domestic-demand opportunities could support growth outside technology services.
Risk Case
JPMorgan remains underweight on information technology because of uncertain US and European demand, tariff-related delays, soft hiring, pricing pressure from artificial intelligence and high valuations relative to growth.
Key facts
- Main themes
- Financials, private capital expenditure and manufacturing
- Preferred sectors
- Financials, industrials, healthcare, materials and consumer discretionary
- Underweight sector
- Information technology
- Private capex outlook
- Spending is expected to recover after nearly a decade below trend
- Power demand
- Expected to rise from about 271 gigawatts to 459 gigawatts by 2035-36
- Transmission opportunity
- JPMorgan estimates an Rs 8 trillion opportunity as grid constraints increase
- Market preference
- Mid- and small-cap stocks are preferred over large caps
- Foreign ownership
- Foreign ownership of Indian equities is estimated at about 15.8%, a roughly 15-year low
Quotes

Dixon Technologies management
Management of the Indian electronics manufacturing services company Dixon Technologies.
“Expect strong bottom-up trends and continued positive earnings revisions into the print, with macro the key swing factor. We believe large private banks offer an attractive entry point on NII inflection and at inexpensive valuations”
 financialexpress.com
“ROCEs won’t be compromised. Dixon has been operating at 30%+ ROCEs for a long time and is conscious of not diluting that. It ensures that ROCEs don’t go below 30% whenever it plans any new investment”
financialexpress.com
Sources
Related news
Jefferies highlights stock picks across 20 sectors as capex accelerates
Bank of America Names 22 Indian Stocks With Upside
JPMorgan Picks Power Equipment Stocks as India’s Grid Spending Rises
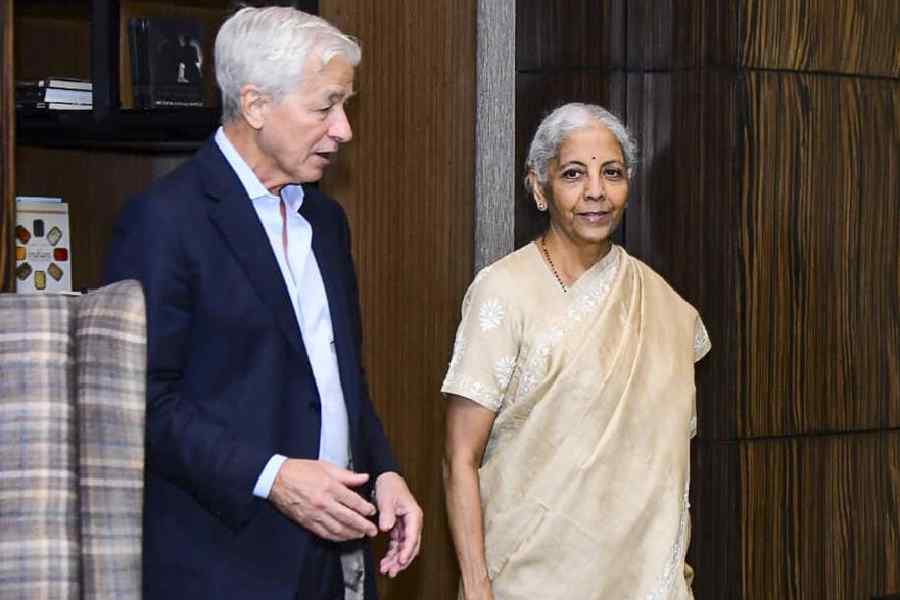
Jamie Dimon Meets Sitharaman at JPMorgan India Conference
Macquarie Names 12 Indian Stocks for Earnings and Returns

Jefferies Sees 31%-50% Upside in Three Indian Stocks
History Favors October Stock Market Comeback; Stocks to Watch
Indian Stocks Slide as Dr Reddy’s, Dixon Buck Trend
Dixon Technologies May Reach 38-40 Million Smartphones by FY27
Dixon Technologies Shares Slip as Brokerages Reassess Growth Prospects