

1 hr ago
Page Industries’ Premium Valuation Faces Slower Growth and Rising Competition
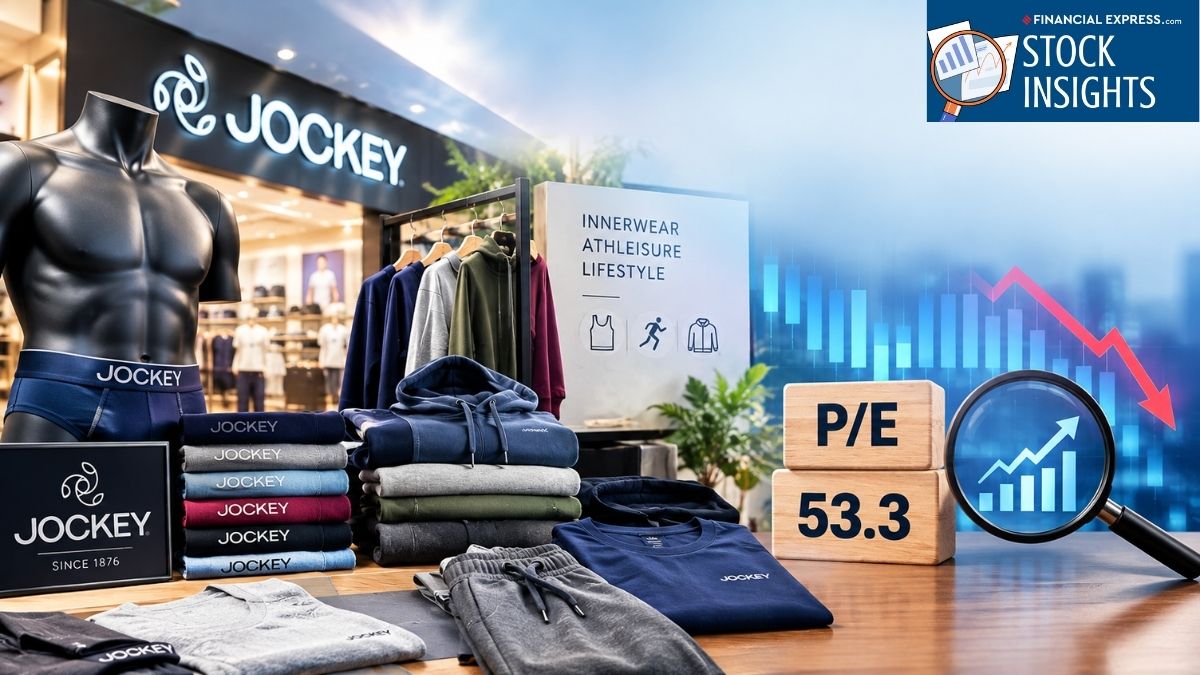
Page Industries sells Jockey clothing and innerwear in India.
The company has a well-known brand and many stores.
It has also added sportswear such as hoodies, T-shirts, pants, and shorts.
However, online brands are offering large discounts, and international companies are entering the market.
The prices of some materials used to make its products have also risen.
These pressures have slowed the company’s sales growth.
The business still earns strong returns on the money invested in it.
Investors are now watching whether future growth can justify the company’s high share price.

Page Industries’ three-year compounded sales growth has slowed to 4%, while net profit growth was 11%.
The company maintained a strong return on equity of 47% over three years, supported by its brand and distribution network.
Higher yarn and cotton costs, D2C discounting, and international brands have increased competitive pressure.
The stock fell 12.7% over the past year, compared with an 8.9% decline in the Sensex.
Page Industries trades at a P/E of 53.3, far above Rupa & Company’s 14.3, making future growth important for valuation support.
- Who
- Page Industries, which sells Jockey innerwear and other apparel, along with competitors including online D2C brands, international brands, and Rupa & Company.
- What
- The company’s slower growth and falling share price are prompting questions about whether its premium valuation is justified.
- Where
- India’s innerwear and athleisure market.
- When
- The stock reached its reported high on October 7, 2022, and a 52-week low on March 16, 2026; the article discusses its outlook for 2026.
- Why
- Rising raw-material costs, aggressive online discounting, and increasing competition have pressured sales and profit growth.
Growth and Brand Case
Valuation and Competition Concerns
Brand strength
Growth and Brand Case
Page Industries benefits from the established Jockey brand, a pan-India distribution network, online initiatives, and strong returns on equity.
Valuation and Competition Concerns
Brand strength may not be enough if online D2C and international competitors continue taking market share.
Product expansion
Growth and Brand Case
Its move into jackets, hoodies, sweatshirts, T-shirts, pants, and shorts could create additional sales over the coming quarters.
Valuation and Competition Concerns
Competition is already intensive in these expanded categories, both online and in physical store chains.
Share valuation
Growth and Brand Case
Future sales and profit improvements could support the current premium if the expanded product range performs as expected.
Valuation and Competition Concerns
A P/E of 53.3 is substantially higher than Rupa & Company’s 14.3, while recent sales growth has slowed to 4% over three years.
Key facts
- Current share price cited
- Rs 37,338, after closing 0.4% higher on Wednesday
- 52-week low cited
- Rs 29,800 on March 16, 2026
- One-year stock performance
- Down 12.7%, versus an 8.9% decline in the Sensex
- Three-year sales growth
- 4% compounded
- Three-year profit growth
- 11% compounded
- Three-year return on equity
- 47%
- Exclusive brand stores
- More than 1,615, alongside more than 893 large-format stores
- Price-to-earnings ratio
- Page Industries: 53.3; Rupa & Company: 14.3
Sources
Related news
Vallabh Bhanshali’s Four-Stock Portfolio Hides Value—and Significant Risks

Globe Enterprises shows resilience despite Indian market sell-off
Bhiwandi Textile Units Struggle as Yarn Prices Surge 70%
Tata Consumer, Rallis India Hit Lows Despite Profit Growth

Haier India Ramps Up Investment Amid Strong Double-Digit Growth
