

10 hrs ago
Indian Banks Receive $127 Billion Boost From Foreign Currency Deposits
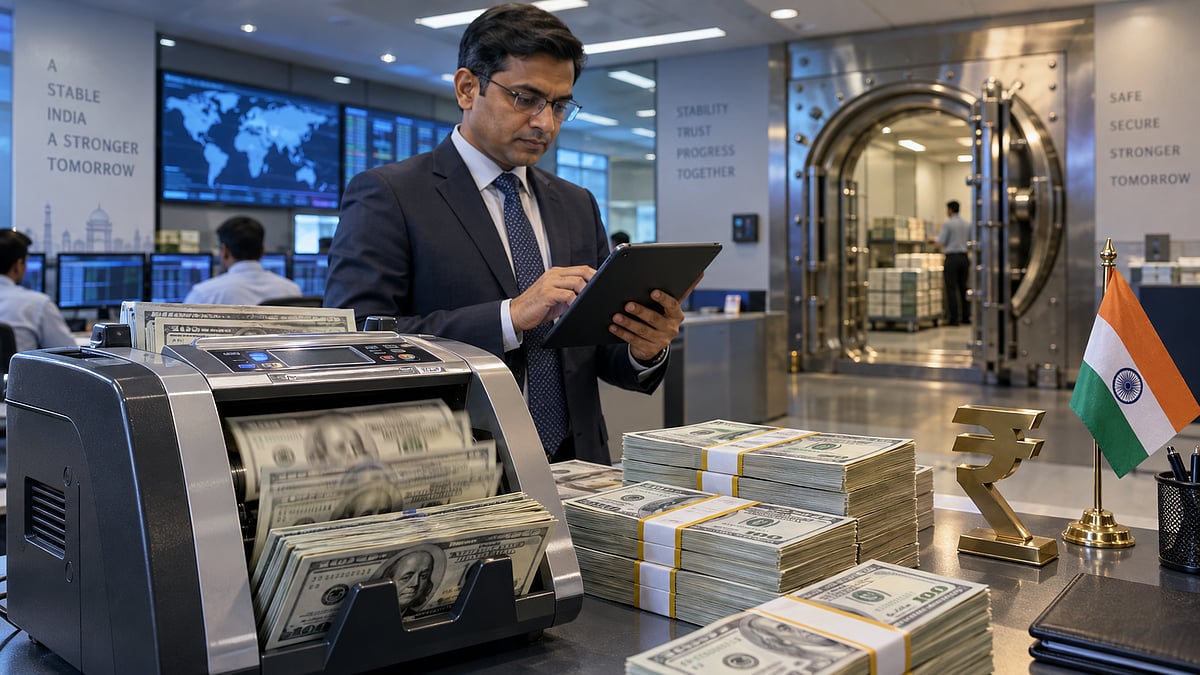
Indian banks received a large amount of money from people living outside India.
The money was placed in special foreign-currency accounts called FCNR(B) deposits.
Banks collected $127 billion between June 8 and August 31, 2026.
The Reserve Bank of India helped make these accounts more attractive by covering certain hedging costs.
The deposits usually last for three to five years.
This gives banks steadier funding for a longer period.
Banks have been lending money faster than they have been collecting deposits.
The new funds may reduce that pressure.
If customers borrow against these deposits, the banks’ balance sheets could grow even more.

Indian banks mobilised a record $127 billion through FCNR(B) deposits between June 8 and August 31, 2026.
The deposits equalled nearly 4.5% of the banking system’s total deposit base as of March 31, 2026.
The Reserve Bank of India absorbed hedging costs on three- to five-year FCNR(B) deposits to encourage inflows.
S&P Global Ratings said the deposits could improve funding stability and ease pressure from credit growth exceeding deposit growth.
Bank balance sheets could expand by $190 billion to $220 billion if 50% to 75% of deposits are leveraged through loans.
- Who
- Indian banks, overseas depositors, the Reserve Bank of India, and S&P Global Ratings.
- What
- Indian banks mobilised $127 billion through Foreign Currency Non-Resident Bank deposits, strengthening their funding and liquidity.
- Where
- The funds were placed with Indian banks through FCNR(B) accounts.
- When
- The deposits were mobilised between June 8 and August 31, 2026; the comparison deposit base was measured on March 31, 2026.
- Why
- The inflows were encouraged by Reserve Bank of India support and are intended to ease funding pressures as credit growth has exceeded deposit growth.
Key facts
- Deposits mobilised
- $127 billion through FCNR(B) accounts
- Mobilisation period
- June 8 to August 31, 2026
- Share of deposit base
- Nearly 4.5% of the banking system’s total deposits as of March 31, 2026
- Deposit maturity
- Three to five years
- Potential balance-sheet increase
- $190 billion to $220 billion
- Leverage assumption
- 50% to 75% of deposits leveraged through loans
- Primary benefit
- Improved liquidity and medium-term funding stability
Sources
Related news

RBI Draws $133 Billion Through Special FCNR(B) Deposit Window
India Draws Record $127 Billion Through Special FCNR Window
Bank of India Raises $2.2 Billion to Support Lending Needs
Private Banks Capture Nearly Half of India’s FCNR(B) Inflows
India’s Forex Reserves Hit Record High on Foreign Inflows
RBI Forex Swap Draws $136.37 Billion, Led by FCNR(B)
ICBC Recovered Watchlisted $500 Million Vedanta Loan in 2017
Moody’s Raises India FY27 Growth Forecast to 7% Amid Resilience

India's BRICS Image Shifts From Weak Link to Global Powerhouse
