2 hrs ago
Ten Checks Before Applying for a Personal Loan App
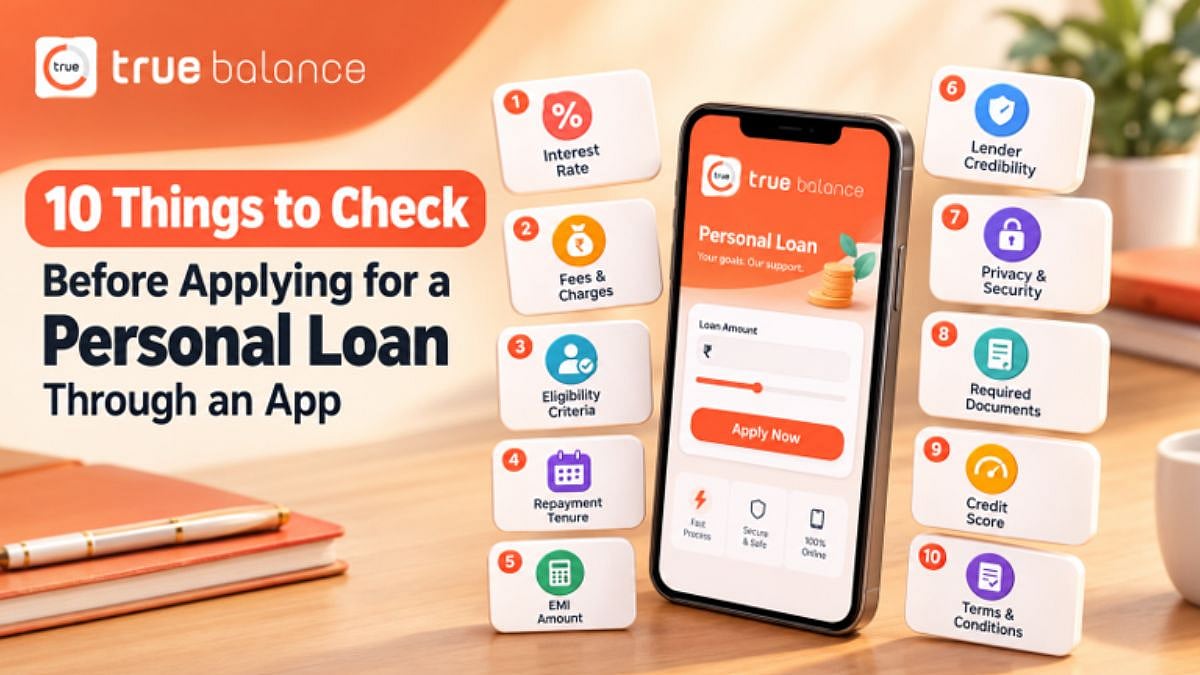
A loan app can make borrowing money feel quick, but it is important to check it carefully first.
Make sure the lender is registered with a financial regulator.
Look at the full cost, including interest and fees.
Check how long you have to repay and what happens if a payment is late.
Be cautious if the app asks to see private contacts or photos.
Read the agreement before you accept the loan.
Applying may affect your credit score, the article says, so check whether you meet the lender’s requirements.
The article also recommends checking customer reviews and support options.
It names True Balance as one option, but borrowers should compare its terms with their needs.

Verify that the app lends through a bank or non-bank lender registered with the relevant regulator.
Compare the annual percentage rate and all fees, not just the advertised interest rate.
Review repayment terms, penalties, data permissions, customer support and the loan agreement before applying.
The article says applications can trigger hard credit inquiries and advises checking eligibility before applying.
The article promotes True Balance, saying it offers loans up to ₹5,00,000 through RBI-registered partners.
- Who
- People considering applying for a personal loan through a mobile app.
- What
- An advice article lists ten checks for assessing personal loan apps and loan terms.
- Where
- Through digital personal loan apps; the article refers to India’s Reserve Bank of India and also mentions the UK Financial Conduct Authority.
- When
- Before downloading an app, applying for a loan or accepting a loan agreement.
- Why
- To help borrowers assess a lender’s reliability, understand costs and repayment obligations, and avoid unnecessary data access.
Key facts
- Checks covered
- Regulatory status, borrowing costs, fees, permissions, repayment terms, credit score effects, customer support, disbursement, reviews and agreement terms.
- APR
- The article says APR reflects the annual interest rate as well as mandatory processing, administrative and documentation costs.
- Repayment tenure example
- The article recommends looking for structured options, ideally ranging from 12 to 48 months.
- Data permissions to question
- Private contact lists, photo galleries, personal media and social media profiles.
- Documents cited
- PAN card, Aadhaar card or valid ID, recent bank statements, and recent salary slips or other proof of income.
- True Balance claims in article
- The article says it offers loans up to ₹5,00,000 through RBI-registered NBFC or bank partners, with interest rates starting at 1% per month.
Sources
Related news
Instant Personal Loans: Requirements, Approval Steps, And Hidden Costs

Personal Loans: Eligibility, Interest Rates, EMIs and Repayment Guide

No-Lock-In Personal Loans Offer Flexibility, But Not Free Foreclosure

First-Time Borrowers: Personal Loan Eligibility, Credit Scores and Repayment

Bajaj Finance Details Personal Loan Amounts, Rates And Tenures
Digital NBFCs Outpace Banks in Volume, Not Loan Value

Jammu EOW Charges Two in Alleged ₹1.22 Crore Investment Scam
HDFC Bank’s 90-Day Reset Ends Leadership Uncertainty

State Borrowing Set to Rise 26% to ₹3.6 Trillion
FCNR(B) Inflows Buy India Time, but Durable Capital Remains Key