

Business · Markets · 2 hrs ago
Meritz Securities raises SK Hynix price target to 3.2 million won

Meritz Securities expects South Korean chipmaker SK Hynix to report operating profit of 80.1 trillion won in the third quarter of 2026, up 32% from the previous quarter.
The forecast is above the 74 trillion won market consensus cited in the report.
The brokerage points to higher shipments and prices for DRAM and NAND memory chips.
It also expects the start of broader HBM4 supply to increase the contribution from high-bandwidth memory, used in advanced computing.
Demand from large technology companies investing in artificial intelligence is another reason the brokerage expects memory demand to remain strong even as prices rise.
Meritz raised its SK Hynix share-price target from 3.1 million to 3.2 million won.
These are forecasts, not reported results; the report also identifies the planned listing of subsidiary Solidigm as a possible longer-term opportunity.

Meritz Securities raised its target price for SK Hynix to 3.2 million won from 3.1 million won.
The brokerage forecast SK Hynix’s third-quarter 2026 operating profit at 80.1 trillion won, above the 74 trillion won market consensus.
It attributed the expected increase to stronger shipments and prices for DRAM and NAND.
Meritz analyst Kim Sun-woo said HBM4 supply was beginning in earnest and could increase its contribution to results.
The report also pointed to stronger supplier bargaining power and the planned listing of SK Hynix subsidiary Solidigm as potential opportunities.
- Who
- Meritz Securities raised its target price for SK Hynix.
- What
- It increased the target to 3.2 million won from 3.1 million won and forecast strong third-quarter results.
- When
- The report was issued on October 12, 2026.
- Where
- Not stated.
- Why
- Meritz cited stronger DRAM and NAND shipments and prices, as well as the expected contribution of HBM4 supply.
This story does not have two clearly opposing sides.
중장기 고객 중심 유연성 극대화 전략에 대한 보상적 되돌림이 발생할 것
또한 높은 판매 비중으로 판가 상승률을 제약했던 HBM 역시 HBM4의 본격 공급이 시작되며 실적 기여가 극대화될 것
모바일 핵심 고객과의 기성 계약도 전반적인 장기공급계약(LTA) 논의로 전환되며 공급자 우위 구조가 강화되고 있다
This story does not have a timeline yet.
- Target price
- 3.2 million won, raised from 3.1 million won
- Forecast quarter
- Third quarter of 2026
- Operating profit forecast
- 80.1 trillion won
- Market consensus
- 74 trillion won
- DRAM shipment and price growth
- 13% and 22%
- NAND shipment and price growth
- 4% and 15%
Sources
Related news

South Korea plans 3 trillion won fund for overseas construction
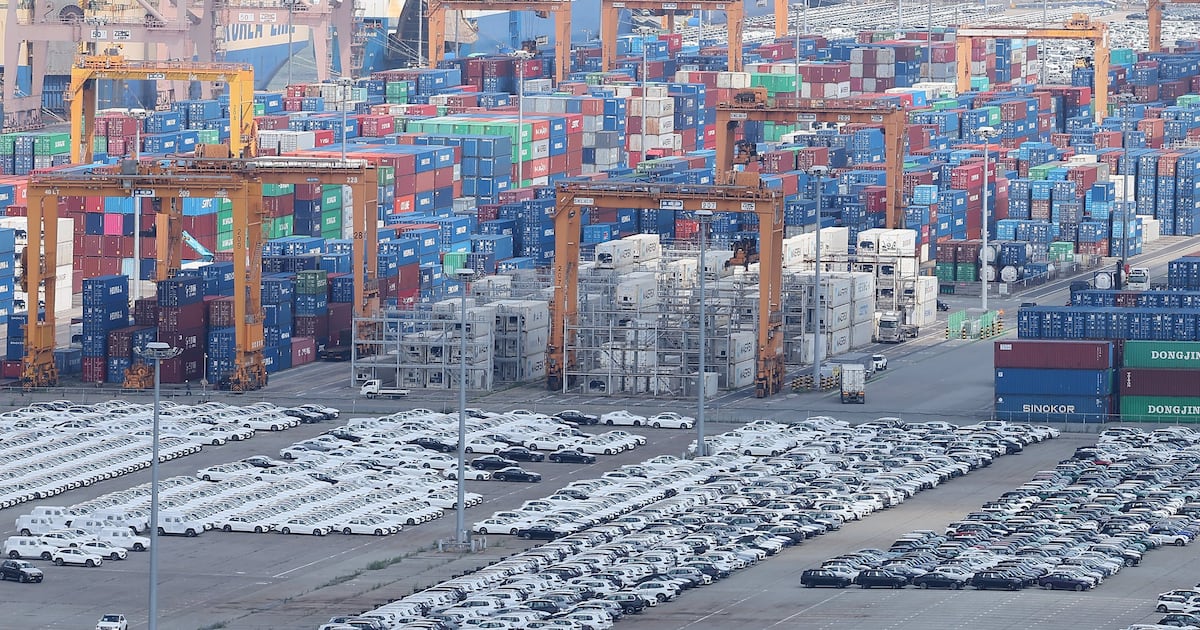
South Korea’s exports hit a record for Oct. 1–10, led by semiconductors

Lotte to present mobility businesses at Japan trade event

Gwangju semiconductor plan lifts shares in regional companies
HiteJinro begins making Kirin Ichiban beer in South Korea

Bank of Korea governor says early rate hikes helped steady markets

LH chief seeks major hiring and financial support to expand housing supply

Won reaches its lowest level against the dollar in about two years
South Korean Won Reaches Two-Year High as Oil Prices Fall

South Korea’s September bond trading rose as individuals bought and foreigners sold

KakaoBank launches mobile banking services for foreign residents in South Korea
