

Archive · 31 Jan 2026
Tata Motors CV Arm Sees Strong Demand
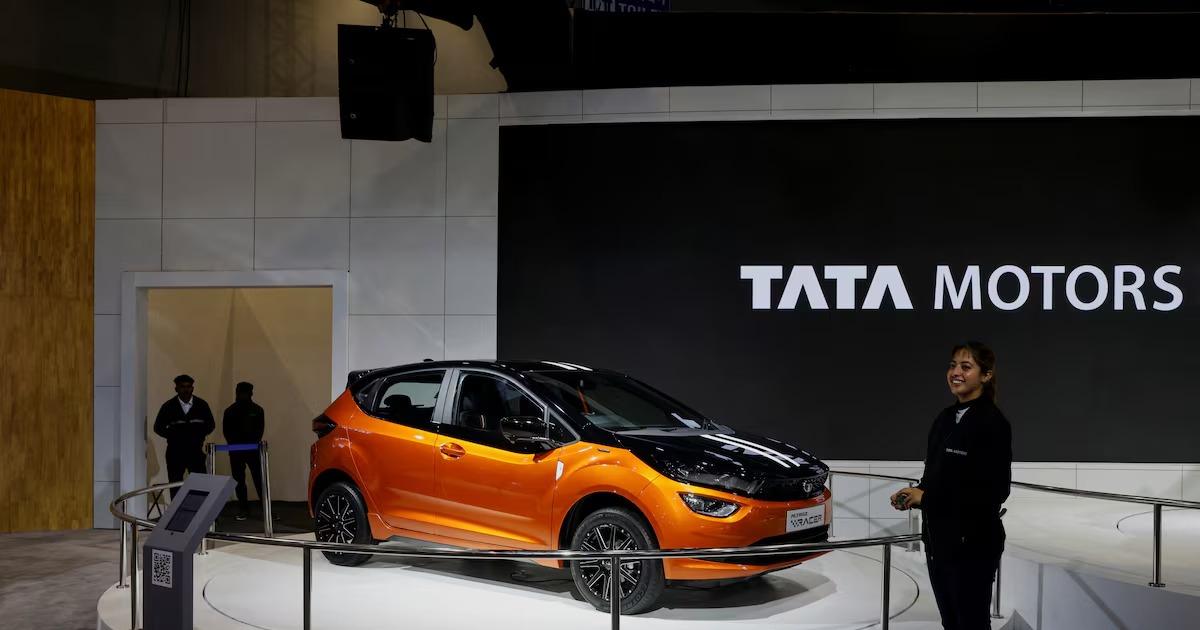
Tata Motors, which makes big trucks and buses, is doing well.
More people are using their vehicles, and the prices for shipping goods have gone up.
This means Tata Motors is making more money.
They expect to keep selling a lot of buses and trucks, especially electric ones, in the next few years.
Some experts think this is great news and that Tata Motors will keep doing well.
Others are a bit worried about costs and competition, but overall, things look good for Tata Motors.

Fleet utilisation levels have climbed to 74-80 per cent, driving demand in India's commercial vehicle market.
Tata Motors' CV segment reported a 16 per cent year-on-year revenue increase to Rs 21,700 crore in Q3.
Ebitda rose 19 per cent to Rs 2,720 crore, with a margin of 12.5 per cent.
Tata Motors plans to deliver around 6,000 buses to various states next year.
Brokerages have mixed views on the sustainability of the upswing, with some seeing a strong upcycle and others expressing caution about margin pressures and market share.
- Who
- Tata Motors' commercial vehicle (CV) arm (TMCV)
- What
- Strong demand drivers and improving industry fundamentals are boosting Tata Motors' CV segment
- When
- The information is based on the December quarter (Q3) performance and future outlook
- Where
- India's commercial vehicle market
- Why
- Due to a pickup in freight rates, rising fleet utilisation, and a long-awaited replacement cycle
- Fleet utilisation levels
- 74-80 per cent
- Ebitda
- Rs 2,720 crore (up 19 per cent)
- Ebitda margin
- 12.5 per cent
- Revenue
- Rs 21,700 crore (up 16 per cent Y-o-Y)
- Average selling prices (ASPs)
- Rs 19.1 lakh (down 2 per cent Q-o-Q)
- Market share in domestic MHCVs
- 47.9 per cent
- Expected bus deliveries for next year
- 6,000 buses