

1 week ago
Kotak Direct Plan Beats Regular by Rs 6.65 Lakh
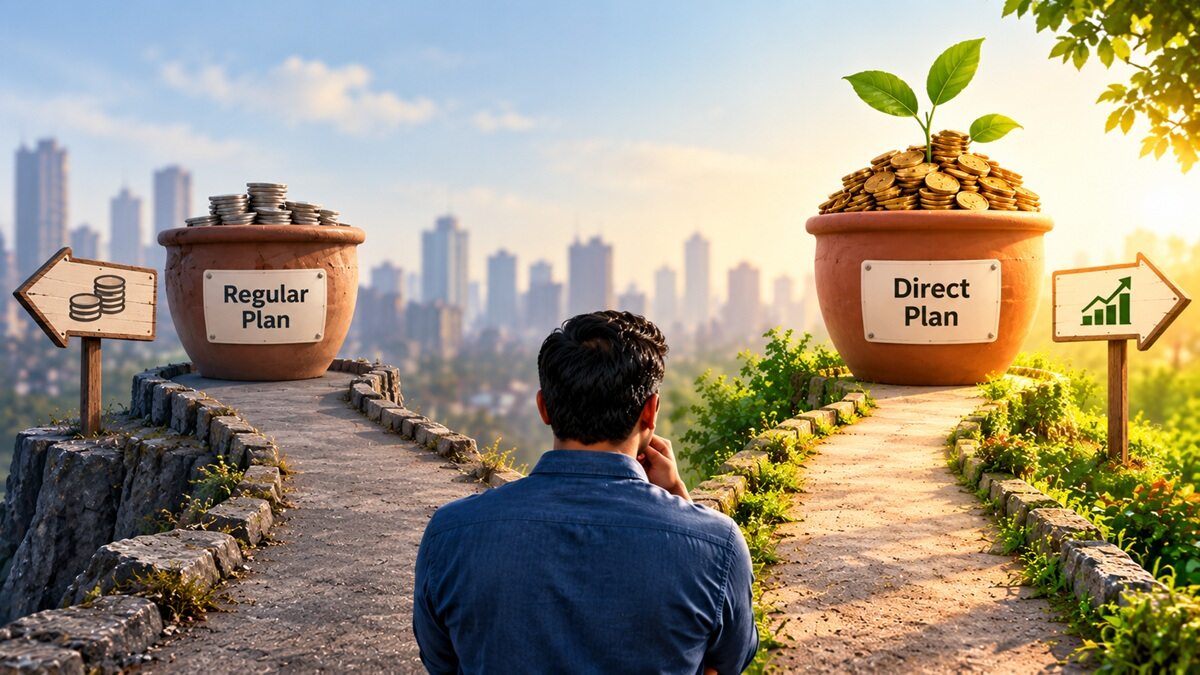
Two people invested the same Rs 10,000 every month in the same Kotak small-cap fund.
They invested for 13 years and each put in Rs 15.60 lakh.
One chose the direct plan, while the other chose the regular plan.
The direct plan had lower costs because it did not include distributor expenses.
After 13 years, the direct-plan investor had Rs 61.09 lakh.
The regular-plan investor had Rs 54.45 lakh.
That created a difference of about Rs 6.65 lakh.
Small yearly costs can make a big difference when they compound over many years.
Both plans still had very high investment risk.

A Rs 10,000 monthly SIP for 13 years grew to Rs 61.09 lakh in Kotak Small Cap Direct and Rs 54.45 lakh in the regular plan.
Both investors contributed the same Rs 15.60 lakh and held exposure to the same underlying portfolio.
The direct plan’s current base expense ratio is 0.50%, compared with 1.41% for the regular plan.
The direct plan recorded a 19.31% annualised SIP return, versus 17.75% for the regular plan.
Both plans carry a Very High risk rating, so the lower-cost direct plan is not a safer investment.
- Who
- Two investors using direct and regular plans of Kotak Small Cap Fund.
- What
- A comparison found that the direct-plan SIP corpus exceeded the regular-plan corpus by Rs 6.65 lakh after 13 years.
- Where
- In the direct and regular plans of Kotak Small Cap Fund.
- When
- Over a 13-year investment period; the direct plan was launched on January 1, 2013.
- Why
- The direct plan had lower expenses, allowing more returns to remain invested and compound.
Direct Plan
Regular Plan
Cost and long-term corpus
Direct Plan
The direct plan has a lower expense ratio and produced the higher historical 13-year SIP corpus in the comparison.
Regular Plan
The regular plan costs more because it includes distribution or intermediary expenses, but it may suit investors who value distributor or adviser assistance.
What the higher return means
Direct Plan
The direct plan’s lower costs provide a structural return advantage, which can compound over time.
Regular Plan
The 0.91 percentage-point current expense gap should not be treated as automatically creating the exact 1.56 percentage-point SIP-return gap, because expenses and market conditions can change.
Investment risk
Direct Plan
Choosing direct can reduce costs but does not reduce the fund’s investment risk.
Regular Plan
The regular plan has the same underlying portfolio and the same Very High risk rating as the direct plan.
Key facts
- Monthly SIP
- Rs 10,000 in each plan
- Investment period
- 13 years
- Total invested
- Rs 15.60 lakh in each plan
- Direct-plan corpus
- Rs 61,09,371
- Regular-plan corpus
- Rs 54,44,525
- Corpus difference
- Rs 6,64,846 in favor of the direct plan
- Expense ratios
- 0.50% direct versus 1.41% regular
- Risk rating
- Very High for both plans
Sources
Related news

Direct or Regular Mutual Funds: Costs, Comparisons, and XIRR Explained

Why Direct and Regular Mutual Funds Earn Different Returns

JioBlackRock Adds Costlier Regular Plans, Expands Fund Offerings

Mutual Fund Expense Ratios Vary Widely Across Equity Categories

Switching Mutual Funds to Direct Plans Carries Hidden Tax Costs
Distributors Dominate Small-Ticket SIPs as Direct Investing Grows

Small-Cap Funds: High Returns Come With Varied Volatility
Kotak Multi-Asset Fund Outperforms Amid Market Divergence
Indian Mutual Funds Show Limited Exposure to Silver

Alpha Shows Mid-Cap Laggards Trail Small-Cap Fund Performance
