

Archive · 26 Aug 2026
MOFSL Sees 21% Upside in Vedanta Aluminium Stock
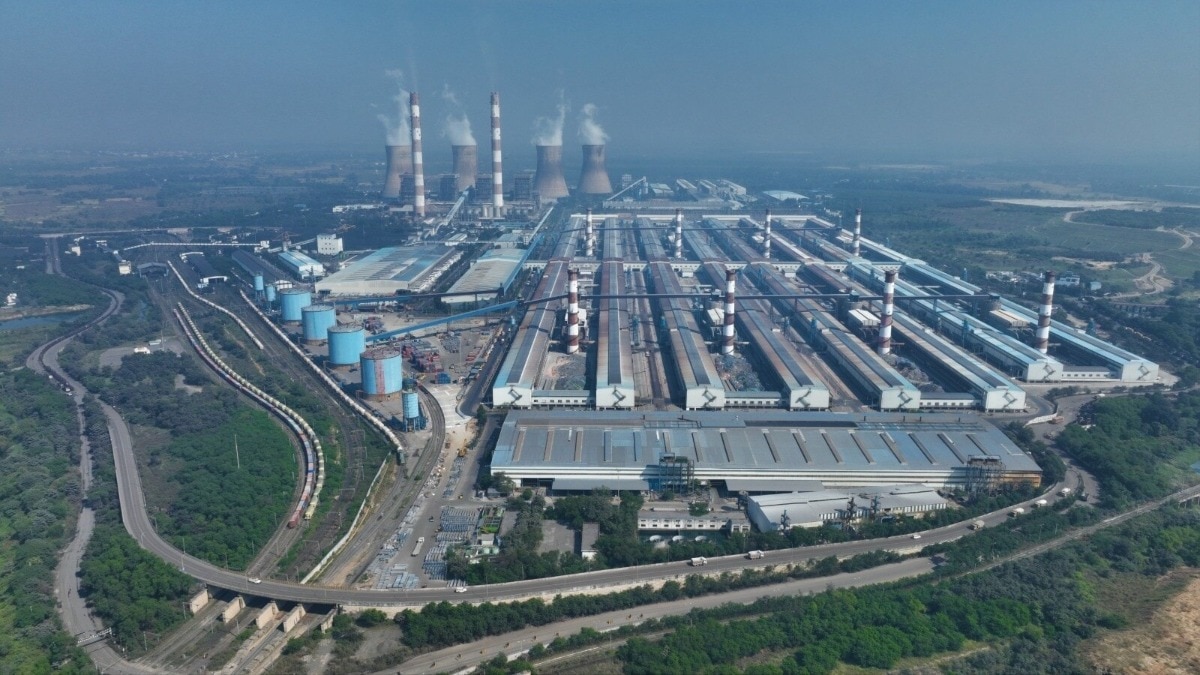
MOFSL believes Vedanta Aluminium Metal’s shares could rise by about 21%.
It gave the stock a Buy rating and a target price of Rs 540.
The company is increasing its aluminum-making capacity at BALCO and Jharsuguda.
This could help production grow through FY28.
Vedanta Aluminium is also trying to control costs by owning more mines and processing facilities.
Its Lanjigarh refinery has become larger, so the company may need to buy less alumina from outside.
Captive coal and power can also make aluminum production cheaper.
MOFSL says these changes could make the company more competitive globally.

MOFSL maintained a Buy rating on Vedanta Aluminium Metal with a Rs 540 target price, implying 21% upside.
The brokerage identified volume growth, integration-led cost reductions and a higher value-added product mix as key growth drivers.
BALCO commissioning and Jharsuguda debottlenecking could lift total smelting capacity to 3 MTPA by FY28-end.
The Lanjigarh refinery expansion to 5 MTPA is expected to improve internal alumina availability and reduce external procurement.
MOFSL expects captive coal, renewable power, operating efficiencies and scale to reduce costs and improve VAML’s global cost-curve position.
- Who
- MOFSL and Vedanta Aluminium Metal (VAML).
- What
- MOFSL maintained a Buy rating and set a Rs 540 target price for VAML, citing expected capacity growth, integration and cost reductions.
- When
- The estimates and targets refer primarily to FY28 and FY28-29; the Sijimali mine is expected to begin operations in 2HFY27.
- Where
- Vedanta Aluminium’s operations at Jharsuguda, BALCO and Lanjigarh, with upstream assets including the Sijimali bauxite mine.
- Why
- MOFSL expects stronger aluminum demand, tighter global supply, Indian import-substitution opportunities, greater vertical integration and lower production costs to support the stock.
- Brokerage
- MOFSL
- Rating
- Buy
- Target price
- Rs 540
- Implied upside
- 21%
- Current smelting capacity
- 2.9 MTPA across Jharsuguda and BALCO
- Expected smelting capacity
- 3 MTPA by FY28-end
- Captive power capacity
- 4.5 GW, plus 1.3 GW of renewable energy secured through long-term agreements
- Expected hot-metal cost
- $1,550-$1,600 per tonne