

Archive · 3 Jul 2025
Marico Predicts Gradual Improvement in Q1 FY26 with Strong Start
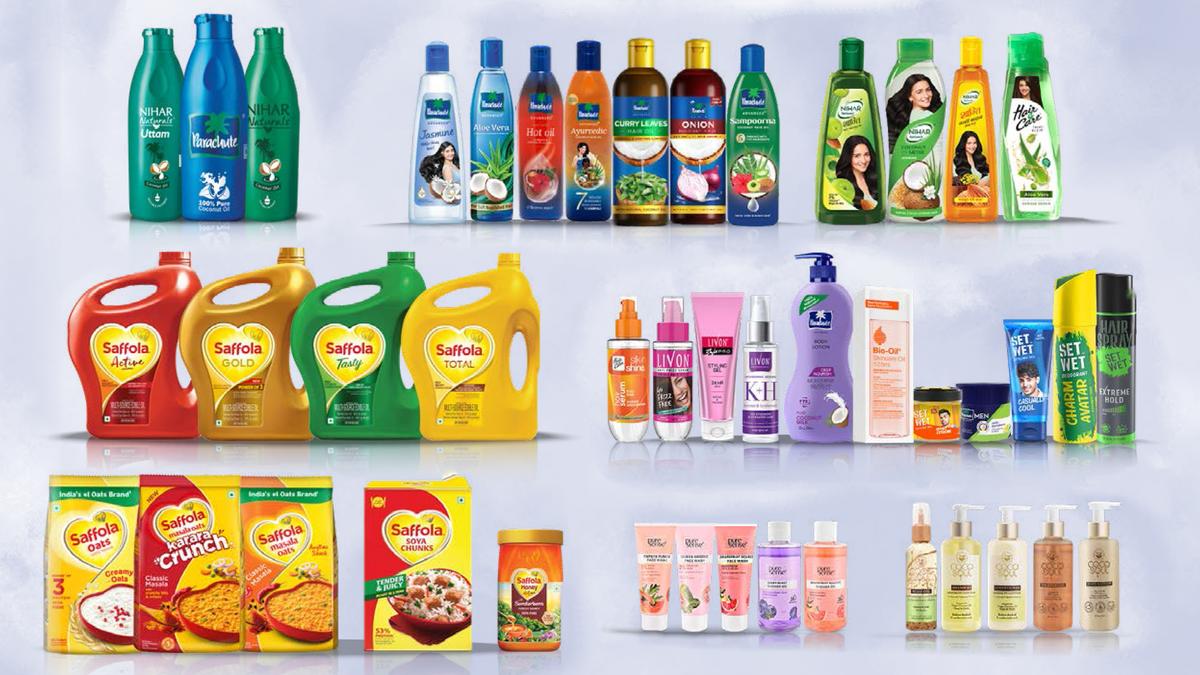
Marico, a company that makes things people buy, is doing okay.
They think things will get better soon because people in the countryside are buying more, and people in cities are still buying about the same amount.
They are selling more things than before.
However, it costs more to make their products right now, especially because of some ingredients like coconut oil.
The company is still investing in making their products well-known.
Some of their products, like hair oil, are doing well, especially in other countries.
Overall, the company is growing, even though some costs are high.

Marico expects gradual improvement in the coming quarters.
Underlying volume growth in India reached a multi-quarter high.
Gross margins are expected to be under pressure due to input costs.
Parachute volumes dipped due to high input costs.
The International business delivered high-teens constant currency growth.
- Who
- Marico Ltd.
- What
- Marico's business update for Q1 FY26.
- When
- Q1 FY26
- Where
- India and international markets.
- Why
- Due to improving rural trends, stable urban sentiment, easing inflation, favourable monsoon, and policy stimulus.
Challenges
Opportunities
Input Costs
Challenges
High input costs.
Opportunities
None given.
- Company
- Marico Ltd
- Expected Outlook
- Gradual improvement
- India Business Volume Growth
- Multi-quarter high
- Gross Margins
- Expected to be under pressure
- Saffola Oils Revenue Growth
- High twenties
- International Business Growth
- High-teens constant currency growth