

3 hrs ago
CBDT Extends Audit-Linked ITR Deadline to November 21
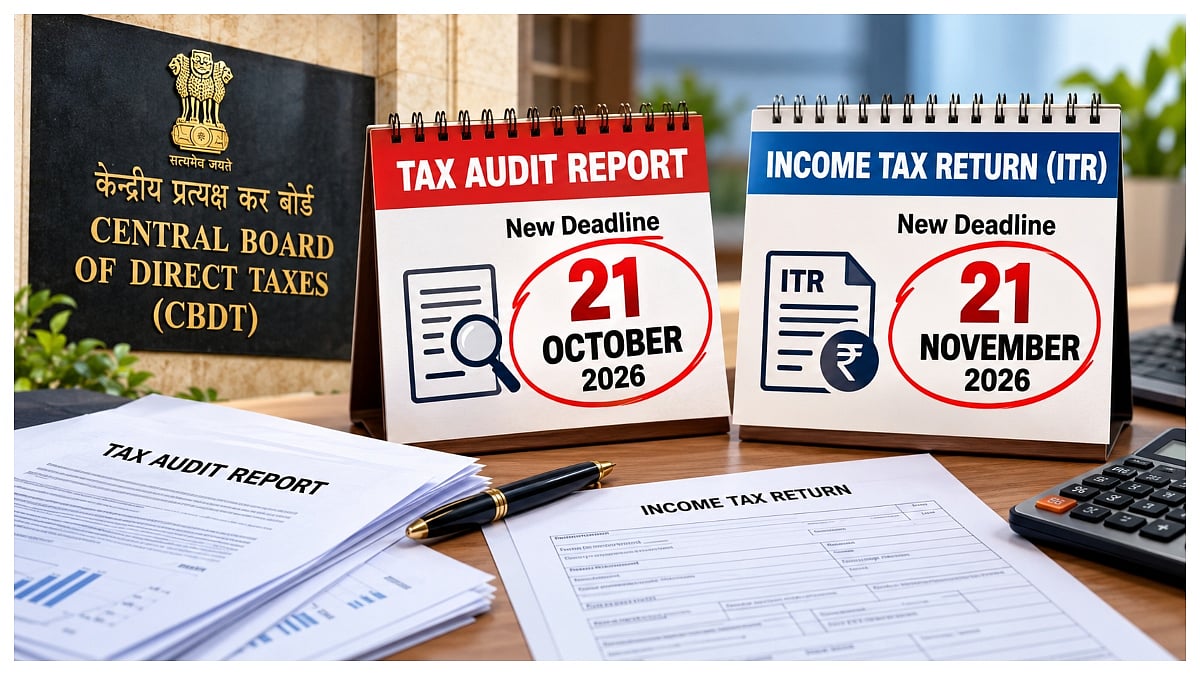
Some businesses and professionals must have their accounts checked by an auditor before filing their tax returns.
The CBDT has given these taxpayers more time for Assessment Year 2026-27.
Their income-tax return deadline moved from October 31 to November 21, 2026.
The deadline for submitting the tax audit report moved from September 30 to October 21, 2026.
The audit report must be submitted before the income-tax return.
This gives taxpayers and auditors 21 extra days for each task.
The extra time can help them finish audits and check their figures.
Regular salaried taxpayers who are not subject to tax audit are not covered by this extension.
Taxpayers who are unsure whether the rules apply to them can consult a tax professional.

The CBDT extended the ITR filing deadline for eligible audited taxpayers from October 31 to November 21, 2026.
The extension applies to income-tax returns for Assessment Year 2026-27.
The tax audit report deadline was moved from September 30 to October 21, 2026.
The changes provide an additional 21 days for each of the two compliance requirements.
The relief applies to taxpayers subject to tax audit, with an exception for those required to furnish a report under section 92E.
- Who
- The Central Board of Direct Taxes, taxpayers whose accounts require tax audit, and their auditors.
- What
- The deadlines for submitting tax audit reports and filing applicable income-tax returns were extended.
- Where
- New Delhi.
- When
- The announcement was made on September 28, 2026; the revised deadlines are October 21 and November 21, 2026.
- Why
- To provide additional time to complete audits, reconcile figures, and make accurate filings.
Key facts
- Authority
- Central Board of Direct Taxes (CBDT)
- Assessment year
- 2026-27
- Revised tax audit report deadline
- October 21, 2026
- Original tax audit report deadline
- September 30, 2026
- Revised ITR deadline
- November 21, 2026
- Original ITR deadline
- October 31, 2026
- Scope
- Taxpayers whose accounts are required to undergo tax audit, excluding those required to furnish a report under section 92E
Sources

Related news

Tax audit deadline remains September 30 as CAs seek extension
7.8 Crore ITRs Filed as Non-Audit Tax Deadline Ends

August 31 ITR Deadline: Belated Returns, Fees and Loss Rules

Tax Audit and ITR Deadlines Form Two-Stage Compliance Process

Who Must File Income-Tax Returns by 31 October?
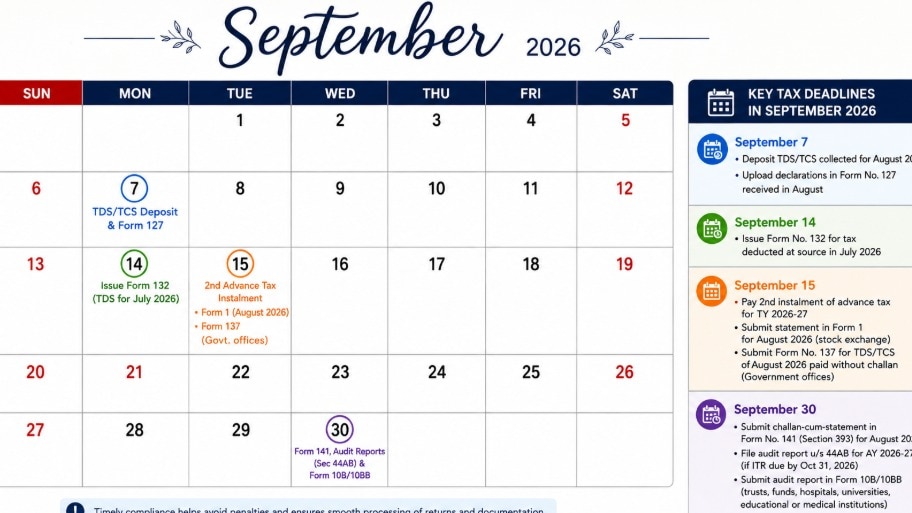
September 2026 Income Tax Deadlines Cover Payments, Audits
Three-Day Nationwide Bank Strike May Disrupt Branch Services
Bank Unions Defer Three-Day Strike After Late-Night IBA Talks
Sitharaman to Attend AIIB Annual Meeting During Qatar Visit
SBI Waives ATM Fees as Bank Strike Threatens Disruptions
