

Archive · 15 Sep 2026
Used-Car Loans Vary by Vehicle Value, Borrower Profile, Costs
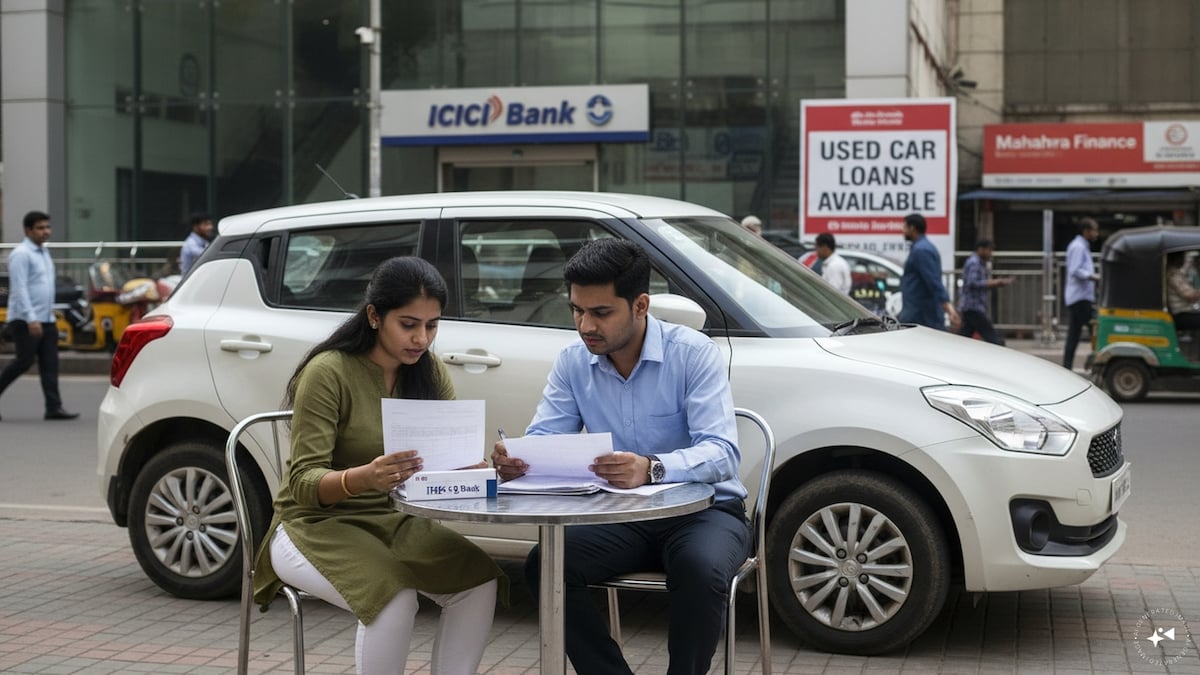
Getting a loan for a used car depends on both the car and the person borrowing money.
The lender checks details such as the car’s age, mileage, condition and paperwork.
It also checks the borrower’s income, credit history and ability to repay.
Lenders usually lend a smaller percentage for used cars than for new cars.
Used-car loans often have higher interest rates because older cars may be harder to sell again.
A longer loan term can make monthly payments smaller but increase the total interest paid.
Buyers should check all fees and whether interest is calculated on a reducing-balance or flat-rate basis.
They should choose based on the total cost, not only the lowest monthly payment.

Lenders assess a used car’s make, model, age, mileage, condition, insurance IDV, RC and RTO records.
Used-car loans typically finance about 70-85% of a vehicle’s value, compared with 85-95% for new cars.
Borrower income, existing obligations, credit history and repayment capacity influence the final loan amount.
Used-car loans generally carry higher interest rates because lenders assess depreciation and resale prospects.
Borrowers should compare total costs, including interest method, fees, tenure, prepayment charges and alternatives.
- Who
- Used-car borrowers and lenders, with views from Sumit Singla of rupyy and Kapil Makhija of MinEMI.
- What
- Lenders evaluate the vehicle and borrower before setting the loan amount, loan-to-value ratio, interest rate and terms.
- When
- When a buyer applies for financing for a used vehicle.
- Where
- The article discusses used-car financing in the Indian lending market.
- Why
- Used vehicles require independent valuation and resale assessment, while lenders also need to judge the borrower’s repayment capacity.
- Used-car loan-to-value
- Typically around 70-85% of the vehicle’s assessed value.
- New-car loan-to-value
- Typically around 85-95%.
- Example loan limit
- A vehicle valued at ₹10 lakh with 70% LTV could receive a loan of ₹7 lakh.
- Vehicle checks
- Make, model, age, mileage, condition, insurance IDV, registration certificate and RTO records.
- Borrower checks
- Income, existing obligations, credit history and repayment capacity.
- Additional costs
- Processing, documentation, valuation, RC or hypothecation, and prepayment or foreclosure charges.