10 hrs ago
Eight Financial Mistakes Indians Should Fix Before Moving Abroad
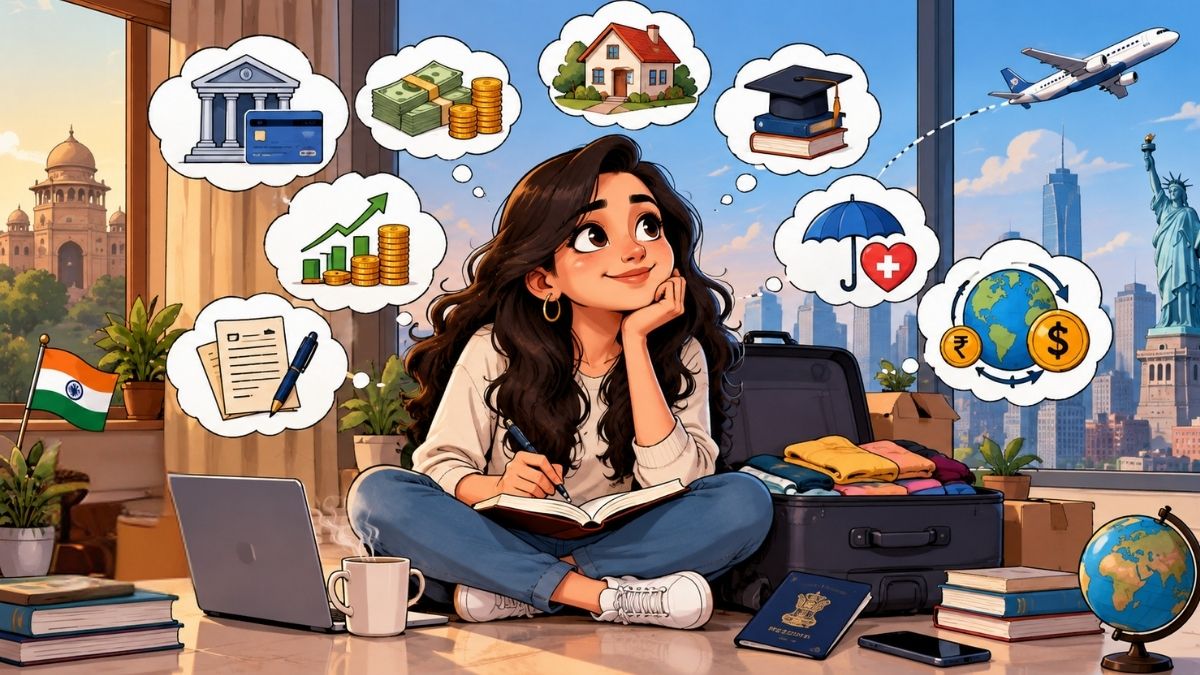
Moving to another country changes how a person must manage money in India.
Before leaving, they should check whether their bank accounts need to be changed to NRO or NRE accounts.
They should also save enough easily available money for about six months of expenses in the new country.
Planning for foreign currencies can help pay for rent, tuition, healthcare and other costs.
Indian investments should be reviewed rather than left running automatically.
Loans, EMIs, provident fund matters, insurance and nominations also need clear instructions.
People may have tax and reporting duties in both India and their new country.
Experts also suggest arranging help from a trusted person in India when needed.
Finally, families should plan for their financial future over the next 10 to 15 years, not only for the duration of a visa.

Convert resident savings accounts where required, complete KYC updates and review NRO and NRE arrangements before departure.
Build an accessible emergency fund covering about six months of essential expenses in the destination country.
Plan foreign-currency needs for housing, tuition, healthcare and daily expenses without transferring more money than necessary.
Review Indian investments, loans, EMIs, provident fund matters, insurance and nominations instead of leaving them unattended.
Understand cross-border tax obligations and create a long-term financial plan separate from the length of the visa.
- Who
- Indians preparing to move abroad and become non-resident Indians, with advice from Amit Gupta and Suresh Rajan.
- What
- Financial Express Digital outlines eight financial mistakes to address before relocating abroad.
- Where
- The preparation concerns finances in India and financial arrangements in the destination country, including the United States.
- When
- Before departure, particularly during the final 60 days after travel is confirmed and the visa is stamped.
- Why
- To avoid banking, liquidity, investment, loan, insurance and cross-border tax complications after relocation.
Key facts
- Emergency fund
- Experts recommend accessible funds covering about six months of essential or destination-country living expenses.
- Banking status
- Resident savings accounts may need to be redesignated, and KYC records updated, when residential status changes.
- NRO account
- Generally used by NRIs to manage income earned or assets held in India, subject to applicable repatriation rules and limits.
- NRE account
- Primarily used to hold overseas earnings in India; funds are generally repatriable.
- Indian investments
- Existing investments, including fixed deposits, mutual funds, equities, property and PPF, should be reviewed before departure.
- Tax planning
- Residential status, income, assets and destination-country rules can create tax and reporting obligations in both countries.
- Long-term horizon
- Families are advised to separate their financial timeline from the visa timeline and consider a 10-to-15-year plan.
Quotes
Suresh Rajan
Founder and Executive Chairman of LCR Capital Partners, discussing financial account updates.
“Your bank accounts, your investment accounts and the records your institutions hold on you are all built around the assumption that you live in India. Once that stops being true, they need to be brought into line.”
 financialexpress.com
“The visa has a length, so the plan quietly takes on the same length, and decisions that need a fifteen-year horizon end up being made on a three-year one.”
financialexpress.com
Sources
Related news

Six Essential Money Moves Before Moving Back to India

Practical Tips for Opening an NRI Bank Account Online

NRE vs NRO Accounts: Key Differences for Non-Resident Indians

PFRDA Explains NPS Rules for Indians Moving Abroad

India Bank Account Rules Differ for NRIs, OCIs, Foreigners
SEBI Plans Digital KYC Changes for Overseas Indian Investors
Gurugram Woman Biker Crash Prompts Calls For Safer Riding

India Target T20I Series Win Despite Fifth-Bowling Concerns

Hindi Pulp Writers Built a Mass Empire Beyond Prizes
TRAI Chairman Urges Safeguards As AI Transforms Telecom Networks
KEC International Secures Rs 1,303 Crore Transmission Orders