

Archive · 27 Jul 2026
Tamilnad Mercantile Bank Q1 profit rises 35%
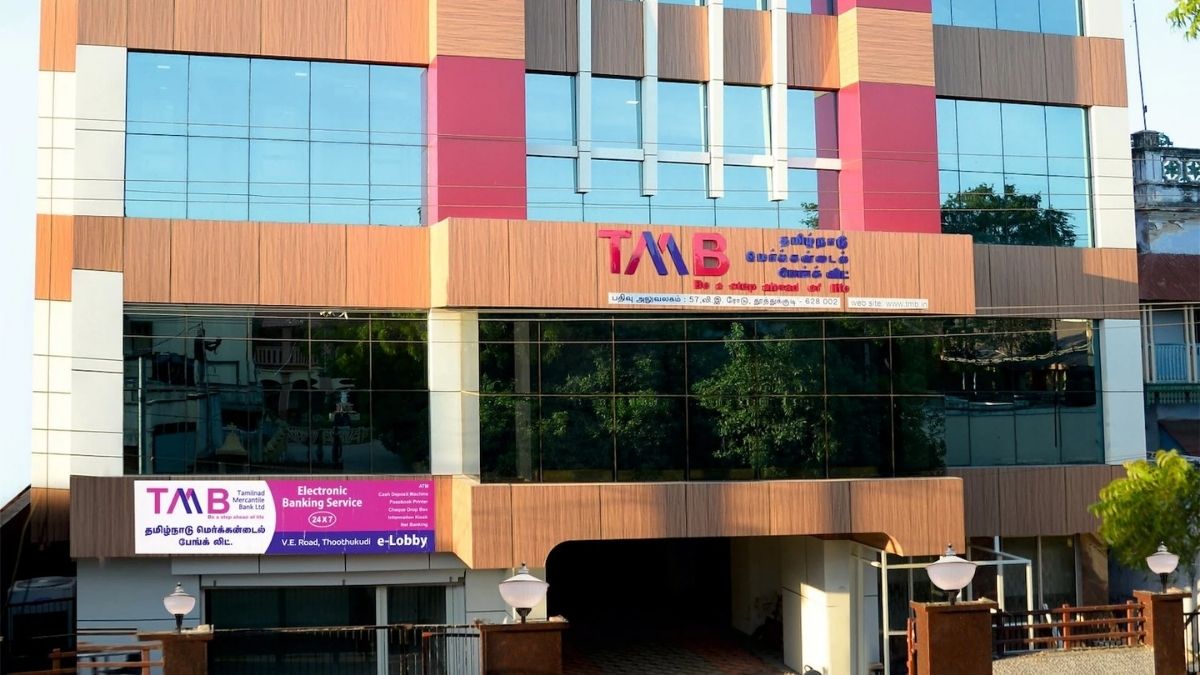
Tamilnad Mercantile Bank (TMB) had a really good first quarter in 2026.
They made a lot more money, about 35% more than the same time last year.
This is because they earned more from loans and other interest-related activities, and they spent less on operating costs.
Their shares even reached a 52-week high.
The bank's CEO, Salee S Nair, is happy with this performance, saying it shows the bank is strong and can handle changes in the economy.
They gave out more loans, especially to small businesses and farmers, and their loan quality improved.
They also got more deposits from customers.
Overall, it was a great quarter for TMB.

Tamilnad Mercantile Bank (TMB) reported a 35% year-on-year rise in net profit to ₹412 crore for Q1FY27.
Interest income rose 20% to ₹1,662.43 crore, while interest expenses increased 11% to ₹897.35 crore.
Net interest income (NII) jumped 32% to ₹765.08 crore, with net interest margin (NIM) expanding to 4.29%.
Credit growth outpaced deposit mobilisation, pushing the credit-deposit ratio up to 88.97%.
Gross non-performing assets (GNPA) declined to 0.69%, and net NPAs halved to 0.17%.
- Who
- Tamilnad Mercantile Bank (TMB)
- What
- Reported a 35% year-on-year rise in net profit to ₹412 crore for Q1FY27
- When
- Quarter ended June 2026
- Where
- India
- Why
- Driven by strong growth in interest income and lower operating expenses
Optimistic View
Cautious View
Profit Growth
Optimistic View
The 35% rise in net profit is a strong indicator of the bank's robust performance and resilience in a challenging macroeconomic environment.
Cautious View
While the profit growth is notable, it is important to monitor the sustainability of this growth in the face of potential economic uncertainties.
Credit-Deposit Ratio
Optimistic View
The increase in the credit-deposit ratio to 88.97% reflects strong credit growth, which is beneficial for the bank's expansion and profitability.
Cautious View
A high credit-deposit ratio could pose liquidity risks if not managed carefully, especially in a volatile economic climate.
Asset Quality
Optimistic View
The improvement in asset quality, with GNPA declining to 0.69% and net NPAs halving to 0.17%, demonstrates effective risk management and a healthy loan portfolio.
Cautious View
While asset quality has improved, continuous vigilance is necessary to ensure that the bank maintains these standards amid potential economic fluctuations.
- Net Profit
- ₹412 crore
- Interest Income
- ₹1,662.43 crore
- Interest Expenses
- ₹897.35 crore
- Net Interest Income (NII)
- ₹765.08 crore
- Net Interest Margin (NIM)
- 4.29%
- Credit-Deposit Ratio
- 88.97%
- Gross Advances
- ₹57,306 crore
- Deposits
- ₹64,409 crore
- Total Business
- ₹1.22 lakh crore
- Retail, Agriculture, and MSME Advances
- ₹54,083 crore
- Export Credit
- 3.53% of total MSME and corporate loan book
- Exposure to West Asian Countries
- ₹32.14 crore
- CASA Deposits
- ₹16,852 crore
- Term Deposits
- ₹47,557 crore
- Gross Non-Performing Assets (GNPA)
- 0.69%
- Net Non-Performing Assets (NPA)
- 0.17%