

Archive · 12 Aug 2025
How to Handle Unexpected Home Repair Costs
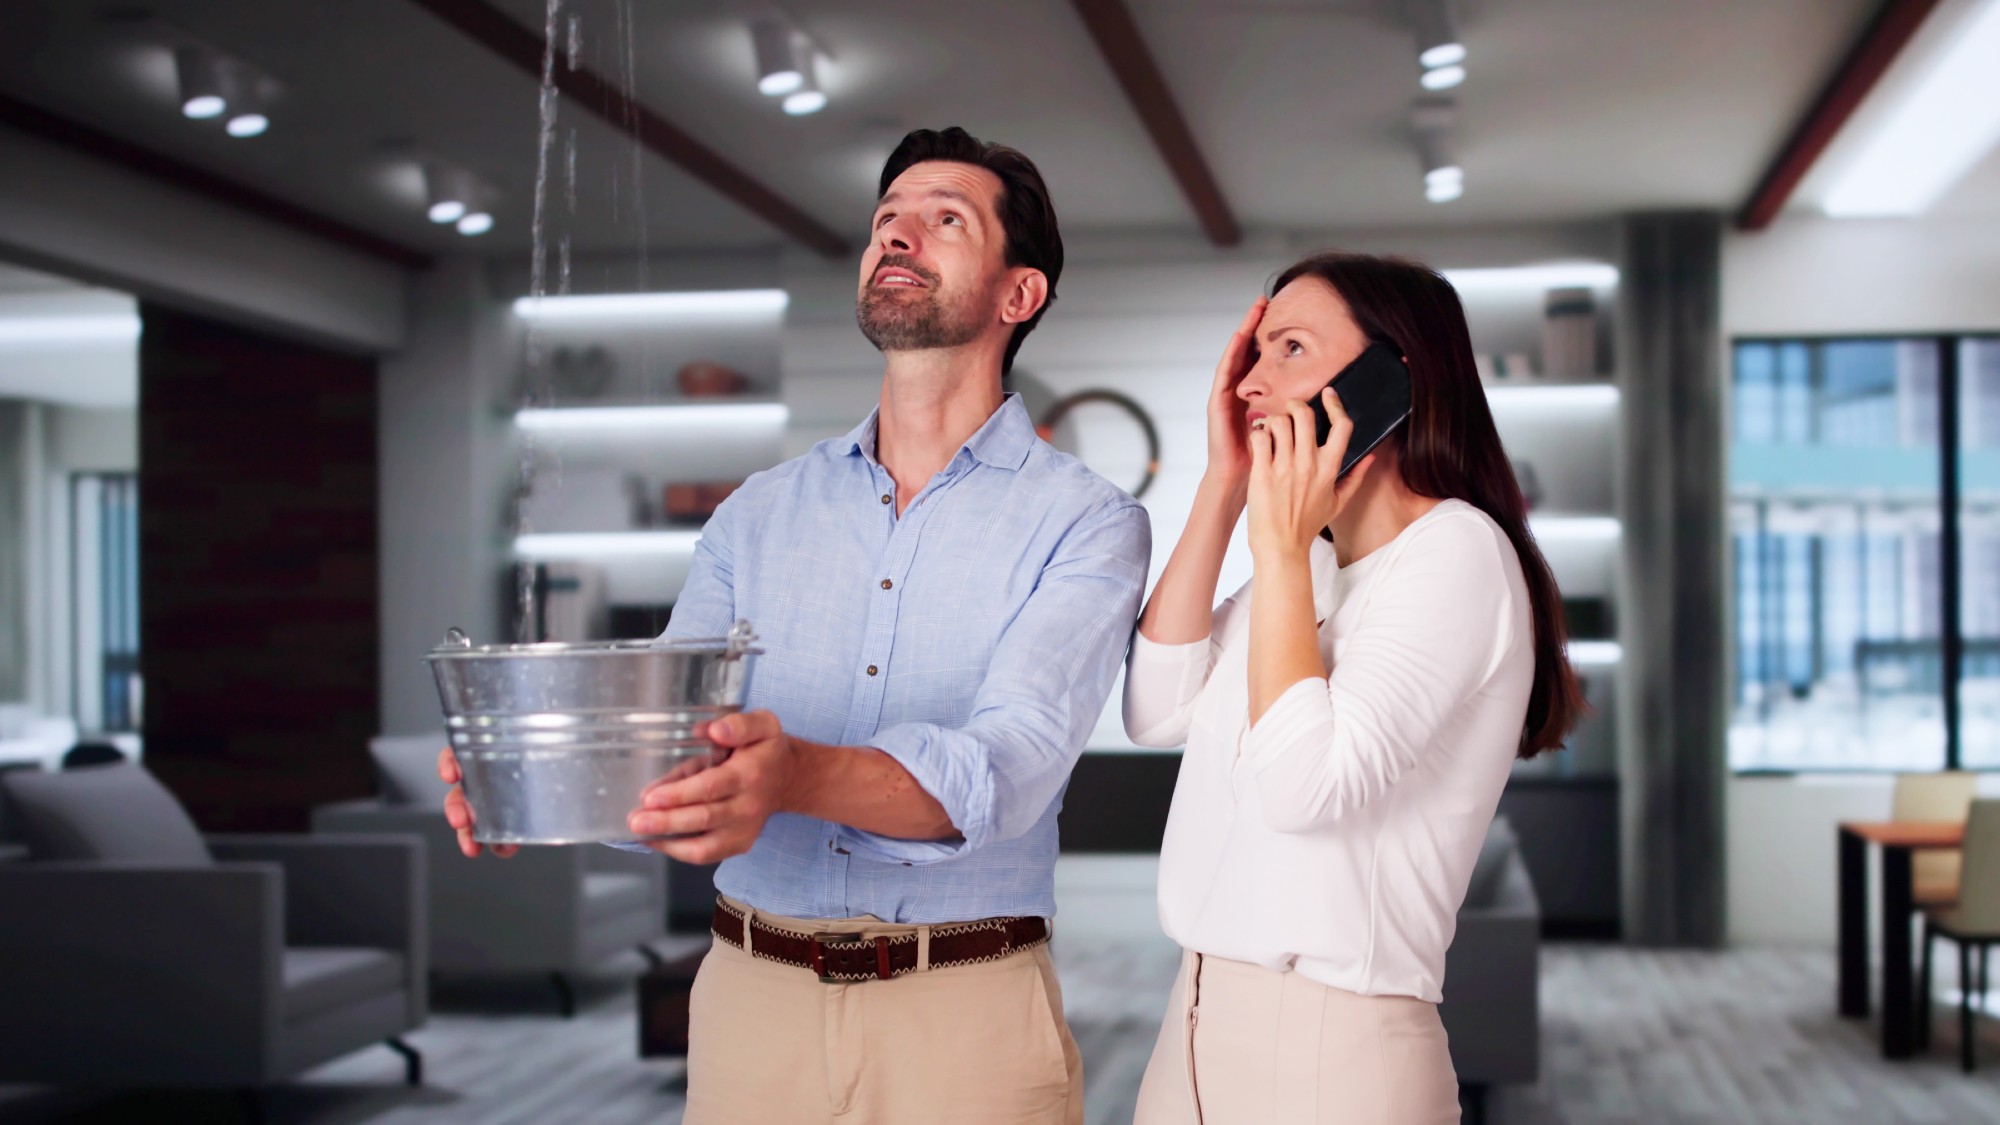
Sometimes your house breaks, like the roof leaks.
This costs money.
You can use your homeowner's insurance to pay for it but it can take a long time.
If that doesn't work, you can borrow money using your house as collateral or get a home improvement loan.
If you can't borrow, you can try community or government assistance programs.

Unexpected home repairs are common and can be costly.
Homeowners insurance is a first line of defense, but reimbursements may take up to 90 days.
Home equity loans or HELOCs offer access to funds, but can risk home ownership.
Home improvement loans are an option, though rates may be higher.
Community or government assistance programs may provide financial aid.
- Who
- Homeowners.
- What
- Ways to cover the costs of unexpected home repairs.
- When
- N/A
- Where
- N/A
- Why
- To maintain their homes.
- Common Issues
- Water/roof damage, windows, and doors.
- Homeowners Spending
- 46% spend over $5,000.
- Homeowner Insurance Reimbursement
- May take up to 90 days
- Home Equity Loan
- Lump sum with fixed interest rates.
- HELOC
- Open line of credit with variable interest rates.
- Home Improvement Loan
- Unsecured personal loans, may offer fast funding.