

2 hrs ago
Supreme Court Stays Ruling Against Income Tax Section 147A
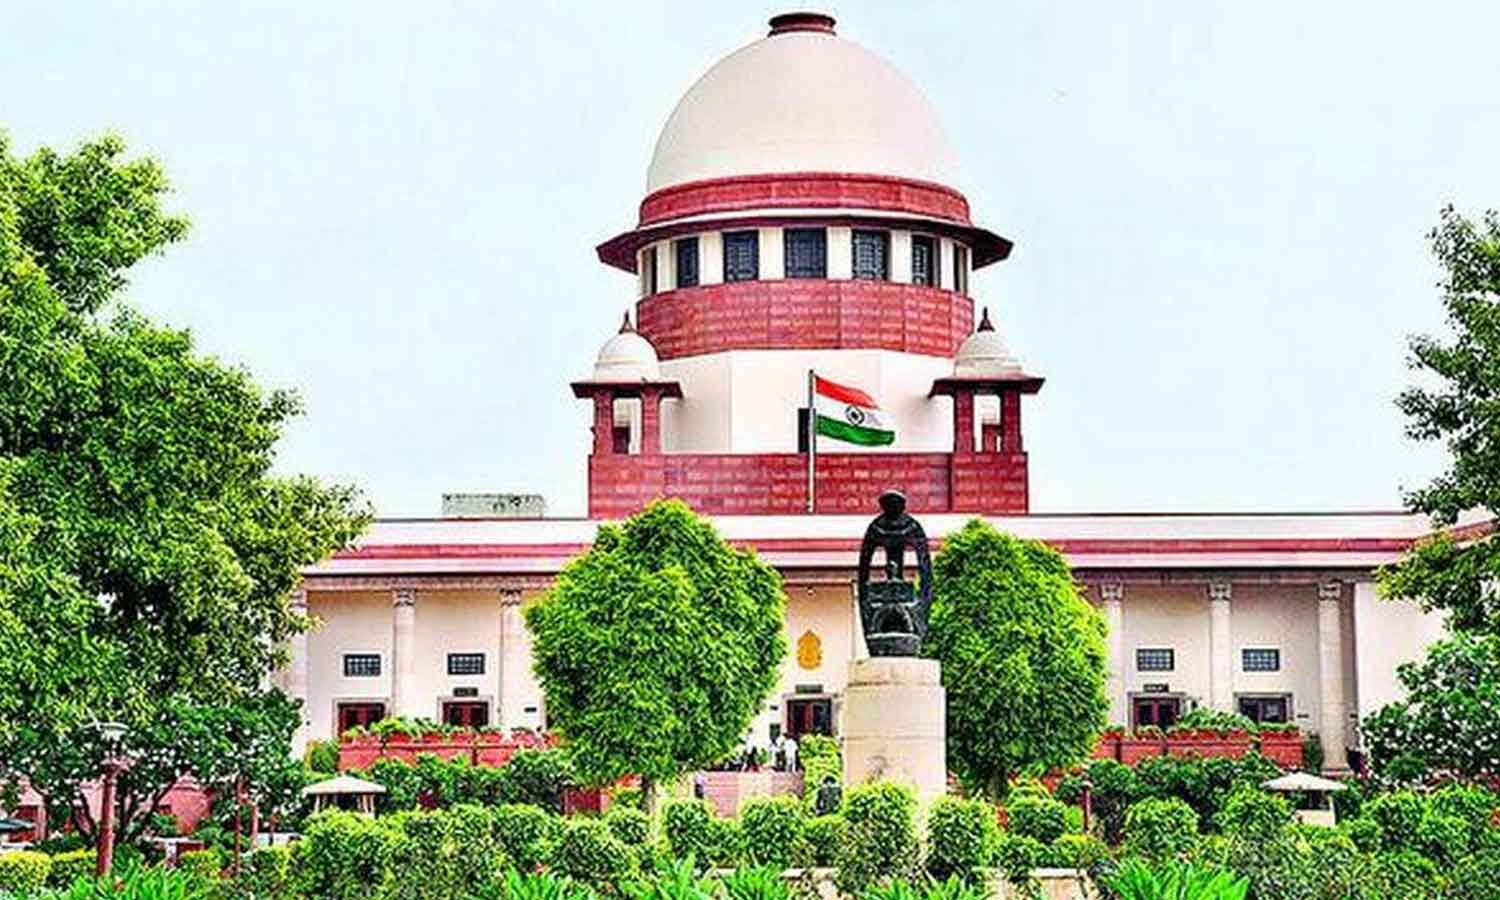
The Punjab and Haryana High Court had said that a tax law provision called Section 147A was unconstitutional.
It also cancelled some tax reassessment notices.
The Union government and tax authorities disagreed and appealed to the Supreme Court.
On Friday, the Supreme Court temporarily paused the High Court decision.
This means the related tax assessment proceedings must not continue for now.
The Supreme Court has not yet made a final decision about whether Section 147A is valid.
The dispute also concerns whether tax notices were properly assigned through a random and faceless system.
The Supreme Court will hear the main case on December 3.

The Supreme Court stayed the Punjab and Haryana High Court ruling declaring Section 147A of the Income Tax Act unconstitutional.
The stay means related assessment proceedings cannot continue until the Supreme Court finally decides the case.
The case arose from a challenge to Section 147A, introduced retrospectively from April 1, 2021, through the Finance Bill, 2026.
The High Court had also set aside Section 148 reassessment notices issued without randomised allocation and faceless processing.
The Supreme Court scheduled the matter for final hearing on December 3.
- Who
- The Supreme Court, the Union government, income tax authorities, and petitioners affected by reassessment notices.
- What
- The Supreme Court stayed a Punjab and Haryana High Court judgment declaring Income Tax Act Section 147A unconstitutional and cancelling certain reassessment notices.
- Where
- The proceedings involve the Punjab and Haryana High Court and the Supreme Court in New Delhi.
- When
- The interim stay was issued on Friday; the matter is listed for final hearing on December 3. Section 147A was introduced retrospectively from April 1, 2021.
- Why
- The Union government and tax authorities challenged the High Court ruling, which had rejected Section 147A and notices issued without the required randomised allocation and faceless process.
Petitioners and High Court Position
Union Government and Tax Authorities
Validity of Section 147A
Petitioners and High Court Position
The Punjab and Haryana High Court declared Section 147A unconstitutional, after petitioners challenged it under Articles 14, 19(1)(g), and 265 of the Constitution.
Union Government and Tax Authorities
The Union government, the Central Board of Direct Taxes, the Deputy Commissioner of Income Tax, and the National Faceless Assessment Centre appealed against the High Court ruling.
Issuance of reassessment notices
Petitioners and High Court Position
The High Court held that notices under Section 148 were unsustainable when issued by jurisdictional Assessing Officers without randomised allocation and faceless processing under Section 151A.
Union Government and Tax Authorities
The tax authorities are seeking to overturn the High Court judgment and defend the challenged reassessment framework; the Supreme Court has stayed the ruling while considering the appeal.
Key facts
- Supreme Court bench
- Justices J.B. Pardiwala and K. Vinod Chandran
- High Court judgment date
- September 10
- Interim direction
- Assessment proceedings cannot proceed until final disposal of the main matter
- Next hearing
- December 3
- Disputed provision
- Section 147A of the Income Tax Act, 1961
- Related notices
- Reassessment notices issued under Section 148
- Allocation requirement
- The dispute concerns randomised allocation and faceless proceedings under Section 151A and its March 29, 2022 scheme
Quotes
Supreme Court bench led by Justice J.B. Pardiwala
The Supreme Court bench hearing the Union government’s challenge to the High Court judgment
“The impugned judgment and order passed by the High Court shall remain stayed on the condition that the assessment proceedings shall not proceed further till the final disposal of the main matter.”
 thehansindia.com
“no hesitation to declare Section 147A of the Act to be unconstitutional”
thehansindia.com
Sources
Related news

Punjab and Haryana High Court Strikes Down Retrospective Tax Reassessment Provision
High Court Strikes Down Tax Reassessment Provision After Lawyer’s Fight

Supreme Court to Hear Challenge Over Tax Reassessment Notices
ITAT Quashes Reassessment Over Rs 41.45 Lakh Deposits

Jaipur ITAT Upholds 87A Rebate on STCG for AY 2024-25

₹5.31 lakh ITAT Delhi refund allowed despite missing original return
Nithari Case Acquitted Surendra Koli Found Dead in Haridwar
Centre Lowers NEET-SS Cut-Off, Opening Special Stray Vacancy Counselling

Supreme Court Seeks Permanent NTA Reforms After NEET Leak
Nilekani Panel to Submit Interim NEET Reforms Report Soon
