7 hrs ago
ITAT Deletes Tax Additions on Rs 2.47 Crore Deposits
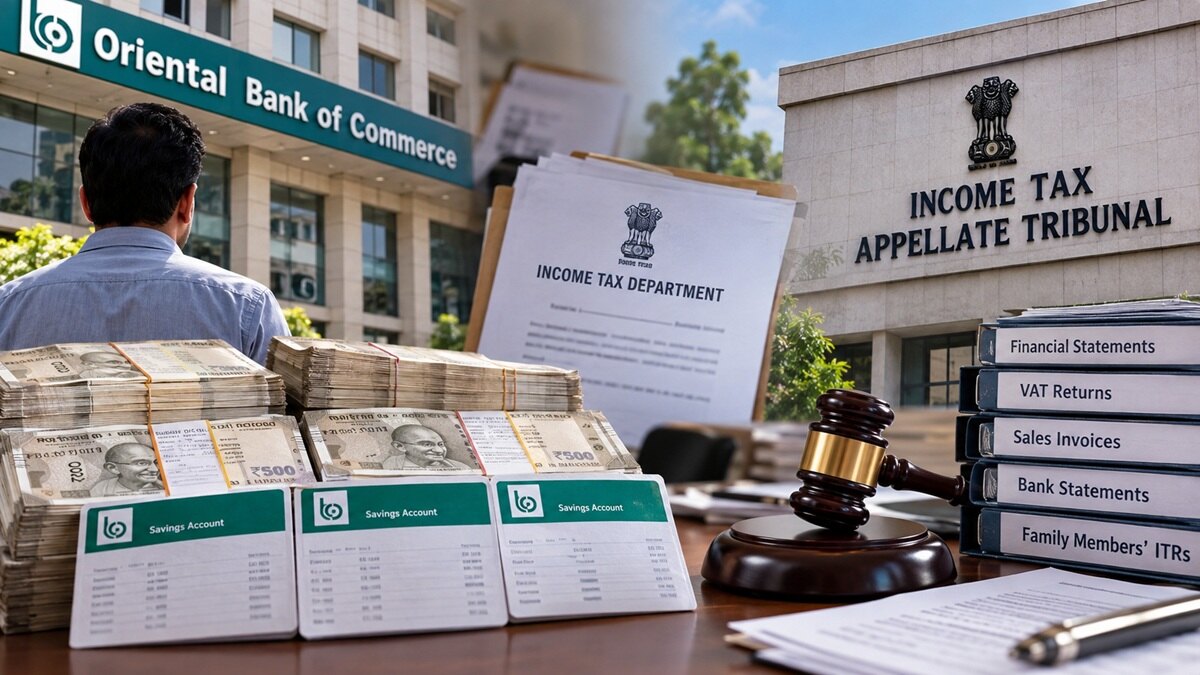
Rakesh Kumar deposited a large amount of cash in his bank accounts during the demonetisation period.
Tax officials asked him to explain where the money came from.
Kumar said much of it came from sales at his medicines business.
He also said some money came from bank withdrawals, his own savings and savings held by family members.
He showed documents such as bank statements, tax returns, sales bills and business accounts.
The tax officials were not satisfied and treated the money as unexplained income.
The ITAT looked at the documents and found that the officials had not identified specific mistakes in them.
It therefore removed the tax additions totaling about Rs 3.32 crore.
The ruling applies to the facts and evidence in this particular case, not automatically to every large cash deposit.

The Delhi ITAT deleted tax additions totaling Rs 3.32 crore against Rakesh Kumar.
Kumar deposited Rs 2,47,91,057 in three Oriental Bank of Commerce accounts during 2016-17.
He attributed Rs 1,64,37,357 to pharmaceutical business cash sales and the rest to withdrawals, personal savings and family savings.
Tax authorities questioned the cash sales, business expenses and the source of Rs 72 lakh attributed to five family members.
The Tribunal found no specific defects in the submitted records and said the authorities had not established that the money was unaccounted.
- Who
- Rakesh Kumar, the Income Tax Department, and the Delhi Bench of the Income Tax Appellate Tribunal.
- What
- The ITAT deleted tax additions totaling Rs 3,31,60,827 relating to cash deposits and other claimed cash sources.
- Where
- The case was decided by the Delhi Bench of the Income Tax Appellate Tribunal and involved three accounts at Oriental Bank of Commerce.
- When
- The deposits and related transactions concerned financial year 2016-17, including the demonetisation period after November 8, 2016; the case concerned assessment year 2017-18.
- Why
- The Tribunal found that Kumar had submitted supporting records and that the lower tax authorities had not identified specific defects or proved that the funds were unaccounted.
Taxpayer and Tribunal
Tax Authorities
Source of business deposits
Taxpayer and Tribunal
Kumar said Rs 1,64,37,357 came from pharmaceutical retail cash sales and submitted financial statements, VAT returns, bank records and sales invoices. The ITAT found the deposits directly correlatable with the sales and noted that the books had not been rejected.
Tax Authorities
The Assessing Officer and CIT Appeals questioned whether the reported sales and cash deposits were adequately reconciled with sales, stock, cash balances and business expenses.
Cash withdrawals and savings
Taxpayer and Tribunal
Kumar attributed Rs 83,69,770 to Rs 9,23,500 in bank withdrawals, Rs 2,46,270 in personal savings and Rs 72 lakh in savings of five family members. The ITAT found the supporting bank records and other evidence sufficient.
Tax Authorities
The Assessing Officer questioned why cash had been withdrawn and redeposited, and sought more evidence about the family members' income, businesses, bank accounts and sources of cash.
Strength of documentary evidence
Taxpayer and Tribunal
The ITAT said the authorities had not identified specific defects in the documents or produced evidence showing that the money was unaccounted.
Tax Authorities
The tax authorities treated the explanations as insufficient, including describing the family-savings explanation as a device to explain the deposits.
Key facts
- Cash deposited
- Rs 2,47,91,057 in three savings accounts
- Business explanation
- Rs 1,64,37,357 was attributed to cash sales from a retail pharmaceutical and medicines business
- Additional disputed amount
- Rs 83,69,770 attributed to withdrawals, personal savings and family savings
- Total tax addition deleted
- Rs 3,31,60,827
- Documents submitted
- Audited financial statements, VAT returns, bank statements, sales invoices, tax records and family-member declarations
- Case reference
- Income Tax Appellate Tribunal, Delhi Bench, ITA No. 2746/Del/2026
- Tax provisions involved
- Section 68 and Section 115BBE of the Income Tax Act
Quotes
Kinjal Bhuta
Chartered accountant and advocate, and Joint Secretary of the Bombay Chartered Accounts Society
“The ruling underscores that taxpayers should preserve a documentary trail like bank statements, audited financials, VAT returns and sales invoices and income tax returns of relatives/friends to establish the source of cash deposits.”
 financialexpress.com
Sources
Related news

ITAT Partly Accepts Explanation For ₹32 Lakh Cash Deposit

Delhi ITAT Rejects Tax on ₹34.8 Lakh Cash Balance

Bengaluru Woman Wins Tax Dispute Over ₹25 Lakh Deposit

ITAT Orders Fresh Review of ₹20.33 Lakh Cash Deposits

Mumbai entrepreneur wins relief over cash credit-card payments

Tyagi Surrenders in Satya Niketan Building Collapse Case

AAP Demands Public Disclosure of Satya Niketan PG Documents
Satya Niketan Collapse Raises Questions Over Illegal Construction, Safety
Satya Niketan Building Collapse Death Toll Reaches Seven